Portugal: 2027 budget bill would extend the VAT exemption on agricultural inputs to 31 December 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Portugal as they stand today, see the Portugal guide →
- Jurisdiction
- Portugal
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 8 October 2026
- Effective
- 1 January 2027
- Authority
- Assembleia da República
- Systems
- ERP, Invoicing, Tax engine, POS
- Verified
- Fetched from official source · high confidence
Suppliers of fertilisers, soil correctives, animal feed, cereals and seeds normally used in agricultural production in Portugal, and the farmers who buy them.
No action — monitoring only.
ERPInvoicingTax enginePOS
Article 138(6)(a) of the Government State Budget bill for 2027 (Proposta de Lei n.º 110/XVII/2.ª, approved in Council of Ministers 8 October 2026; general debate 27-28 October 2026; entry into force 1 January 2027) extends until 31 December 2027 the provisions of article 4 of Lei n.º 10-A/2022 of 28 April, the temporary VAT exemption, with right to deduct input VAT, on supplies of fertilisers and soil correctives, feed flours, cereals and seeds for livestock, and certain other goods normally used in agricultural production. The exemption currently runs to 31 December 2026 under the 2026 State Budget law. The bill articulado contains no amendment to the VAT Code rates.
What changed in detail
This is a budget bill, not law. Article 138(6)(a) of the Government’s State Budget bill for 2027 (Proposta de Lei n.º 110/XVII/2.ª, approved in the Council of Ministers on 8 October 2026, with the general debate scheduled for 27 and 28 October 2026) would extend until 31 December 2027 article 4 of Lei n.º 10-A/2022 of 28 April.
Article 4 of Lei n.º 10-A/2022 exempts from VAT, with the right to deduct input VAT, supplies of fertilisers and soil correctives, and of flours, cereals and seeds and other products for feeding livestock, poultry and other animals, where these goods are normally used in agricultural production. The exemption currently runs to 31 December 2026 under the 2026 State Budget law.
The bill would enter into force on 1 January 2027. Its articles contain no amendment to the VAT Code rates.
What it means
The relief has been rolled forward year by year since 2022, and this bill continues that pattern. Until the budget is approved and published, suppliers have no legal basis to keep applying the exemption from 1 January 2027, so invoicing systems should keep the 31 December 2026 end date in place and be ready to extend it once the State Budget law appears in the Diário da República.
Proof
6 - É prorrogado, até 31 de dezembro de 2027, o disposto: a) No artigo 4.º da Lei n.º 10-A/2022, de 28 de abril;6 - The following are extended until 31 December 2027: a) Article 4 of Law No. 10-A/2022 of 28 April;
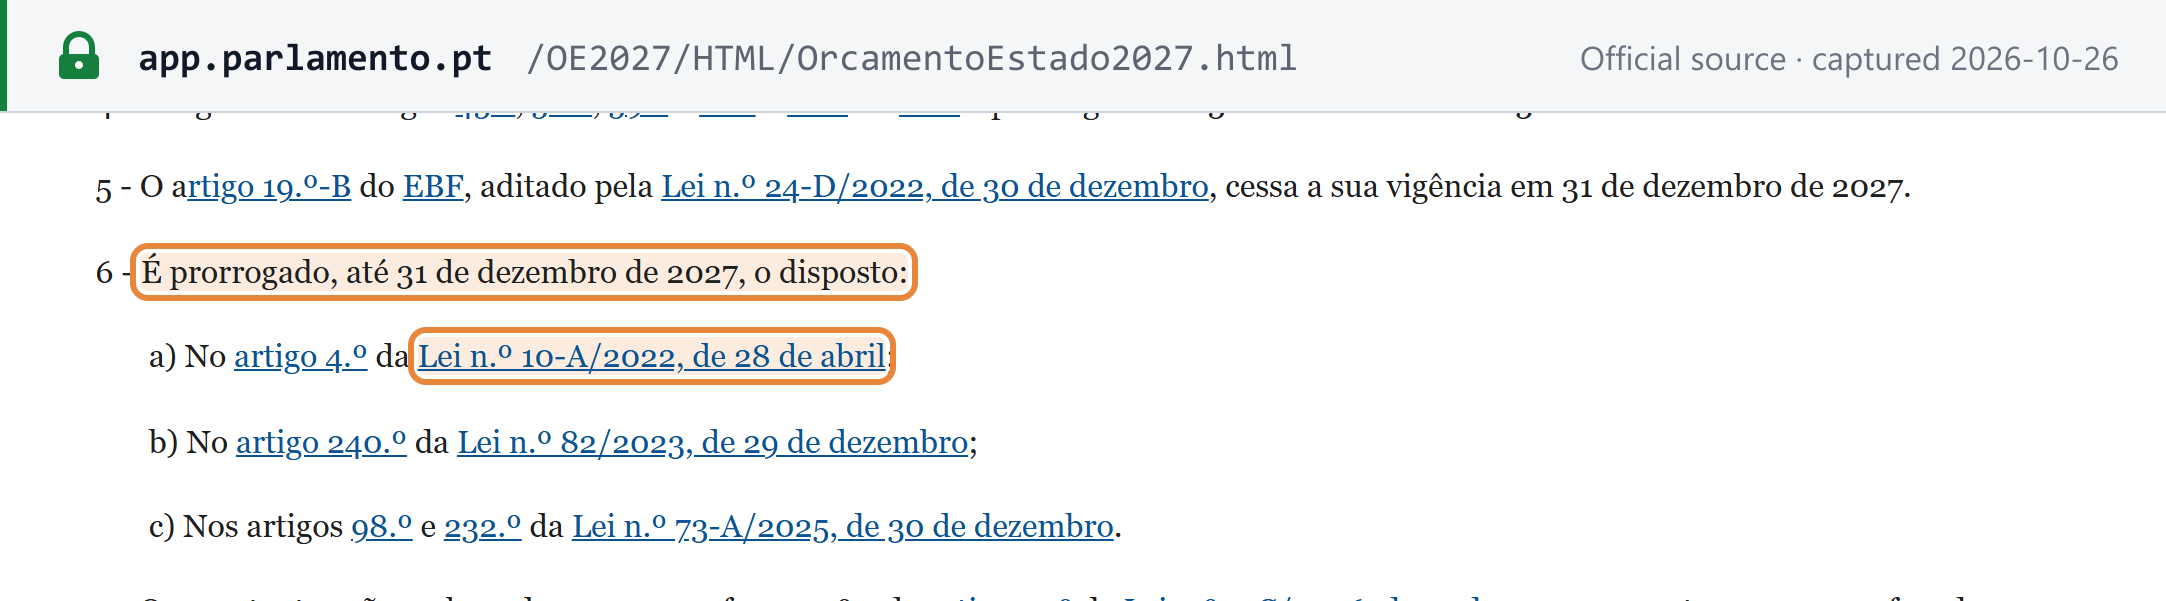 Source snapshot of the official page. Open full size ↗