Serbia lets VAT payers under RSD 8,000,000 turnover deregister from 1 January 2027
- Jurisdiction
- Serbia
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 1 September 2026
- Effective
- 1 January 2027
- Authority
- Narodna skupština Republike Srbije (National Assembly of Serbia)
- Systems
- Tax engine, ERP
- Verified
- Fetched from official source · high confidence
VAT payers in Serbia whose turnover in the preceding 12 months did not exceed RSD 8,000,000.
Review VAT deregistration eligibility and procedure (RSD 8,000,000 turnover test) and tax-period-change timing ahead of 1 January 2027.
Tax engineERP
Serbia's National Assembly adopted the Law on Amendments and Supplements to the Law on Value Added Tax (act no. 2585-26), part of a wider tax-law package published together in Sluzbeni glasnik RS br. 80/2026 of 1 September 2026. The law adds a new Article 38a allowing a VAT payer whose total turnover in the preceding 12 months did not exceed RSD 8,000,000 to apply for termination of VAT liability, with the tax authority processing deregistration and issuing a deregistration certificate where conditions are met; it also revises tax-period-change procedures and VAT registration/deregistration forms. Per Article 17, the law enters into force on the eighth day after publication, with general application from 1 January 2027 (Article 1 applies from entry into force; Article 7 applies from 15 December 2026).
What changed in detail
Serbia’s National Assembly adopted the Law on Amendments and Supplements to the Law on Value Added Tax (act no. 2585-26), part of a wider tax-law package published in Službeni glasnik RS br. 80/2026 of 1 September 2026. A new Article 38a lets a VAT payer whose total turnover in the preceding 12 months did not exceed RSD 8,000,000 apply for termination of VAT liability; the tax authority processes deregistration and issues a deregistration certificate where conditions are met. The law also revises tax-period-change procedures and VAT registration/deregistration forms. Per Article 17, the law enters into force on the eighth day after publication, with general application from 1 January 2027 (Article 1 applies from entry into force; Article 7 applies from 15 December 2026).
What it means
This gives small VAT payers a formal exit route they did not previously have — the RSD 8,000,000 test mirrors the registration threshold, so a business that drops below it can now close the loop instead of staying VAT-registered indefinitely. Deregistration is not automatic: it requires an application, and the taxpayer chooses the effective date within the rules. Review deregistration eligibility and the related tax-period-change timing ahead of the 1 January 2027 general-application date.
Proof
Na zahtev obveznika koji u prethodnih 12 meseci nije ostvario ukupan promet veći od 8.000.000 dinara, uključujući i obveznika iz člana 33. stav 5. i člana 34. stav 8. ovog zakona, za prestanak obaveze plaćanja PDV, poreski organ sprovodi postupakAt the request of a taxpayer who has not achieved total turnover exceeding RSD 8,000,000 in the preceding 12 months, including a taxpayer under Article 33(5) and Article 34(8) of this law, for termination of the obligation to pay VAT, the tax authority conducts the procedure
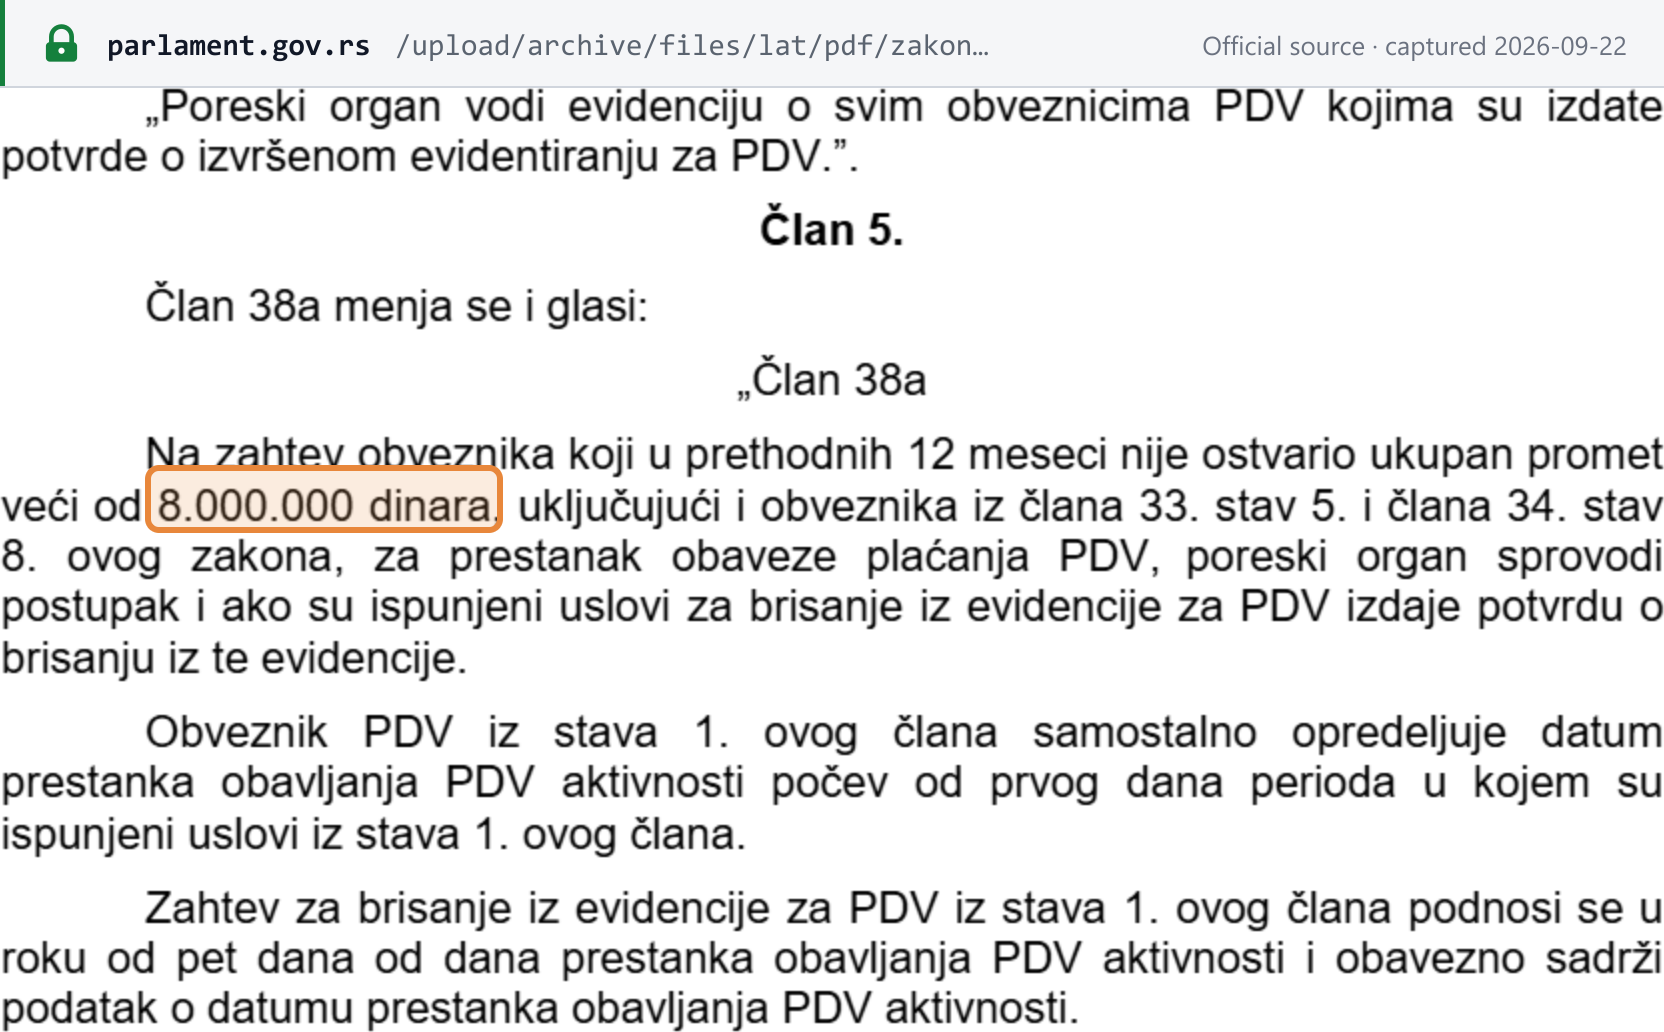 Source snapshot of the official page. Open full size ↗