Sweden proposes ViDA step 2 VAT changes from 1 January 2027 in Proposition 2025/26:278
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Sweden as they stand today, see the Sweden guide →
- Jurisdiction
- Sweden
- Tax
- VAT
- Change type
- Registration
- Status
- Proposed
- Impact
- Watch
- Announced
- 9 June 2026
- Effective
- 1 January 2027
- Authority
- Sveriges riksdag
- Systems
- Tax engine, E-commerce, Reporting
- Verified
- Fetched from official source · medium confidence
Businesses engaged in cross-border supplies subject to Swedish VAT.
Plan for the 1 January 2027 ViDA second-step rules (OSS/IOSS reporting, chargeable event) pending the Riksdag vote after the 2026 election.
Tax engineE-commerceReporting
Government Proposition 2025/26:278 'Teknisk översyn av mervärdesskattereglerna vid gränsöverskridande handel' (dated 4 June 2026; Lagrådet raised no objection) proposes amendments to the VAT Act (2023:200) implementing the second step of the ViDA Directive (EU) 2025/516, covering cross-border trade rules, the chargeable event and the time VAT becomes due, with entry into force proposed for 1 January 2027. Riksdag status: referred to the Tax Committee (Skatteutskottet) and not yet decided.
What changed in detail
This is a government proposition, not law. Proposition 2025/26:278, “Teknisk översyn av mervärdesskattereglerna vid gränsöverskridande handel” (technical review of the VAT rules on cross-border trade), is dated 4 June 2026 and was tabled in the Riksdag on 9 June 2026. The Council on Legislation (Lagrådet) raised no objection.
It proposes amendments to the VAT Act (2023:200) to implement the second step of the ViDA Directive (EU) 2025/516. The amendments cover the cross-border trade rules, the chargeable event, the time at which VAT becomes due and the special schemes. Entry into force is proposed for 1 January 2027.
The proposition has been referred to the Tax Committee (Skatteutskottet). As of 5 October 2026 there was no committee report and the Riksdag had not decided.
What it means
The 1 January 2027 date is a proposal and depends on the Riksdag adopting the text. Businesses with cross-border flows should plan against it, since the changes touch when VAT falls due, but should not change systems on the assumption that the wording is final.
The absence of an objection from Lagrådet lowers the risk of substantive redrafting, though it does not guarantee adoption in the proposed form.
Proof
Lagändringarna föreslås träda i kraft den 1 januari 2027.The legislative amendments are proposed to enter into force on 1 January 2027.
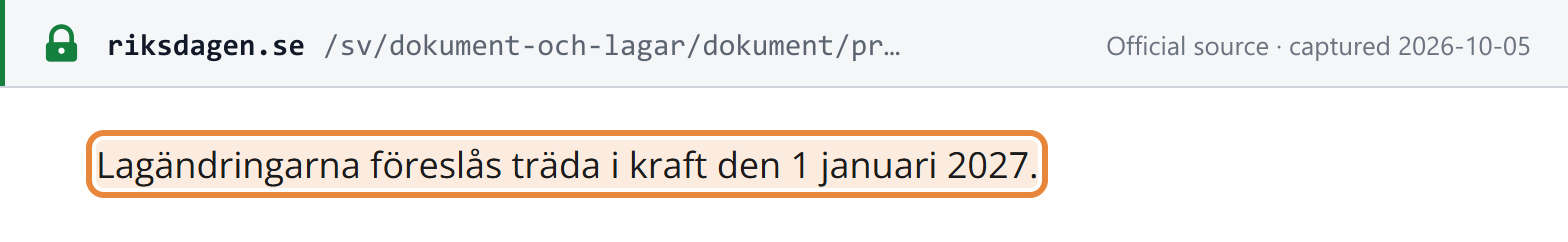 Source snapshot of the official page. Open full size ↗