Switzerland defers the VAT portal obligation for flat-rate and group taxpayers to 2027
- Jurisdiction
- Switzerland
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Effective
- 1 January 2027
- Authority
- Eidgenössische Steuerverwaltung (ESTV)
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
VAT-registered businesses using the flat-rate or lump-sum method, VAT groups, and taxpayers deregistering as a taxable person.
VAT-registered businesses using the flat-rate/lump-sum method, VAT groups, and taxpayers planning deregistration must be ready to use the ESTV online portal for these procedures from 1 January 2027.
Tax engineReporting
Switzerland's Federal Tax Administration (ESTV) confirms that the portal obligation (Portalpflicht) for the flat-rate and lump-sum tax-rate methods, VAT group taxation, and deregistration as a taxable person -- part of the partially revised VAT Ordinance (MWSTV) that otherwise entered into force 1 January 2025 alongside the revised VAT Act -- is deferred and will only be introduced on 1 January 2027.
What changed in detail
The partially revised VAT Ordinance (MWSTV) entered into force alongside the revised VAT Act on 1 January 2025, but the Federal Tax Administration (ESTV) confirms one exception: the Portalpflicht — the mandatory use of the ESTV online portal — for the flat-rate and lump-sum tax-rate methods, VAT group taxation, and deregistration as a taxable person, is deferred and will only be introduced on 1 January 2027.
Every other part of the revised MWSTV, including the general portal requirements that already took effect in 2025, is unaffected by this deferral.
What it means
Businesses using the flat-rate or lump-sum scheme, VAT groups, and anyone planning to deregister have until 2027 before the portal channel becomes mandatory for those specific procedures — the general portal obligation elsewhere in the VAT Ordinance already applies and is not touched by this deferral. Confirm which of your VAT procedures actually rely on flat-rate/lump-sum treatment, group taxation, or deregistration before assuming the extra runway applies to your filings generally.
Proof
Eine Ausnahme bildet die Portalpflicht für die Bereiche Saldo- und Pauschalsteuersatzmethode, Gruppenbesteuerung sowie die Abmeldung als steuerpflichtige Person, die erst auf den 1. Januar 2027 eingeführt wird.An exception is the portal obligation for the balance and flat-rate methods, group taxation, and deregistration as a taxable person, which will only be introduced on 1 January 2027.
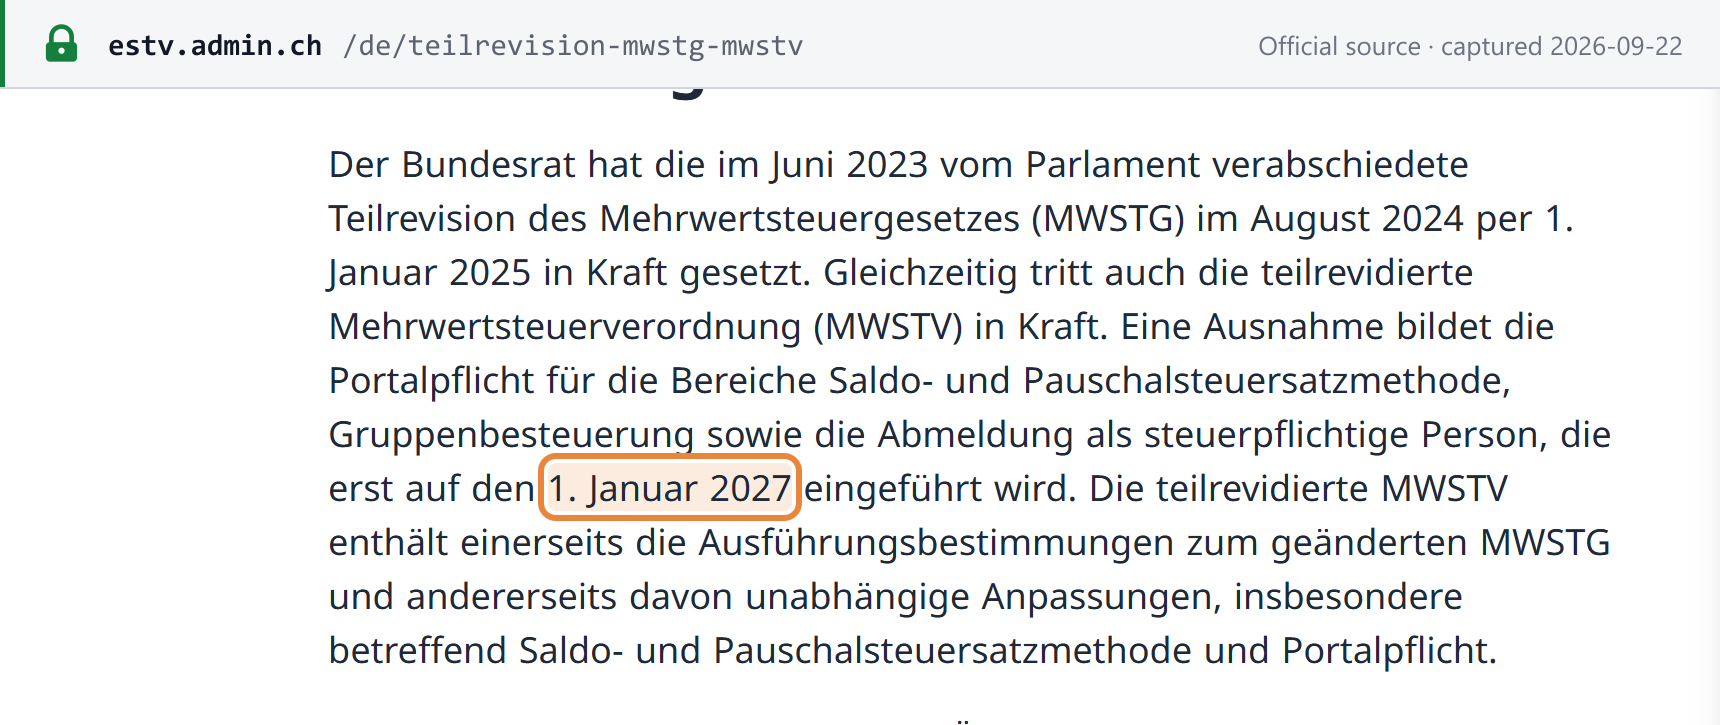 Source snapshot of the official page. Open full size ↗