Taiwan places sales of virtual assets and stablecoins outside business tax
- Jurisdiction
- Taiwan
- Tax
- Business Tax (VAT)
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 3 September 2026
- Effective
- 3 September 2026
- Authority
- Ministry of Finance, R.O.C. (mof.gov.tw)
- Systems
- Tax engine, Invoicing
- Verified
- Fetched from official source · high confidence
Business entities in Taiwan selling virtual assets or stablecoins as defined in subparagraphs 1 and 6 of Article 3 of the Virtual Asset Services Act — virtual asset service providers, exchanges and any business whose supplies include those assets. The order addresses the sale of the assets. It does not mention service fees, commissions or other consideration charged alongside such sales.
Business entities selling virtual assets or stablecoins as defined in subparagraphs 1 and 6 of Article 3 of the Virtual Asset Services Act should not charge business tax on those sales. The Order states the scope position and carries no separate commencement date.
Tax engineInvoicing
Ministry of Finance Order Tai-Tsai-Shui-Tzu No. 11504611390, dated 3 September 2026 and published in the Executive Yuan Gazette Vol. 032 No. 164, states that sales by business entities of virtual assets and stablecoins as defined in subparagraphs 1 and 6 of Article 3 of the Virtual Asset Services Act do not fall within the scope of business tax. The Order carries no separate commencement provision.
What changed in detail
Ministry of Finance Order Tai-Tsai-Shui-Tzu No. 11504611390, dated 3 September 2026 (ROC year 115) and published in the Executive Yuan Gazette Vol. 032 No. 164, states that sales by business entities of virtual assets and stablecoins as defined in subparagraphs 1 and 6 of Article 3 of the Virtual Asset Services Act are not within the scope of business tax.
The operative text is a single sentence. The order carries no separate commencement provision.
Two features of the drafting bound what the order covers:
- The scope exclusion is anchored to statutory definitions — subparagraphs 1 and 6 of Article 3 of the Virtual Asset Services Act — not to a general description of crypto-assets. What is excluded is what that Act defines.
- The order addresses the sale of the assets. Fees, commissions and other consideration charged by a service provider alongside such sales are not mentioned in it.
What it means
“Outside the scope” is a stronger and more useful position than “exempt”, and the difference is not cosmetic. An exempt supply sits inside the tax system and generally restricts input tax recovery; a supply outside the scope is not a taxable transaction at all. Businesses modelling this as a zero rate or an exemption code in a tax engine will get the return presentation wrong even where the tax collected is nil.
The practical significance is that Taiwan has resolved a question many jurisdictions still leave to inference. Where a consumption-tax statute predates crypto-assets, the usual answer is assembled from analogy — are these goods, services, or something money-like? — and different advisers reach different answers. A one-sentence ministerial order tied to statutory definitions removes that argument for the assets the Virtual Asset Services Act covers.
The live question the order does not answer is the service layer. Exchanges and virtual asset service providers typically earn commission, spread and custody or listing fees. Those are consideration for services, and the order’s language reaches the sale of the assets rather than the charge for arranging it. Businesses should not read this as a blanket exclusion for the whole activity.
The absence of a commencement date is also worth noting: this is framed as a statement of the existing scope position rather than a change taking effect on a date, which is how a scope clarification usually reads and is why it carries no transitional provision.
Proof
財政部 令 中華民國115年9月3日 台財稅字第11504611390號 營業人銷售虛擬資產服務法第3條第1款及第6款所定虛擬資產及穩定幣,非屬營業稅課稅範圍。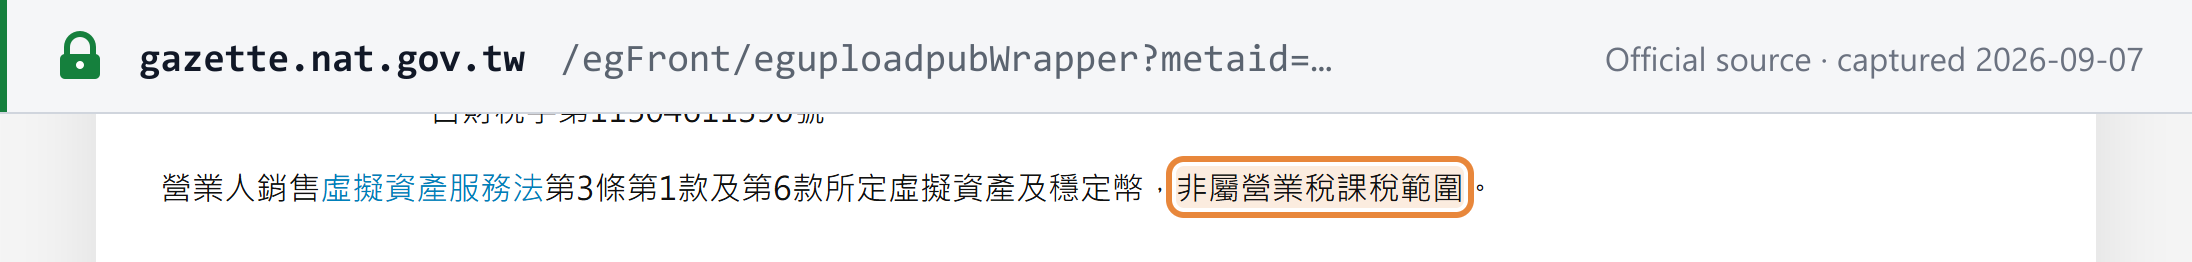 Source snapshot of the official page. Open full size ↗