Tajikistan's VAT rate falls to 13% on 1 January 2027 under the Tax Code's transitional provisions
- Jurisdiction
- Tajikistan
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Effective
- 1 January 2027
- Authority
- Tax Committee under the Government of the Republic of Tajikistan
- Systems
- Tax engine, ERP, Invoicing
- Verified
- Fetched from official source · high confidence
Every business making taxable operations or taxable imports in Tajikistan at the standard VAT rate.
Update tax engines and pricing to apply the 13% VAT rate for Tajikistan-taxable transactions and imports from 1 January 2027.
Tax engineERPInvoicing
Tajikistan's Tax Code (Article 397(4), transitional provisions) sets the value-added tax rate under Article 264(1)(1) at 14 percent for the period from 1 January 2024 to 31 December 2026, stepping down to 13 percent from 1 January 2027. The Article 264(1)(1) statutory standard rate itself is 15 percent, but the transitional provision overrides it through this schedule.
What changed in detail
The standard VAT rate in Article 264(1)(1) of the Tax Code of the Republic of Tajikistan is 15 percent. It is not the rate that applies. Article 397(4), in the Code’s transitional provisions, establishes the rate for taxable operations and taxable importation at 14 percent from 1 January 2024 to 31 December 2026, and at 13 percent from 1 January 2027.
The step-down is therefore already on the statute book rather than proposed: it sits in the Code as consolidated to Law No. 2168 of 14 May 2025, and the Tax Committee repeats the schedule in the note at the head of the published text. No further instrument is needed to bring the 13 percent rate into effect on 1 January 2027.
Article 264(1) also carries a reduced rate — 7 percent for construction works, hotel services and catering services, and 5 percent for the sale of domestically produced agricultural products, the processing of agricultural products other than raw cotton, training services and sanatorium and resort medical services without the right to offset VAT — and a zero rate. The transitional provision reaches only the standard rate in subparagraph 1.
The text cited here is the Tax Committee’s own English rendering of the Code, which it marks an unofficial translation.
What it means
Nothing has to be legislated for this to happen, which is exactly why it gets missed. The rate lives in a transitional article at the back of the Code rather than in the rate article, so a system configured from Article 264 alone is carrying 15 percent and has been wrong since 2024.
The thing to diarise is the boundary, not the arithmetic. Supplies made in December 2026 stay at 14 percent however they are invoiced or paid, and credit notes against them keep that rate. Continuous supplies and prepayments spanning the year end are where the two rates meet, so the tax point rule matters more than the new number.
Where a price list quotes VAT-inclusive amounts, the one percentage point is a margin decision due before January rather than after it.
Proof
Rates of value added tax established by paragraph 1) of part 1 of Article 264 of this Code for taxable operations and taxable importation shall be established from January 1, 2024 to December 31, 2026 - 14 percent and from January 1, 2027 - 13 percent.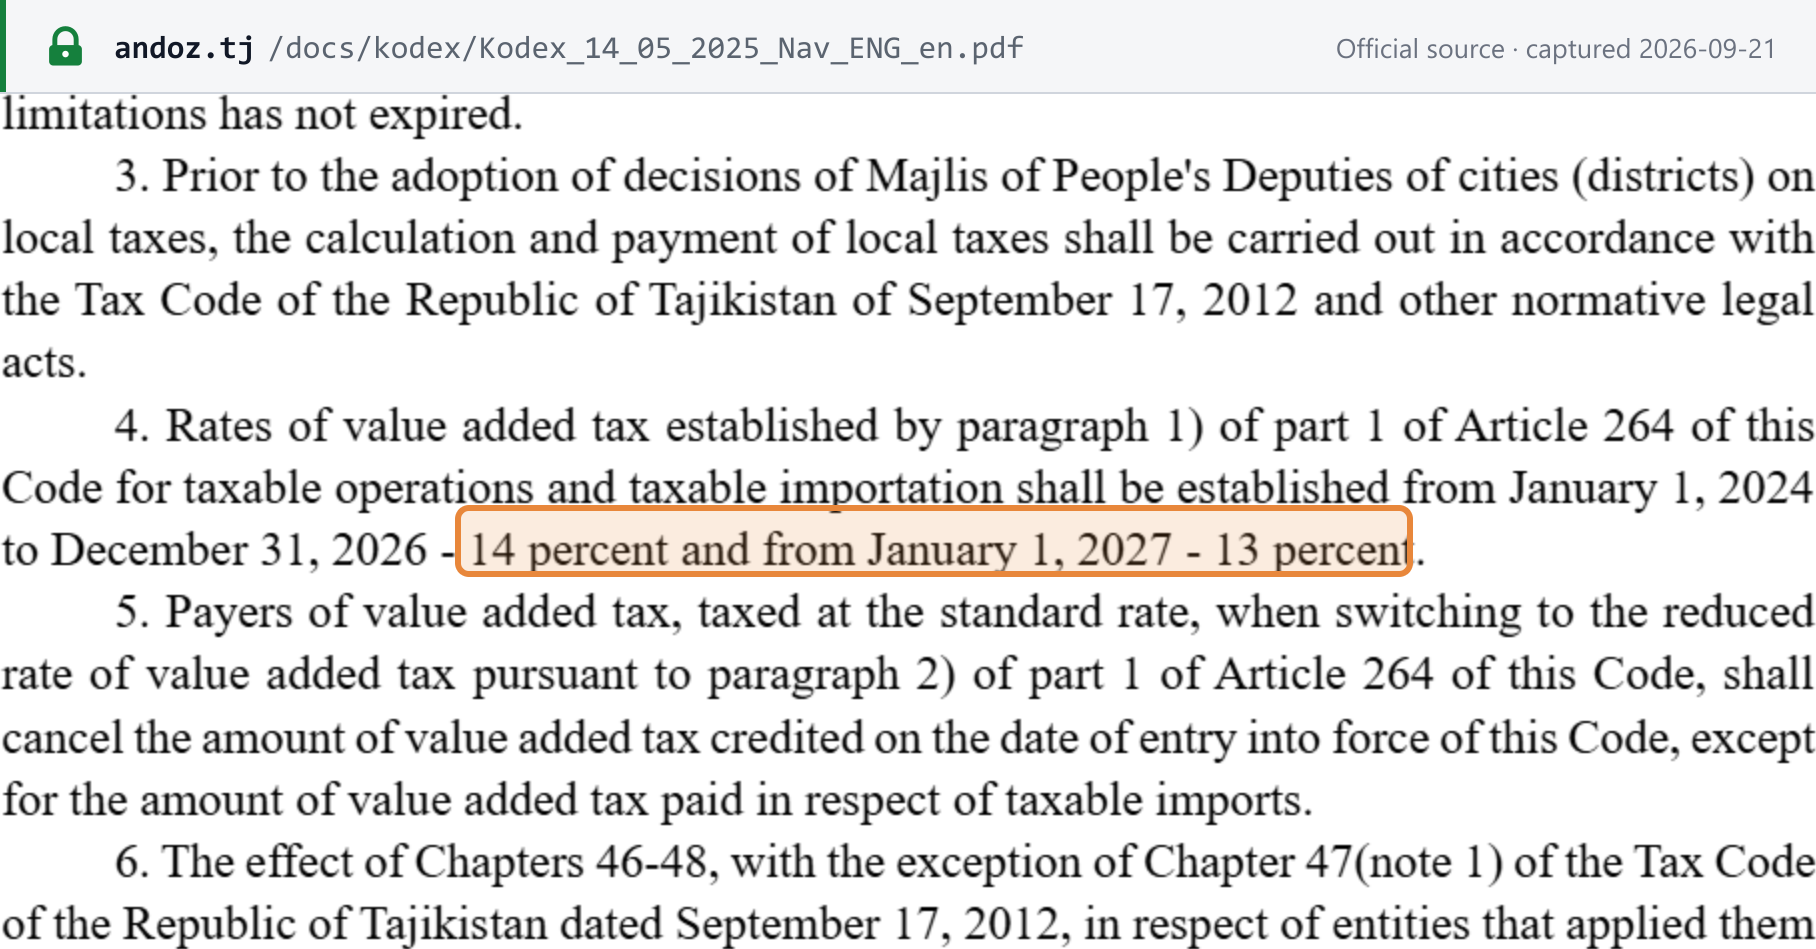 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Tax Code of the Republic of Tajikistan, Tax Committee English text as of 14 May 2025 (Law No. 2168) — Article 397(4) on page 231 of 233 · andoz.tj