Tanzania's Excise (Non-Resident Service Provider) Regulations 2026 took effect 1 July 2026
This page records one dated change. For the rules in Tanzania as they stand today, see the Tanzania guide →
- Jurisdiction
- Tanzania
- Tax
- Excise
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 30 June 2026
- Effective
- 1 July 2026
- Authority
- Tanzania Revenue Authority (TRA)
- Systems
- Tax engine, Reporting, E-commerce
- Verified
- Fetched from official source · high confidence
Non-resident providers of electronic communication, pay-to-view TV and streaming, betting, gaming and lottery advertising, and money transfer and payment services to unregistered persons in Tanzania.
Register non-resident Tanzania-facing electronic services entities for excise (90-day window from 1 July 2026 has run) and file monthly returns by the 7th.
Tax engineReportingE-commerce
Government Notice No. 158E, the Excise (Non-Resident Service Provider) Regulations, 2026 (published 30 June 2026, made under the Excise (Management and Tariff) Act Cap. 147), came into operation on 1 July 2026. Non-resident providers of electronic communication, pay-to-view TV/streaming, betting/gaming/lottery advertising and money transfer/payment services delivered over the internet to unregistered persons in Tanzania must register online with the Commissioner General (providers already operating had 90 days from commencement), file monthly returns and pay duty by the 7th of the following month in TZS or convertible currency, and are exempt from using electronic fiscal devices.
What changed in detail
Government Notice No. 158E, the Excise (Non-Resident Service Provider) Regulations, 2026, was published on 30 June 2026 under the Excise (Management and Tariff) Act Cap. 147 and came into operation on 1 July 2026.
It covers non-resident providers of electronic communication, pay-to-view TV and streaming, betting, gaming and lottery advertising, and money transfer and payment services, where the service is delivered over the internet to unregistered persons in Tanzania.
Such providers must register online with the Commissioner General. Providers already operating when the regulations began had 90 days from commencement to register. They must file monthly returns and pay the duty by the seventh day of the following month, in TZS or convertible currency. They are exempt from using electronic fiscal devices.
What it means
This is an excise regime, not VAT, and it reaches the foreign supplier directly rather than the local customer. A provider already serving Tanzanian users on 1 July 2026 had a 90-day registration window that closes around 29 September 2026, so existing providers may already be late.
The seventh-of-the-month deadline is tight relative to many VAT regimes, and the electronic fiscal device exemption does not remove the monthly return duty.
Proof
A registered service provider shall, on or before the seventh day of the month following the month to which the return relates, file return electronically and pay the duty payable in respect of services rendered in the duty period.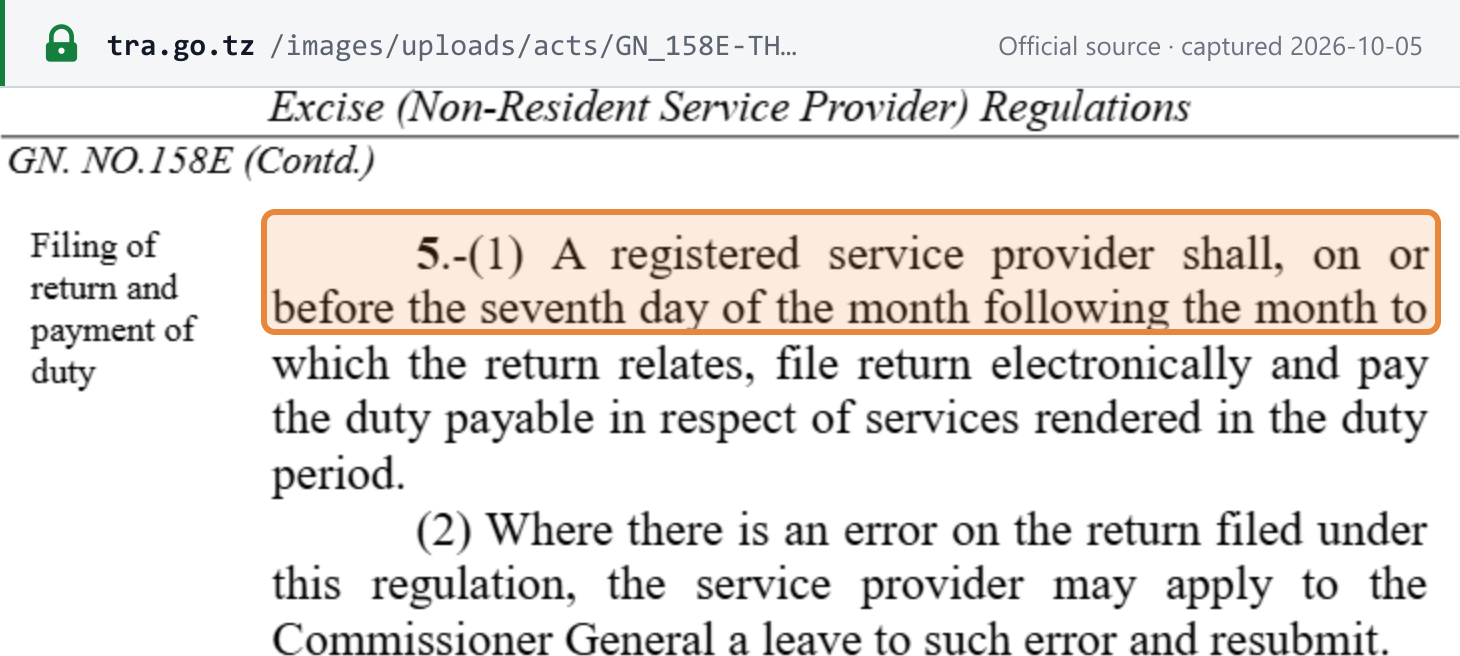 Source snapshot of the official page. Open full size ↗