Togo bars individual importers and exporters from the TPU simplified regime
- Jurisdiction
- Togo
- Tax
- VAT / TPU
- Change type
- Registration
- Status
- In force
- Impact
- Action required
- Announced
- 4 September 2026
- Effective
- 4 September 2026
- Authority
- Office Togolais des Recettes (OTR)
- Systems
- Customs, Tax engine
- Verified
- Fetched from official source · high confidence
Natural persons in Togo who carry out, or intend to carry out, import or export operations while taxed under the Taxe Professionnelle Unique.
Any individual (natural person) conducting import or export operations in Togo who is currently under the TPU/synthetic regime must contact OTR tax services to transition to the régime réel (and register for standard VAT obligations) to avoid restrictions at the customs cordon.
CustomsTax engine
The Office Togolais des Recettes (OTR), in Avis aux Opérateurs Économiques N° 008/2026/OTR/CG/CI/CDDI dated 4 September 2026 (signed 2 September 2026 by Commissaire Général Yawa Djigbodi Tsegan), states that under Article 129-2 of the Code Général des Impôts, natural persons carrying out import and/or export operations are not eligible for the simplified turnover-tax regime (régime synthétique d'imposition / Taxe Professionnelle Unique - TPU), regardless of turnover, and must instead be subject to the standard 'régime du bénéfice réel' (which carries normal VAT-registration obligations). Import/export operations may no longer be carried out by taxpayers under the synthetic regime; affected operators are told to regularize their status with the tax services.
What changed in detail
The Office Togolais des Recettes published Avis aux Opérateurs Économiques N° 008/2026/OTR/CG/CI/CDDI on 4 September 2026, signed at Lomé on 2 September 2026 by the Commissaire Général, Yawa Djigbodi Tsegan.
The notice states that under article 129-2 of the Code général des impôts, natural persons carrying out import and/or export operations are not eligible for the régime synthétique d’imposition — the Taxe Professionnelle Unique. Any natural person who carries out, or intends to carry out, such operations must therefore be placed under the régime du bénéfice réel d’imposition, irrespective of the amount of their turnover.
Two consequences follow in the notice itself. Operators currently under the synthetic regime who wish to carry on international trade are told to approach the competent tax offices to complete the formalities for admission to the régime réel. And import or export operations may no longer be carried out by taxpayers under the synthetic regime; those concerned are invited to regularise their tax position as soon as possible in order to avoid any restriction on their operations at the customs cordon.
The notice applies an existing provision of the CGI rather than enacting a new rule. What is new is OTR stating that it will be given effect at the border.
What it means
The enforcement point is the one to plan around. Article 129-2 is not new, but a rule that was previously a classification question has been attached to a gate: the consequence of staying on the TPU is not a reassessment letter months later, it is a consignment that does not move. That shifts the urgency from “before the next return” to “before the next shipment”.
It also moves the taxpayer into a different compliance world. The régime du bénéfice réel carries real-accounting and VAT obligations that the TPU’s single flat tax was designed to replace, so a sole trader importing modest volumes is not making a small administrative change — they are taking on bookkeeping, VAT returns and invoicing duties for the first time.
Proof
les personnes physiques effectuant des opérations d'importation et/ou d'exportation ne sont pas éligibles au régime synthétique d'imposition (Taxe Professionnelle Unique - TPU). En conséquence, toute personne physique qui réalise ou envisage de réaliser des opérations d'importation et/ou d'exportation doit être soumise au régime du bénéfice réel d'imposition, indépendamment du montant de son chiffre d'affaires.natural persons carrying out import and/or export operations are not eligible for the simplified tax regime (Taxe Professionnelle Unique - TPU). Consequently, any natural person who carries out or intends to carry out import and/or export operations must be placed under the actual-profit tax regime, irrespective of the amount of their turnover.
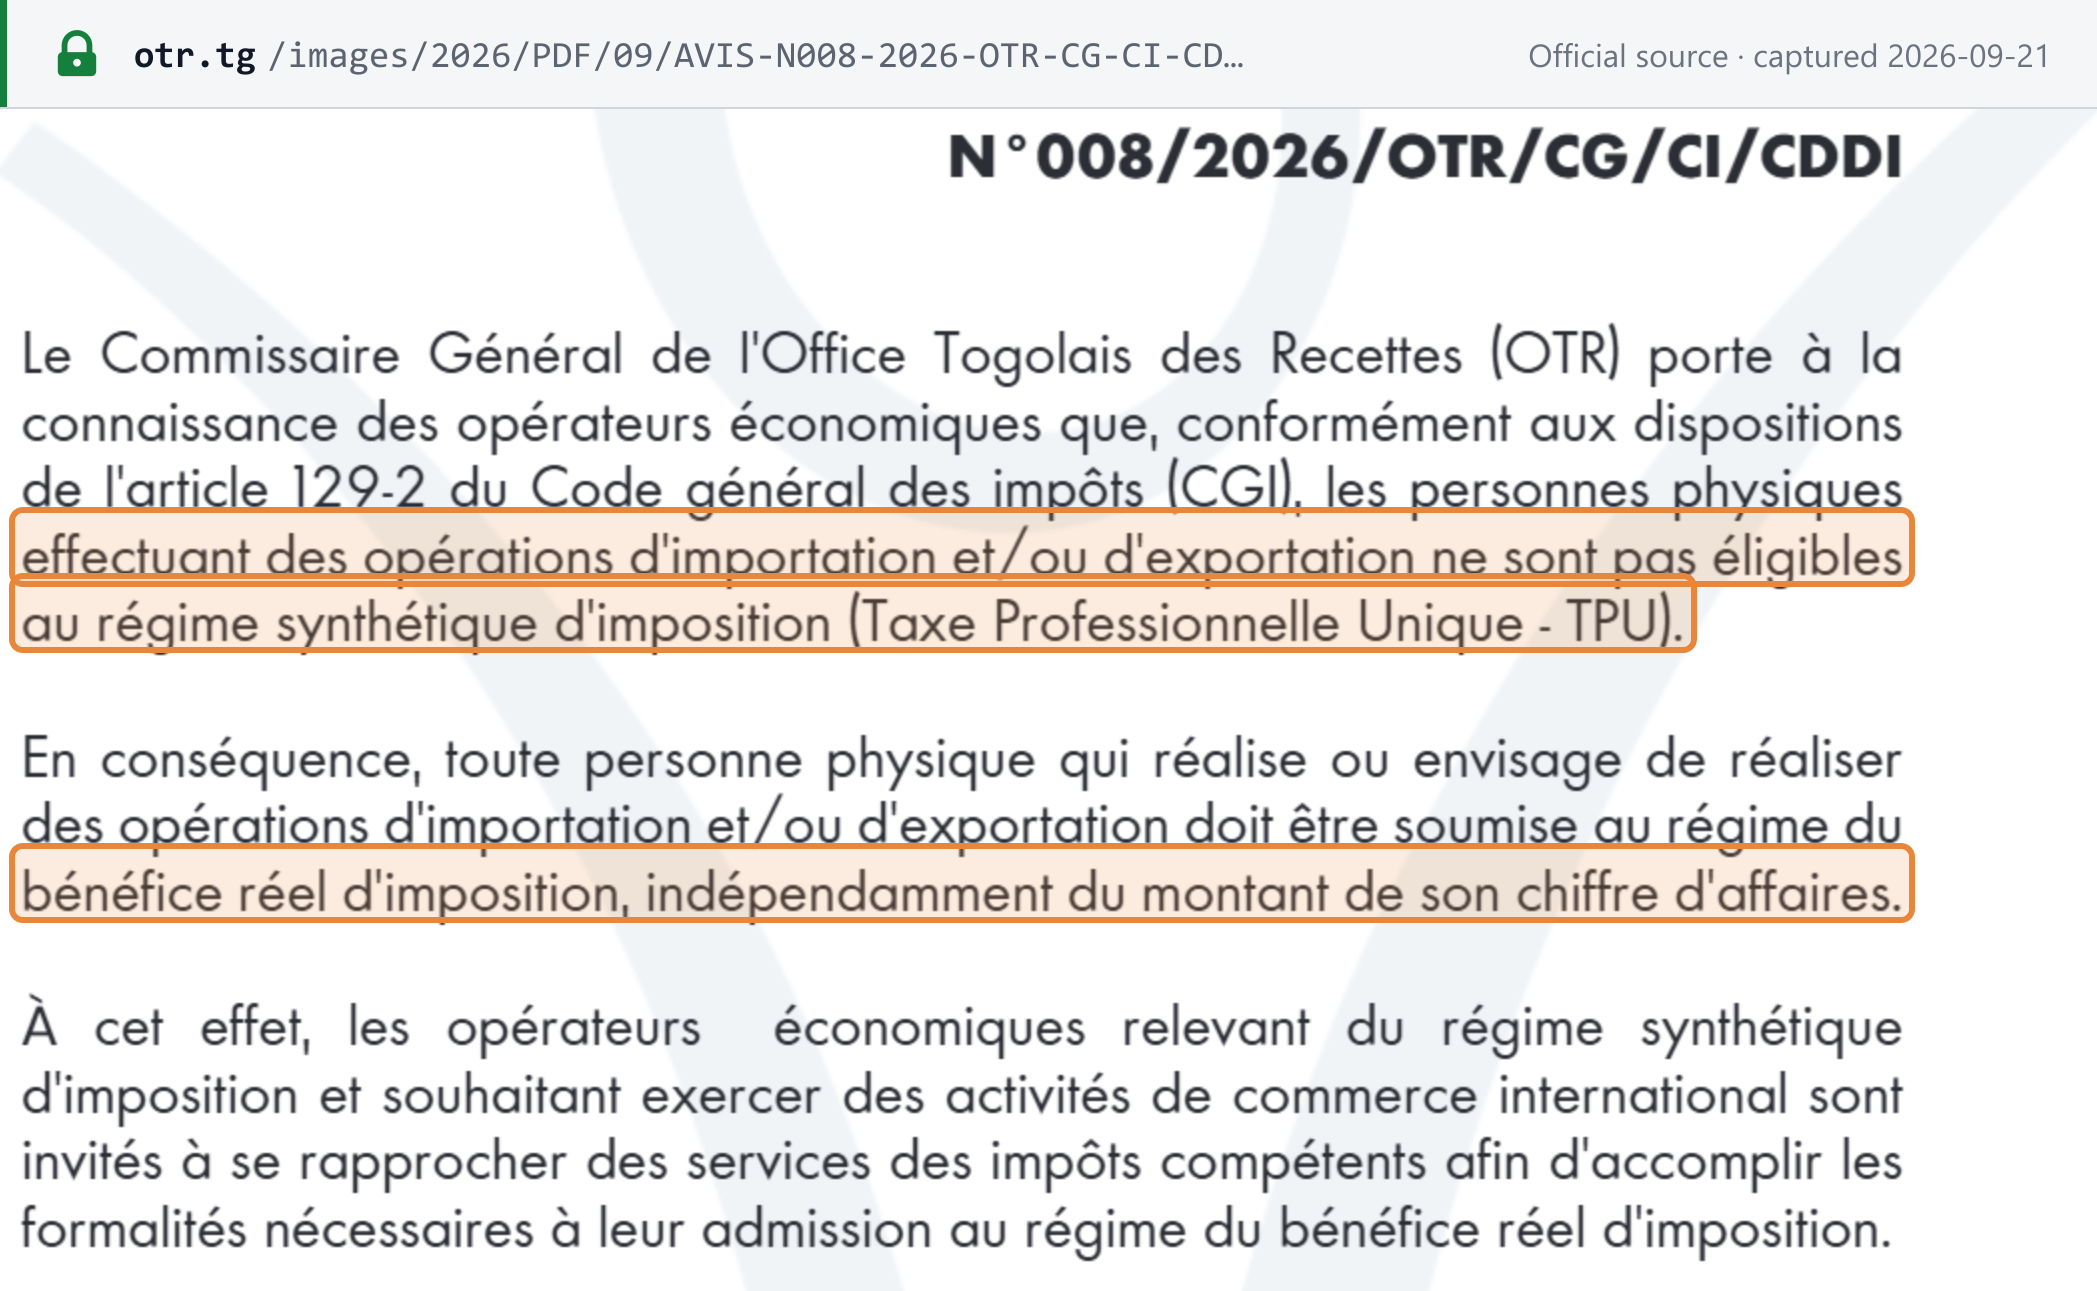 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Avis aux Opérateurs Économiques N° 008/2026/OTR/CG/CI/CDDI, signed at Lomé on 2 September 2026 by the Commissaire Général — the signed PDF the cited OTR page links as 'Veuillez télécharger l'avis complet ici' · www.otr.tg