Türkiye extends monthly tax reporting to hosting and social network providers
- Jurisdiction
- Türkiye
- Tax
- Tax Procedure Law (VUK) — platform reporting
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 5 September 2026
- Effective
- 5 September 2026
- Authority
- Resmî Gazete, T.C. Cumhurbaşkanlığı
- Systems
- Reporting, E-commerce
- Verified
- Fetched from official source · high confidence
Hosting providers (yer sağlayıcılar) and social network providers that carry listings enabling the purchase, sale or rental of movables, immovables, goods or services — classified-ad sites, marketplace and rental platforms, and social networks whose users post such listings. Access providers and content providers also join the class of persons who may be placed under a reporting duty. Communiqué 538 already reached e-commerce service providers and intermediary service providers; Communiqué 595 adds access providers, content providers, hosting providers and social network providers to that class.
Hosting providers (yer sağlayıcılar) and social network providers that publish listings enabling the purchase, sale or rental of movables, immovables, goods or services must report monthly to the Revenue Administration: the internet address(es) where the service is provided, the name/title and TCKN/YKN/VKN of the persons served, and the listing details of the transactions carried out on their behalf. The reporting duty previously reached only e-commerce service providers and intermediary service providers.
ReportingE-commerce
Tax Procedure Law General Communiqué Serial No. 595, published in Resmî Gazete No. 33361 on 5 September 2026, amends General Communiqué Serial No. 538 (Resmî Gazete No. 31852, 31 May 2022). It widens the class of persons who may be placed under a continuous information-reporting duty from e-commerce service providers and intermediary service providers to also include access providers, content providers, hosting providers and social network providers, and extends the covered transactions from purchase and sale to purchase, sale, rental, listings and advertising in any digital medium including the internet. A new paragraph requires hosting providers and social network providers publishing such listings to report the specified data to the Revenue Administration for each one-month period of the calendar year. The Communiqué entered into force on its publication date.
What changed in detail
Tax Procedure Law General Communiqué Serial No. 595, published in Resmî Gazete No. 33361 on 5 September 2026, amends General Communiqué Serial No. 538 (Resmî Gazete No. 31852, 31 May 2022). It entered into force on its publication date.
The amendment does two separate things.
It widens who can be placed under a reporting duty. Communiqué 538 reached e-commerce service providers and intermediary service providers. Communiqué 595 adds access providers, content providers, hosting providers (yer sağlayıcılar) and social network providers to that class.
It widens what must be reported. The covered transactions move from purchase and sale to purchase, sale, rental, listings and advertising in any digital medium, including the internet.
A new paragraph then imposes the concrete obligation. Hosting providers and social network providers that publish listings enabling the purchase, sale or rental of movables, immovables, goods and services must report to the Revenue Administration, for each one-month period of the calendar year:
- the internet address or addresses at which the service was provided;
- the name/title and TCKN/YKN/VKN of the natural or legal persons served — that is, the data that establishes their tax status;
- the listing details of the sale or rental transactions carried out on their behalf.
Reporting is electronic, by the method set out in Article 5 of Communiqué 538.
What it means
The shift here is from intermediary to carrier. Communiqué 538’s reporting duty followed the transaction: if a platform stood between buyer and seller, it reported. Communiqué 595 follows the listing instead. A site that merely publishes an advertisement — and never sees the payment, the contract or the delivery — is now inside the perimeter, and is being asked for the tax identity of the person who placed the listing.
That is a materially harder ask than it first appears. A platform that intermediates a sale has already collected identity data because it had to settle money. A platform that only hosts a classified ad frequently has not: it may hold an email address and a phone number and nothing that maps to a TCKN, YKN or VKN. The obligation therefore implies a collection step at listing time, not just a reporting step at month end, and retrofitting that into an existing product is the real work.
The inclusion of rentals is the second thing worth noting. Rental listings have historically sat outside sales-transaction reporting because no sale occurs; Communiqué 595 names them explicitly.
Finally, note what this is not. This is a Tax Procedure Law information-reporting obligation, not a VAT charging rule: it does not make the platform liable for tax on the underlying transaction, and it does not create a deemed-supplier regime. It builds the data set from which such liability could later be assessed against the lister.
Proof
(2) Taşınır ve taşınmazlar ile mal ve hizmetlerin alınması, satılması veya kiralanmasının temin edilmesine yönelik olarak verilen ilanların yayımlanmasına imkân sağlayan yer sağlayıcılar ile sosyal ağ sağlayıcılar takvim yılının birer aylık süreleri içerisinde gerçekleştirmiş oldukları söz konusu işlemlere ilişkin olarak; a) Verilen hizmetin sağlandığı internet adres veya adreslerini, b) Hizmet verilen gerçek ya da tüzel kişilere ait ad soyad/unvan, TCKN/YKN/VKN gibi mükellefiyet tespitine ilişkin bilgileri, c) Hizmet verilenler adına gerçekleştirilen taşınır, taşınmaz, mal ve hizmet satış/kiralama işlemlerine ilişkin ilan bilgilerini, elektronik ortamda 5 inci maddede açıklanan yöntemle Başkanlık sistemlerine bildirmek zorundadır.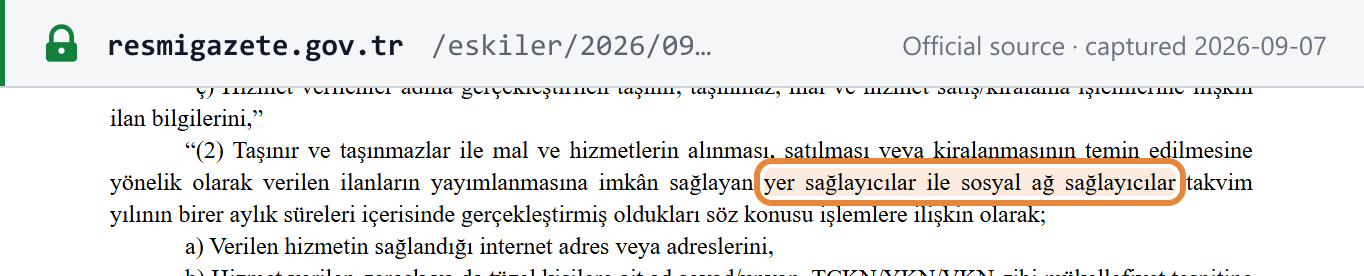 Source snapshot of the official page. Open full size ↗