Uganda publishes an EFRIS e-invoicing duty for twelve sectors, backdated to July 2025
- Jurisdiction
- Uganda
- Tax
- VAT / EFRIS
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 10 August 2026
- Effective
- 1 July 2025
- Authority
- Uganda Revenue Authority (URA)
- Systems
- Invoicing, POS, Tax engine
- Verified
- Fetched from official source · high confidence
Businesses in twelve named sectors, whether or not VAT-registered: manufacturing; mining and quarrying; water supply, sewerage, waste management and remediation; electricity, gas, steam and air conditioning supply; construction; transportation and storage; accommodation and food service; information technology and communication; real estate; professional, scientific and technical activities; arts, entertainment and recreation; and wholesale and retail of fuel. Businesses in those sectors turning over less than UGX 10,000,000 a year, and taxpayers with rental income below UGX 2,820,000 a year, may use EFRIS voluntarily but are not required to. Providers of passenger land transport — taxis, boda-bodas, shuttles and buses — and non-resident digital service providers liable to digital service tax are excluded from this phase.
Businesses in the twelve listed sectors must issue electronic invoices and receipts through EFRIS, in addition to the existing obligation on all VAT-registered taxpayers. Businesses in those sectors with turnover below UGX 10,000,000 a year, and taxpayers with rental income below UGX 2,820,000 a year, are not required to issue through EFRIS but may do so voluntarily. Providers of passenger land transport and non-resident digital service providers liable to digital service tax are excluded from this phase.
InvoicingPOSTax engine
A Uganda Revenue Authority public notice, "Additional taxpayers required to use EFRIS", first published on 10 August 2026, states that businesses in twelve listed sectors are required to use the Electronic Fiscal Receipting and Invoicing Solution to issue electronic invoices and receipts, in addition to the existing mandatory EFRIS obligation for all VAT-registered taxpayers. The notice recites an effective date of 1 July 2025 — it publishes in August 2026 an obligation it states has applied for thirteen months. The twelve sectors are manufacturing; mining and quarrying; water supply, sewerage, waste management and remediation; electricity, gas, steam and air conditioning supply; construction; transportation and storage; accommodation and food service; information technology and communication; real estate; professional, scientific and technical activities; arts, entertainment and recreation; and wholesale and retail of fuel. The notice cites no legal instrument.
What changed in detail
A Uganda Revenue Authority public notice, “Additional taxpayers required to use EFRIS”, was first published on 10 August 2026. It states that businesses in twelve listed sectors must use the Electronic Fiscal Receipting and Invoicing Solution (EFRIS) to issue electronic invoices and receipts, in addition to the existing obligation on all VAT-registered taxpayers.
The effective date the notice recites is 1 July 2025. The notice publishes in August 2026 an obligation it states has already applied for thirteen months.
The twelve sectors are manufacturing; mining and quarrying; water supply, sewerage, waste management and remediation; electricity, gas, steam and air conditioning supply; construction; transportation and storage; accommodation and food service; information technology and communication; real estate; professional, scientific and technical activities; arts, entertainment and recreation; and wholesale and retail of fuel.
The notice also sets out carve-outs and two consequences:
- Turnover floor. Businesses in the listed sectors with turnover below UGX 10,000,000 a year need not issue through EFRIS, though they may do so voluntarily. The same applies to taxpayers with rental income below UGX 2,820,000 a year.
- Excluded from this phase. All providers of passenger land transport — taxis, boda-bodas, shuttles, buses — and all non-resident digital service providers liable to digital service tax.
- Income tax consequence. No income tax deduction is allowed for an expense not supported by an e-invoice or e-receipt where the supplier is required to use EFRIS (s.22(3)(m) Income Tax Act).
- Buyer identification. Every business e-invoice or e-receipt must carry the buyer’s BRN, NIN or TIN.
The notice cites no legal instrument. Aggregators report the underlying instrument as Uganda Gazette General Notice No. 2218 of 2025; that number is not asserted here because the Gazette could not be reached to confirm it.
What it means
The dating is the story, and it is a trap for anyone reading the aggregator coverage rather than the notice. Several trackers reported this in late August 2026 as a new mandate. It is not presented as one: the authority is publishing, in 2026, a duty it says began in July 2025. Whether that reflects a gazetted 2025 instrument that was never publicised, or a restatement whose retrospectivity was not intended to bite, the notice itself does not say — and the absence of any cited instrument makes the question harder rather than easier.
For a business inside the twelve sectors, the practical exposure is therefore not “start issuing through EFRIS now”. It is the thirteen months already elapsed, during which invoices may have been issued outside EFRIS. The income tax limb sharpens that: expenses unsupported by an e-invoice from a supplier required to use EFRIS are not deductible, so the risk lands on the customer’s return as well as the supplier’s compliance record.
The second thing worth noting is that this reaches beyond VAT registration. EFRIS was previously understood as an obligation attaching to VAT-registered taxpayers; the sector list is drawn by activity, so a business below the VAT threshold in, say, construction or real estate can be inside it. The UGX 10,000,000 turnover floor is what limits that, and it is low.
Anyone advising here should get the underlying instrument before relying on the 1 July 2025 date, because the notice does not supply it.
Proof
Uganda Revenue Authority (URA) wishes to inform the general public that, effective July 1st 2025, businesses operating in the sectors listed below are required to use the Electronic Fiscal Receipting and Invoicing Solution (EFRIS) to issue electronic invoices and electronic receipts. This requirement is in addition to the existing mandatory EFRIS obligation for all VAT registered taxpayers.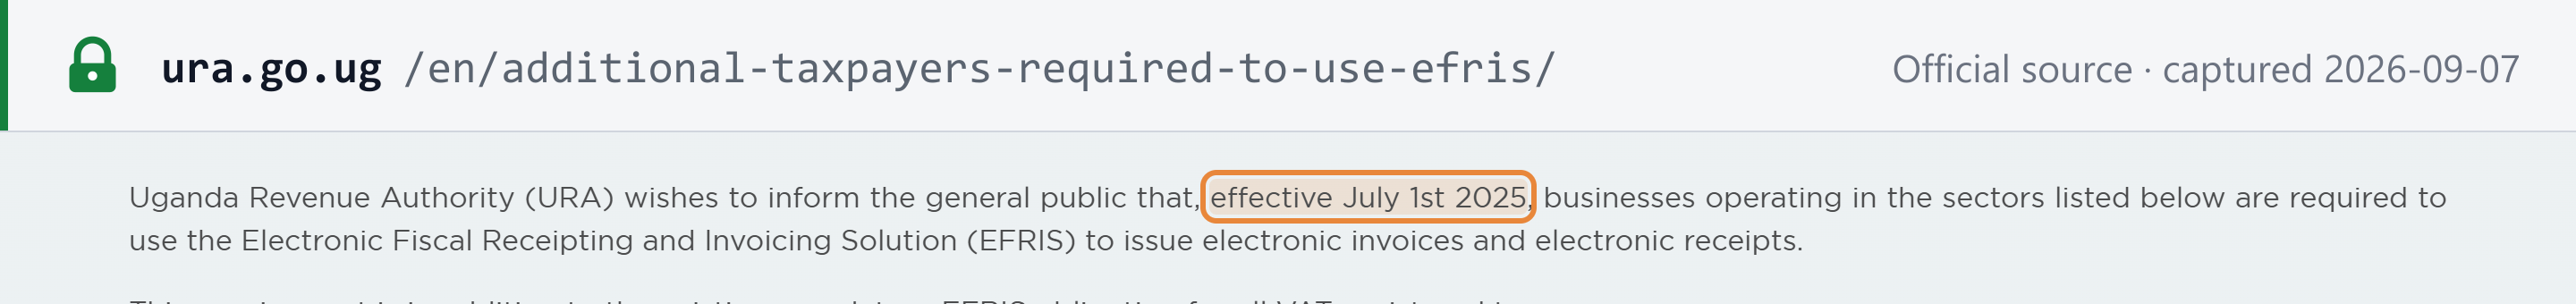 Source snapshot of the official page. Open full size ↗
First date of publication: Monday August 10, 2026 Source snapshot of the official page. Open full size ↗