Ukraine exempts from VAT imports of defence goods for taxpayers' own defence production (Law No. 4967-IX)
This page records one dated change. For the rules in Ukraine as they stand today, see the Ukraine guide →
- Jurisdiction
- Ukraine
- Tax
- VAT
- Change type
- Update
- Status
- In force
- Impact
- FYI
- Announced
- 3 September 2026
- Effective
- 17 September 2026
- Authority
- Verkhovna Rada of Ukraine
- Systems
- Customs, Tax engine
- Verified
- Fetched from official source · high confidence
Ukrainian taxpayers producing weapons, military and special equipment that import defence goods for their own production, where the end recipient is a law-enforcement body, the Ministry of Defence, the Armed Forces or another military or volunteer formation.
No action — monitoring only.
CustomsTax engine
Law of Ukraine No. 4967-IX of 3 September 2026 amends the Tax Code to exempt from VAT the import into Ukraine, under the import customs regime, of defence goods (weapons, military and special equipment including unmanned systems, electronic-warfare and reconnaissance means, ammunition) brought in by taxpayers for their own defence-production activity, where the end recipient under the end-user certificate or contract is a law-enforcement body, the Ministry of Defence, the Armed Forces or another military or volunteer formation, and the goods are received without reimbursement of their cost; it also adds quad bikes and all-terrain vehicles of heading 8703 and 8704 to the transitional-provision lists of goods for security and defence needs. The Rada record shows entry into force on 17 September 2026.
What changed in detail
Law of Ukraine No. 4967-IX of 3 September 2026 amends the Tax Code by adding a new paragraph to point 197.23 of Article 197. The Rada record shows entry into force on 17 September 2026.
The new paragraph exempts from VAT the import into Ukraine, under the import customs regime, of goods specified in part eight of Article 287 of the Customs Code, where taxpayers bring them in for their own production of weapons and military and special equipment. The goods covered (defined as defence goods) include unmanned systems, electronic-warfare and reconnaissance means, weapons and ammunition.
Three conditions apply:
- the end recipient under the end-user certificate or the contract is a law-enforcement body, the Ministry of Defence, the Armed Forces of Ukraine, or another military or volunteer formation;
- the goods are imported for the taxpayer’s own defence-production activity;
- the end recipient receives the defence goods without reimbursement of their cost.
The law also adds quad bikes and all-terrain vehicles of headings 8703 and 8704 to the transitional-provision lists of goods for security and defence needs.
What it means
This is a narrow relief for defence manufacturers rather than a general change to import VAT. It turns on paperwork: the end-user certificate or contract must name a qualifying recipient, and the goods must reach that recipient free of charge. Importers relying on it should keep that chain of documents with each customs declaration, because an import that fails any condition is taxed in the normal way.
Proof
Звільняються від оподаткування операції із ввезення на митну територію України у митному режимі імпорту товарів, визначених частиною восьмою статті 287 Митного кодексу України, що ввозяться платниками податків для використання у власній виробничій діяльності з виробництва озброєння, військової та спеціальної технікиOperations of importing into the customs territory of Ukraine under the import customs regime goods specified in part eight of Article 287 of the Customs Code of Ukraine, brought in by taxpayers for use in their own production of weapons, military and special equipment, are exempt from taxation
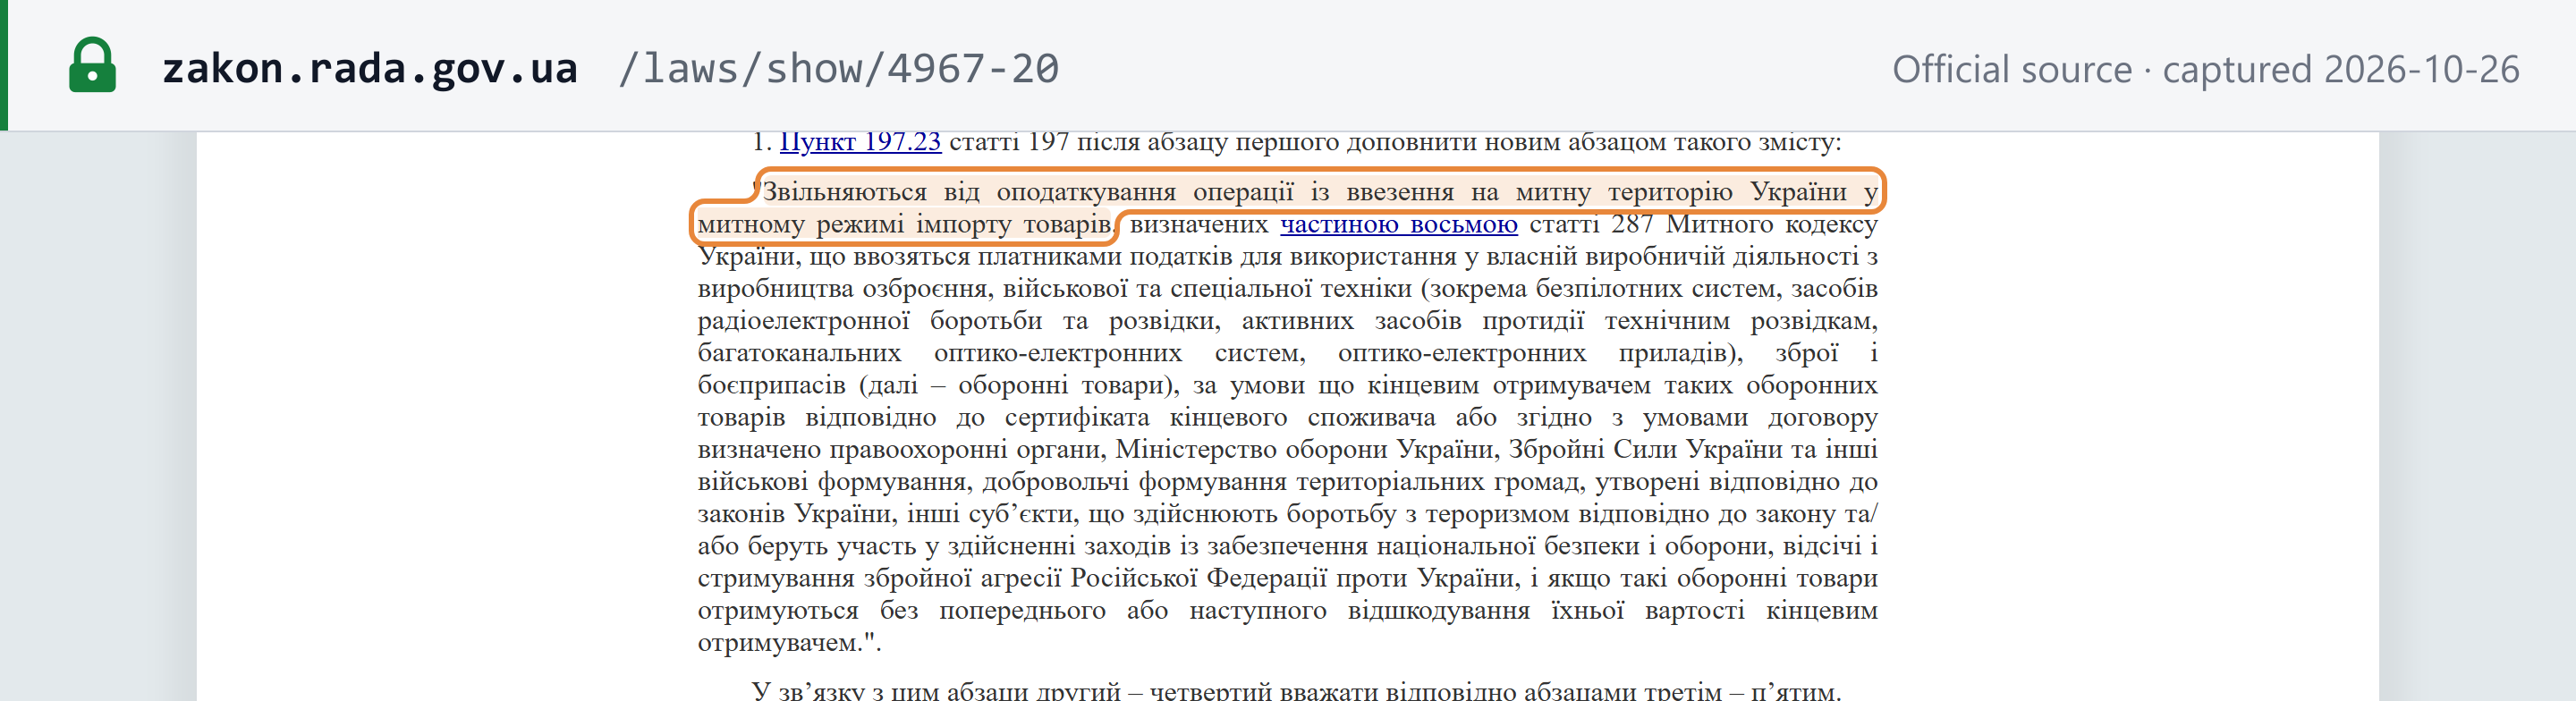 Source snapshot of the official page. Open full size ↗