Uruguay exempts beverage-container deposits from IVA and gives housing cooperatives an IVA credit from 1 January 2027 (Law 20.531)
- Jurisdiction
- Uruguay
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 16 October 2026
- Effective
- 1 January 2027
- Authority
- IMPO – Dirección Nacional de Impresiones y Publicaciones Oficiales, Uruguay
- Systems
- Tax engine, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Operators of approved beverage-container deposit-return schemes in Uruguay, and housing cooperatives building or recycling new dwellings whose projects are executed by deed after 1 January 2027.
Beverage-container deposit scheme operators and housing cooperatives: update IVA treatment for deposit/refund operations and construction-cost credits from 1 January 2027, pending regulations.
Tax engineInvoicingReporting
Uruguay's Ley N° 20.531 (Rendición de Cuentas y Balance de Ejecución Presupuestal, Ejercicio 2025), promulgated 1 October 2026 and published 16 October 2026, amends Title 10 (IVA) of the Texto Ordenado 2023: Article 297 adds Article 70 bis exempting from IVA the deposit and refund operations associated with single-use beverage containers under approved waste-management plans implementing a deposit-return system (SDDR); Article 300 adds literal F) to Article 87 giving housing cooperatives a credit for the IVA included in purchases of goods and services for the direct construction costs of the cooperative project (only goods and services incorporated directly into the civil works), applicable to cooperative projects whose deeds are executed after 1 January 2027; Article 301 empowers the Executive Power to modify the limit in literal H) of Article 36 of Title 10. Under Article 2 the law applies from 1 January 2027 unless a provision states another date.
What changed in detail
Uruguay’s Law No. 20.531, the Rendición de Cuentas y Balance de Ejecución Presupuestal for the 2025 financial year, was promulgated on 1 October 2026 and published on 16 October 2026. It amends Title 10 (IVA) of the Texto Ordenado 2023 in three places:
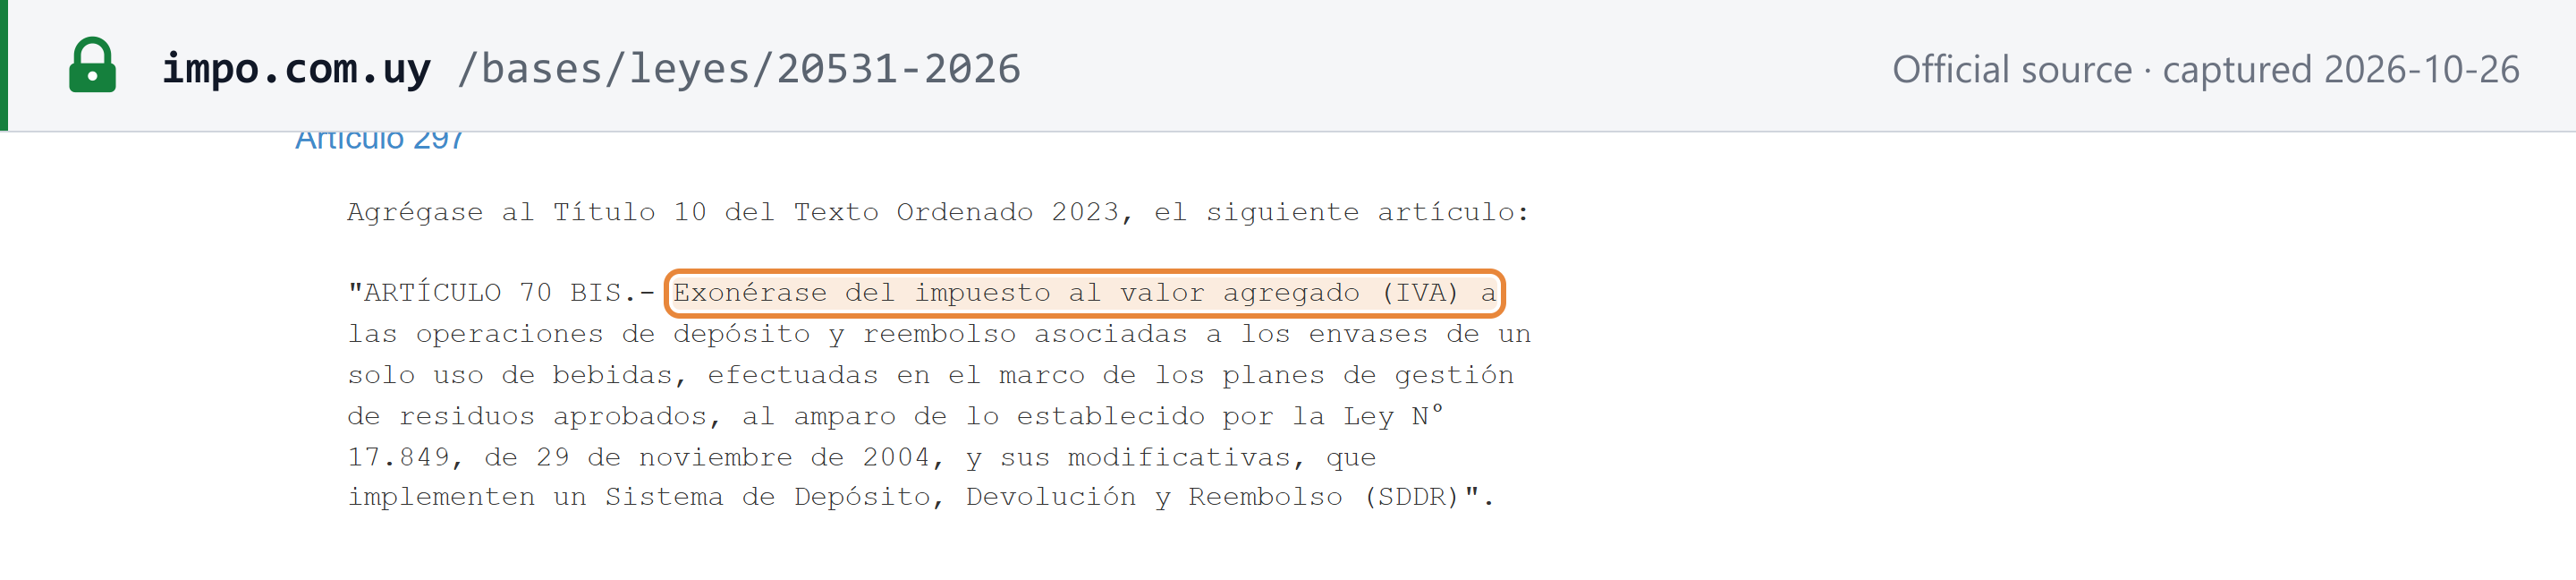
- Article 297 adds Article 70 bis, exempting from IVA the deposit and refund operations associated with single-use beverage containers carried out under approved waste-management plans that implement a deposit-return system (Sistema de Depósito, Devolución y Reembolso, SDDR).
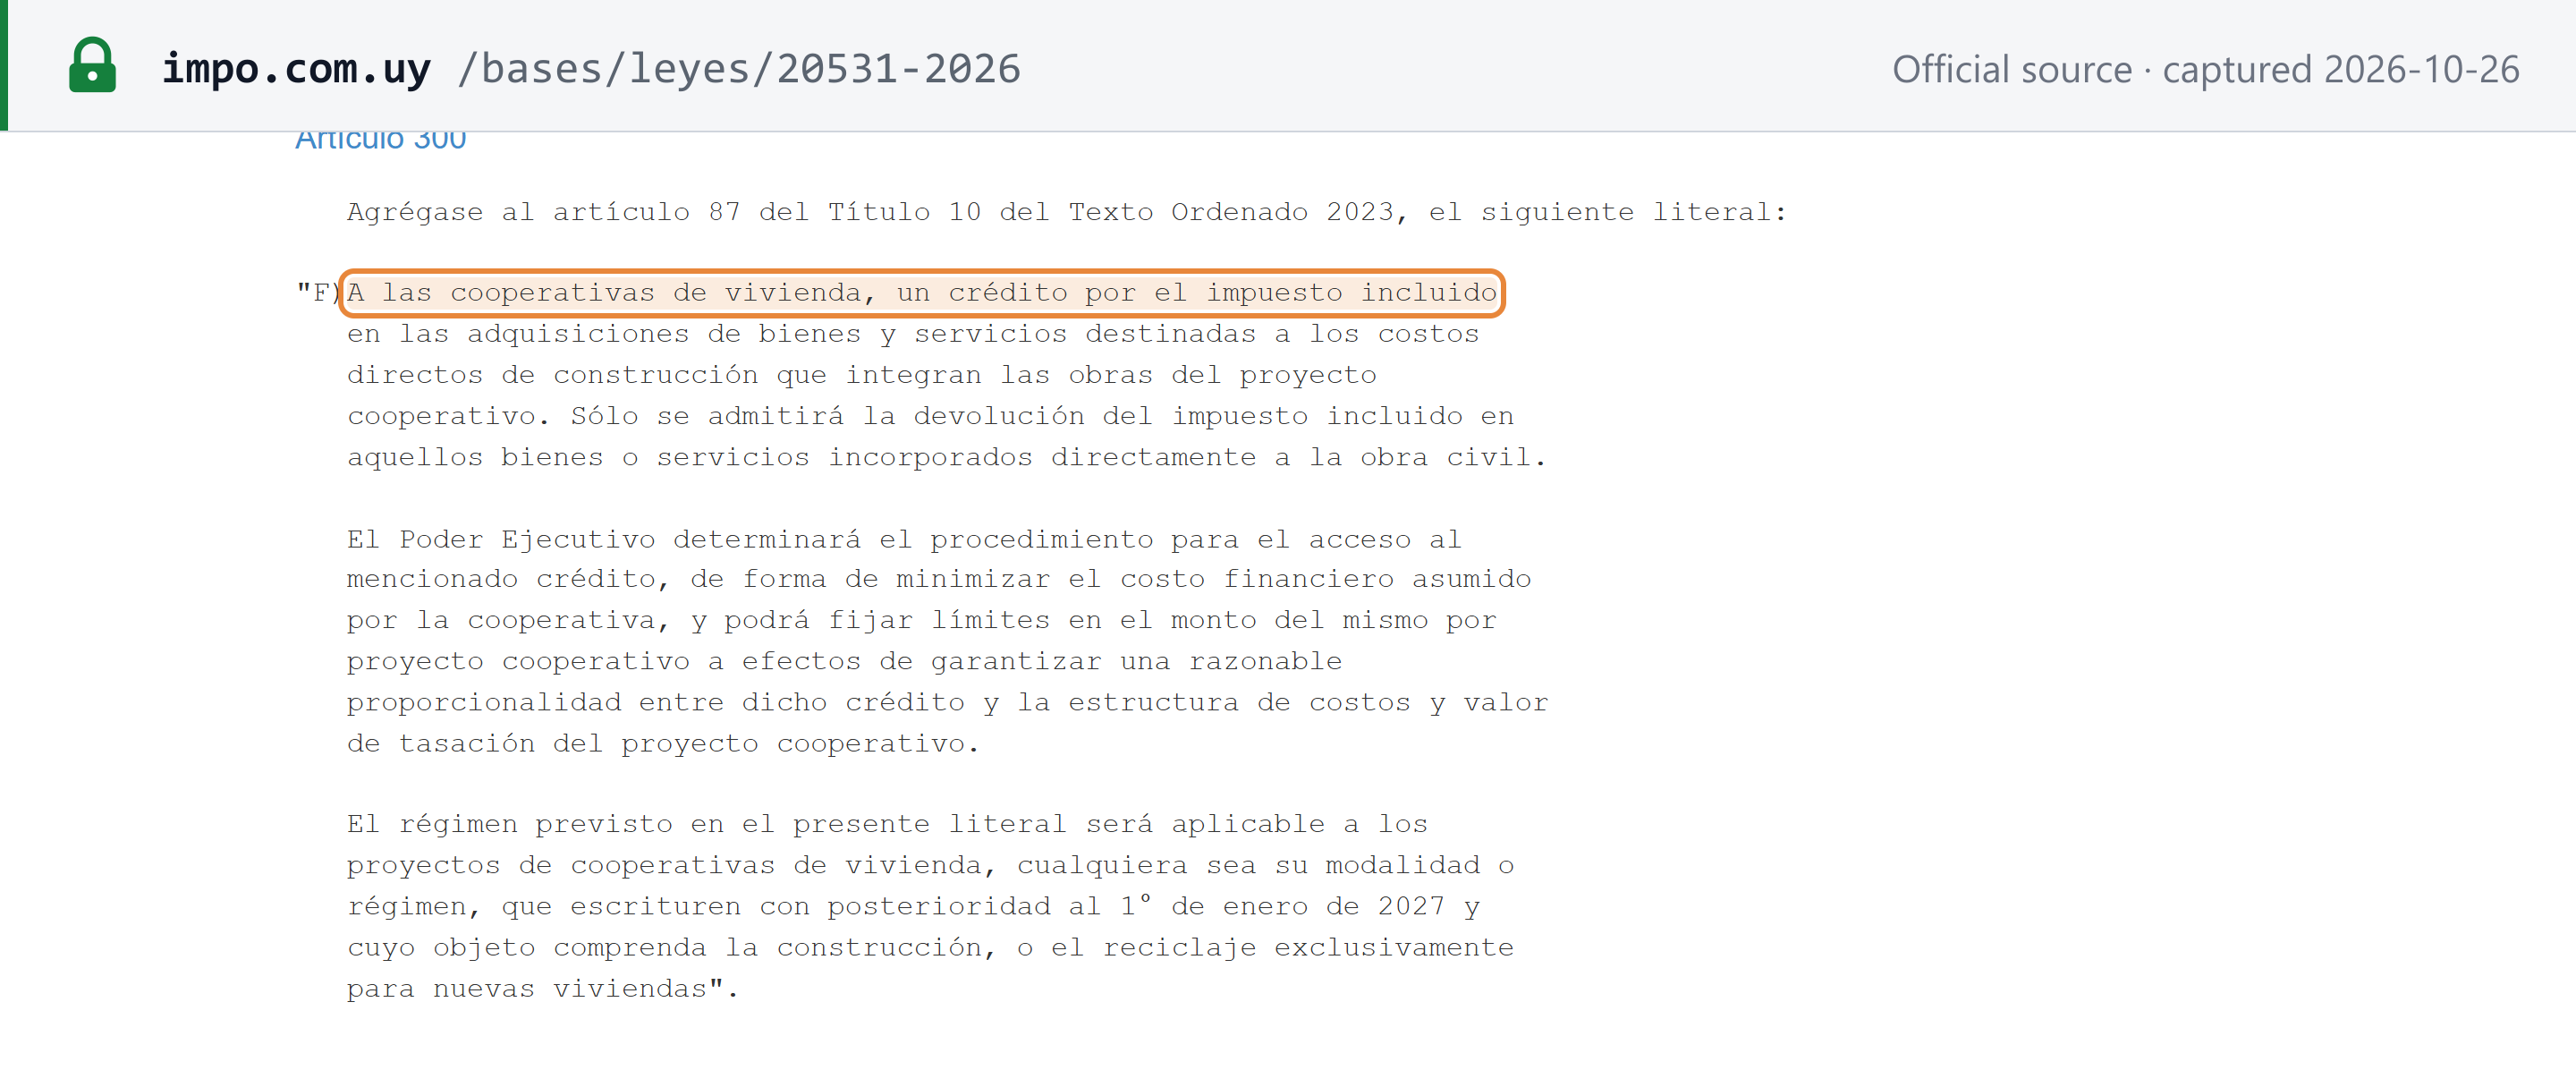
- Article 300 adds literal F) to Article 87, giving housing cooperatives a credit for the IVA included in purchases of goods and services for the direct construction costs of the cooperative project. Only IVA on goods and services incorporated directly into the civil works qualifies. The regime applies to housing cooperative projects of any type whose deeds are executed after 1 January 2027 and whose purpose is building, or recycling exclusively for new dwellings. The Executive Power sets the procedure and may cap the credit per project.
- Article 301 empowers the Executive Power to modify the limit in literal H) of Article 36 of Title 10.
Under Article 2 the law applies from 1 January 2027 unless a provision states another date.
What it means
Both measures need implementing regulations before they work in practice: the cooperative credit depends on a procedure the Executive Power has still to set, and the container exemption depends on approved deposit-return plans. Cooperatives planning projects should note that only deeds executed after 1 January 2027 qualify, and that the credit covers construction inputs built into the works, not general project costs.
Proof
A las cooperativas de vivienda, un crédito por el impuesto incluido en las adquisiciones de bienes y servicios destinadas a los costos directos de construcción que integran las obras del proyecto cooperativo.To housing cooperatives, a credit for the tax included in purchases of goods and services allocated to the direct construction costs that form part of the works of the cooperative project.
 Source snapshot of the official page. Open full size ↗
Exonérase del impuesto al valor agregado (IVA) a las operaciones de depósito y reembolso asociadas a los envases de un solo uso de bebidas, efectuadas en el marco de los planes de gestión de residuos aprobadosDeposit and refund operations associated with single-use beverage containers, carried out under approved waste-management plans, are exempted from value added tax (IVA)
 Source snapshot of the official page. Open full size ↗