Uzbekistan taxes foreign marketplaces on goods sold to individuals from December 2026
- Jurisdiction
- Uzbekistan
- Tax
- VAT
- Change type
- Digital services
- Status
- Enacted
- Impact
- Action required
- Announced
- 10 September 2026
- Effective
- 12 December 2026
- Authority
- National Database of Legislation of the Republic of Uzbekistan (lex.uz)
- Systems
- E-commerce, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Foreign legal entities selling goods to individuals in Uzbekistan through an electronic trading platform, where the place of supply is Uzbekistan.
If you operate a foreign marketplace selling goods to individuals in Uzbekistan, register with the Tax Committee within 30 days of your first in-scope transaction from 12 December 2026, and configure VAT on the gross sale price plus quarterly electronic reporting.
E-commerceTax engineReporting
Law of the Republic of Uzbekistan No. ZRU-1173 of 10 September 2026 amends Chapter 39 of the Tax Code so that foreign legal entities selling goods to individuals through electronic trading platforms are brought within the same regime as foreign suppliers of electronic services. Such foreign entities must apply to the tax authority for registration (or deregistration) no later than thirty calendar days from the day they begin (or cease) supplying electronic services or selling goods through electronic trading platforms, and must file tax reporting electronically through the taxpayer personal cabinet. Where a foreign legal entity sells goods to individuals through an electronic trading platform and the place of supply is Uzbekistan, the taxable base is the value of those goods including the tax, calculated from the actual sale prices. Article 5 provides that the Law enters into force three months after its official publication; the National Database of Legislation records the commencement date as 12 December 2026.
What changed in detail
Law of the Republic of Uzbekistan No. ZRU-1173 of 10 September 2026 amends Chapter 39 of the Tax Code so that foreign legal entities selling goods to individuals through electronic trading platforms are brought within the same VAT regime that already applies to foreign suppliers of electronic services.
In-scope foreign entities must apply for tax registration, or deregistration, within thirty calendar days of starting, or stopping, that activity, and must file tax reporting electronically through the taxpayer personal cabinet. Where the place of supply is Uzbekistan, the taxable base is the value of the goods including tax, calculated from the actual sale price. Article 5 sets commencement at three months after official publication, which the National Database of Legislation records as 12 December 2026.
What it means
The VAT base includes the tax itself rather than being calculated on a tax-exclusive price, a gross-up that changes the effective rate calculation for anyone modelling margins on Uzbekistan sales. Foreign marketplaces already registered for the Uzbekistan electronic-services VAT regime do not get an exemption for their goods business: the thirty-day registration clock runs separately for goods activity, so a platform that only just added a marketplace-for-goods feature needs to check whether that starts a new registration window.
Proof
При реализации иностранными юридическими лицами через электронные торговые платформы физическим лицам товаров, местом реализации которых признается Республика Узбекистан, налоговая база определяется как стоимость данных товаров с учетом суммы налога, исчисленной исходя из фактических цен их реализацииWhere foreign legal entities sell goods to individuals through electronic trading platforms and the place of supply of those goods is deemed to be the Republic of Uzbekistan, the tax base is determined as the value of those goods including the amount of tax, calculated from their actual sale prices.
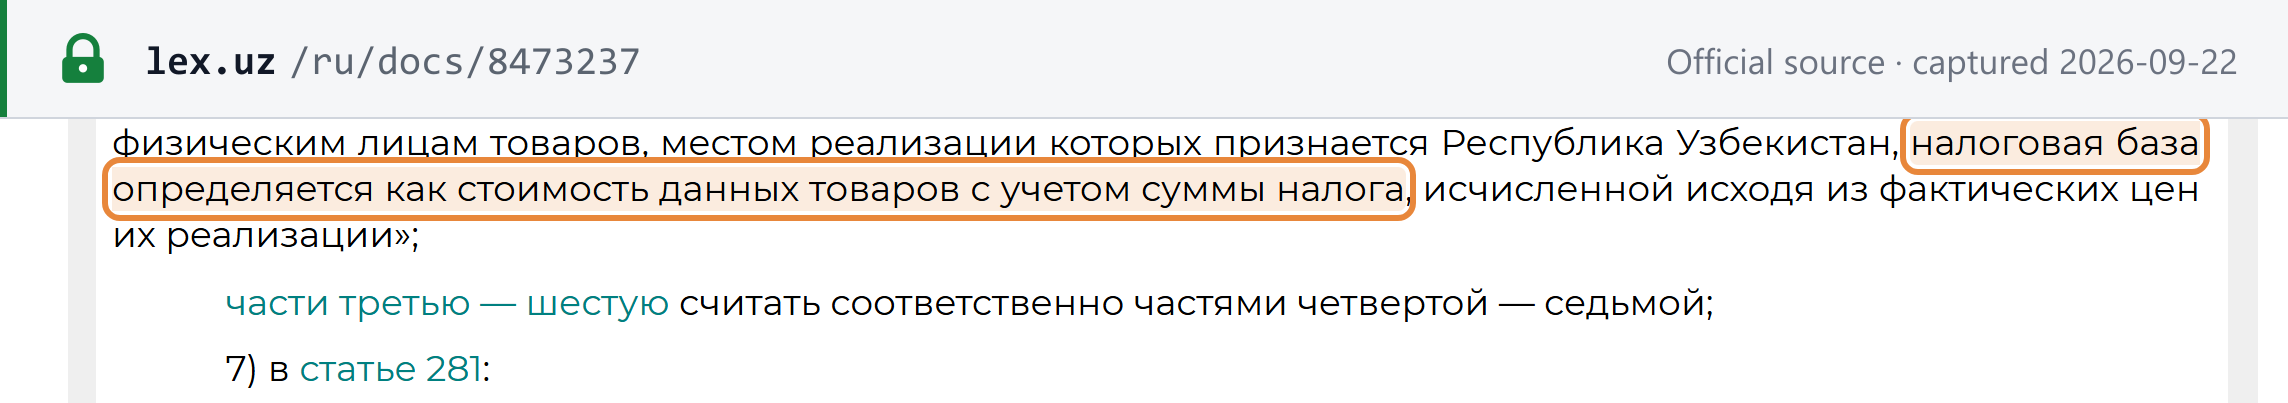 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · lex.uz