Vietnam's 8% reduced VAT rate under Resolution 204/2025/QH15 ends 31 December 2026
This page records one dated change. For the rules in Vietnam as they stand today, see the Vietnam guide →
- Jurisdiction
- Vietnam
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Effective
- 1 January 2027
- Authority
- Báo Điện tử Chính phủ (Government of Vietnam e-newspaper, baochinhphu.vn)
- Systems
- Invoicing, Tax engine, POS, ERP, E-commerce
- Verified
- Fetched from official source · medium confidence
VAT-registered businesses in Vietnam supplying goods and services that currently qualify for the 8% rate.
Prepare invoicing and tax-engine rate tables for the 8% rate to lapse to 10% on 1 January 2027 unless the National Assembly adopts an extension at its autumn session.
InvoicingTax enginePOSERPE-commerce
National Assembly Resolution 204/2025/QH15 on VAT reduction applies a 2-point cut (10% to 8%) to goods and services under Article 9(3) of VAT Law 48/2024/QH15, except telecommunications, financial, banking, securities, insurance, real estate, metal products, mining (other than coal) and excise-taxable goods (other than petrol), and has effect from 1 July 2025 to 31 December 2026. No resolution, decree or official proposal extending the 8% rate beyond 31 December 2026 was found as of 5 October 2026, so the 10% rate would apply again from 1 January 2027 absent a new instrument.
What changed in detail
National Assembly Resolution 204/2025/QH15 reduces VAT by 2 percentage points, from 10% to 8%, for goods and services under Article 9(3) of VAT Law 48/2024/QH15. The excluded categories are telecommunications, financial, banking, securities, insurance, real estate, metal products, mining (other than coal) and excise-taxable goods (other than petrol).
The resolution has effect from 1 July 2025 to 31 December 2026.
As of 5 October 2026 no resolution or decree extending the 8% rate beyond 31 December 2026 was found; a recommendation from the customs authority to extend it has been reported. Absent a new instrument, the 10% rate would apply again from 1 January 2027.
What it means
The end date is fixed in the resolution itself, so the default is a return to 10% on 1 January 2027 unless the National Assembly or Government acts. That is a conclusion from the absence of an extension, not an announcement by the authorities.
Businesses should model both outcomes in pricing and invoicing systems for the turn of the year, and check for a new instrument before finalising the January 2027 configuration.
Proof
Nghị quyết này có hiệu lực thi hành từ ngày 1/7/2025 đến hết ngày 31/12/2026.This Resolution takes effect from 1 July 2025 to the end of 31 December 2026.
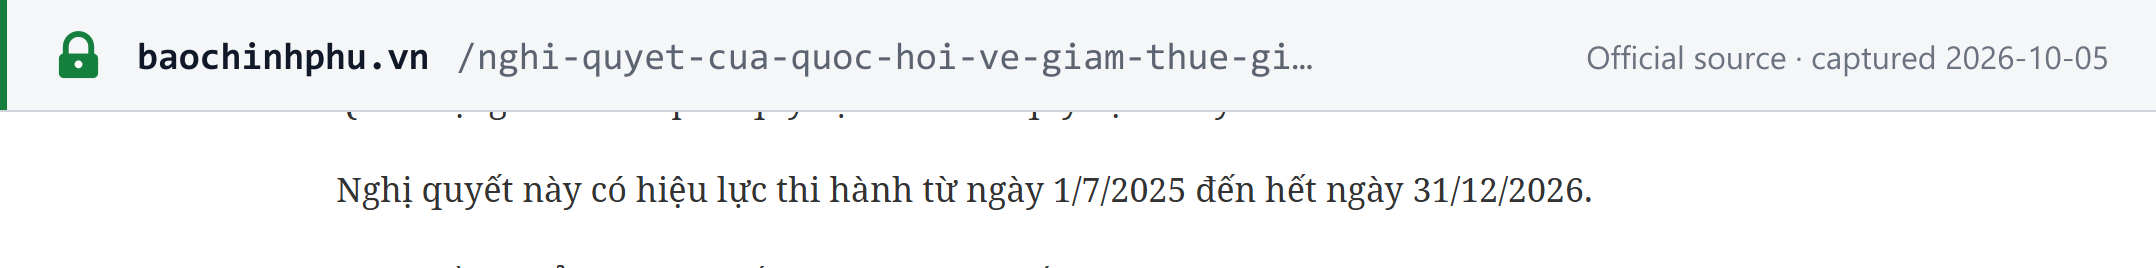 Source snapshot of the official page. Open full size ↗