Foreign suppliers to Vietnam may register for e-invoices, but Decree 254/2026 does not require it
This page records one dated change. For the rules in Vietnam as they stand today, see the Vietnam guide →
- Jurisdiction
- Vietnam
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2026
- Effective
- 1 July 2026
- Authority
- Công Báo — Official Gazette of the Government of Vietnam
- Verified
- Fetched from official source · high confidence
Foreign organisations with taxable revenue in Vietnam, including operators of offshore e-commerce and digital platforms, considering whether to register to use Vietnamese e-invoices under Decree No. 254/2026/NĐ-CP.
No action required for foreign suppliers; registration to use Vietnamese e-invoices is voluntary.
Decree No. 254/2026/NĐ-CP (30 June 2026, effective 1 July 2026), which implements the Law on Tax Administration No. 108/2025/QH15 on e-invoices, provides in Article 2(1)(đ) that foreign organisations with taxable revenue in Vietnam, including operators of offshore e-commerce and digital platforms, register voluntarily ('đăng ký tự nguyện') to use e-invoices under the Decree. This corrects vn-tax-administration-law-108-2026 (2026-W26), which stated that non-resident platform operators must issue Vietnamese e-invoices.
What changed in detail
This corrects the record of Law No. 108/2025/QH15 (the Tax Administration Law), which stated that non-resident platform operators must issue Vietnamese e-invoices. They are not required to.
Decree No. 254/2026/NĐ-CP, which implements the Tax Administration Law’s e-invoicing provisions and took effect 1 July 2026, provides at Article 2(1)(đ) that foreign organisations with taxable revenue in Vietnam — including operators of offshore e-commerce and digital platforms — register voluntarily (“đăng ký tự nguyện”) to use e-invoices under the Decree.
What it means
No action is required of a foreign platform operator on this specific point: registering to issue Vietnamese e-invoices is an option under Decree 254/2026, not a mandate. A foreign supplier should not build a Vietnamese e-invoicing compliance programme around an obligation the implementing decree does not impose — though its other duties, including withholding and remitting VAT for sellers on its platform where it controls ordering or payment, are unaffected by this correction.
Proof
đ) Tổ chức nước ngoài (bao gồm cả chủ quản nền tảng thương mại điện tử, nền tảng số ở nước ngoài) có hoạt động kinh doanh trên nền tảng thương mại điện tử và các dịch vụ khác có phát sinh doanh thu tính thuế tại Việt Nam (sau đây gọi là nhà cung cấp nước ngoài) đăng ký tự nguyện sử dụng hóa đơn điện tử theo quy định tại Nghị định này.đ) Foreign organisations (including operators of offshore e-commerce platforms and digital platforms) that conduct business on e-commerce platforms and other services generating taxable revenue in Vietnam (hereafter, foreign suppliers) register voluntarily to use e-invoices under this Decree.
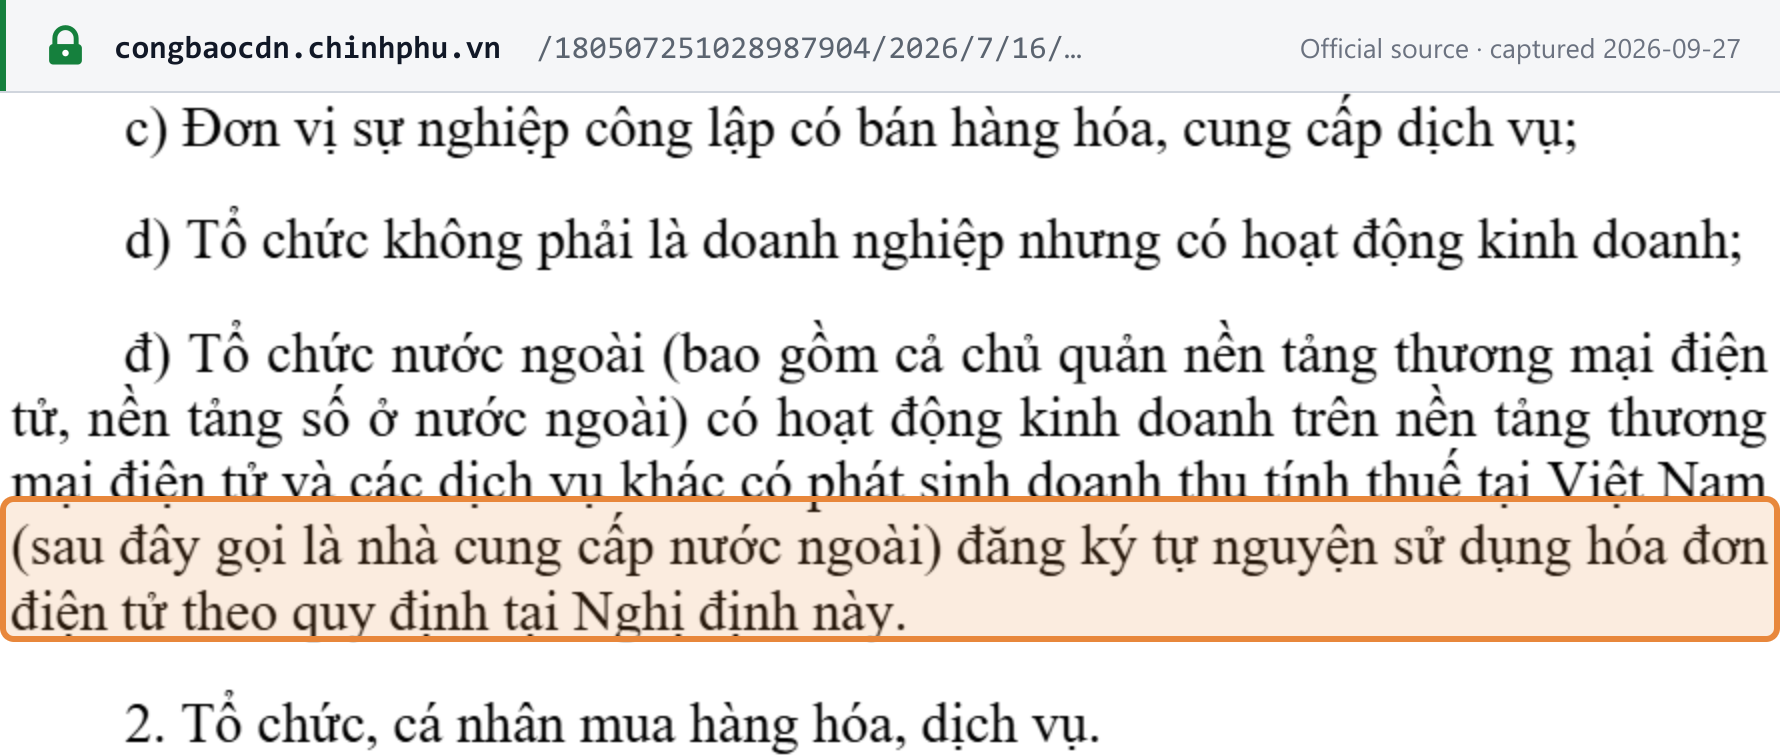 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Law No. effective 1 July 2026