Zimbabwe adds a 10% export line to the VAT return as the Finance Act 2025 changes go live in TaRMS
This page records one dated change. For the rules in Zimbabwe as they stand today, see the Zimbabwe guide →
- Jurisdiction
- Zimbabwe
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Watch
- Announced
- 4 September 2026
- Effective
- 1 January 2026
- Authority
- Zimbabwe Revenue Authority (ZIMRA)
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Zimbabwean registered operators declaring output tax on export supplies, and any taxpayer that must self-register in TaRMS for one of the new 2026 tax types before a return will be generated.
Exporters should confirm in TaRMS whether any of their export supplies now fall under the new 'Supply of goods/services at 10% (Exports)' output-tax category rather than the standard zero-rating, and declare accordingly.
Tax engineReporting
ZIMRA Public Notice 50 of 2026 (issued 4 September 2026) confirms that, among the 2026 legislative changes made by the Finance Act, 2025 (Act No. 7 of 2025) and now configured in ZIMRA's Tax and Revenue Management System (TaRMS) with effect from 1 January 2026, a new rate line 'Supply of goods/services at 10% (Exports)' has been added to the Declaration of Output Tax section of the VAT return for the Remittance of Value Added Tax.
What changed in detail
Public Notice 50 of 2026, issued by the Zimbabwe Revenue Authority on 4 September 2026, advises taxpayers that the 2026 legislation changes introduced by the Finance Act No. 7 of 2025, effective 1 January 2026, have now been configured in the Tax and Revenue Management System (TaRMS).
For VAT, the notice lists among the changes to existing tax types and returns a new rate for “Supply of goods/services at 10% (Exports)” under the Return for Remittance of Value Added Tax, Declaration of Output Tax.
The same deployment adds new tax types with their own returns — Gaming Operator’s Tax, Presumptive Rental Income Tax, Withholding Tax on Digital Services, Domestic Minimum Top-Up Tax, and Special Capital Gains Tax on the transfer of shares or interests in land-holding entities. A taxpayer has to register for each tax type in the TaRMS self-service portal before the system will generate returns; registration is auto-approved, and pending returns are then generated from the effective date of registration captured.
Other listed changes: coal and cut or uncut dimensional stone added to the Levy on Specified Minerals at 3%; new gold royalty bands for other miners of 5% above US$1,200 and up to US$5,000 an ounce and 10% above US$5,000; a capital gains tax exemption for transfers of shareholding from government-owned enterprises to specified entities; a “Tax Credit for Certain Sports Expenditure” field on income tax returns; and the removal of the Bookmakers Tax and the withholding tax on betting punters’ gross winnings from 1 January 2026.
What it means
The VAT line is the item to check first, because a 10% output rate on exports is not how exports normally work. Zimbabwe zero-rates most exports, so a separate 10% export category in the output-tax declaration means some class of export supply now carries tax — and the notice announces the field, not its scope. Map nothing to it without reading the Finance Act provision behind it.
The rest is registration housekeeping with a trap in it. TaRMS generates pending returns from the effective date of registration you capture, and ZIMRA is asking taxpayers who have been filing manually to complete the same returns in the system so they do not sit pending. Register a new tax type with a carelessly early effective date and you inherit a run of returns nobody intended to owe.
Proof
A new rate for ‘Supply of goods/services at 10% (Exports)’ under the Return for Remittance of Value Added Tax, Declaration of Output Tax.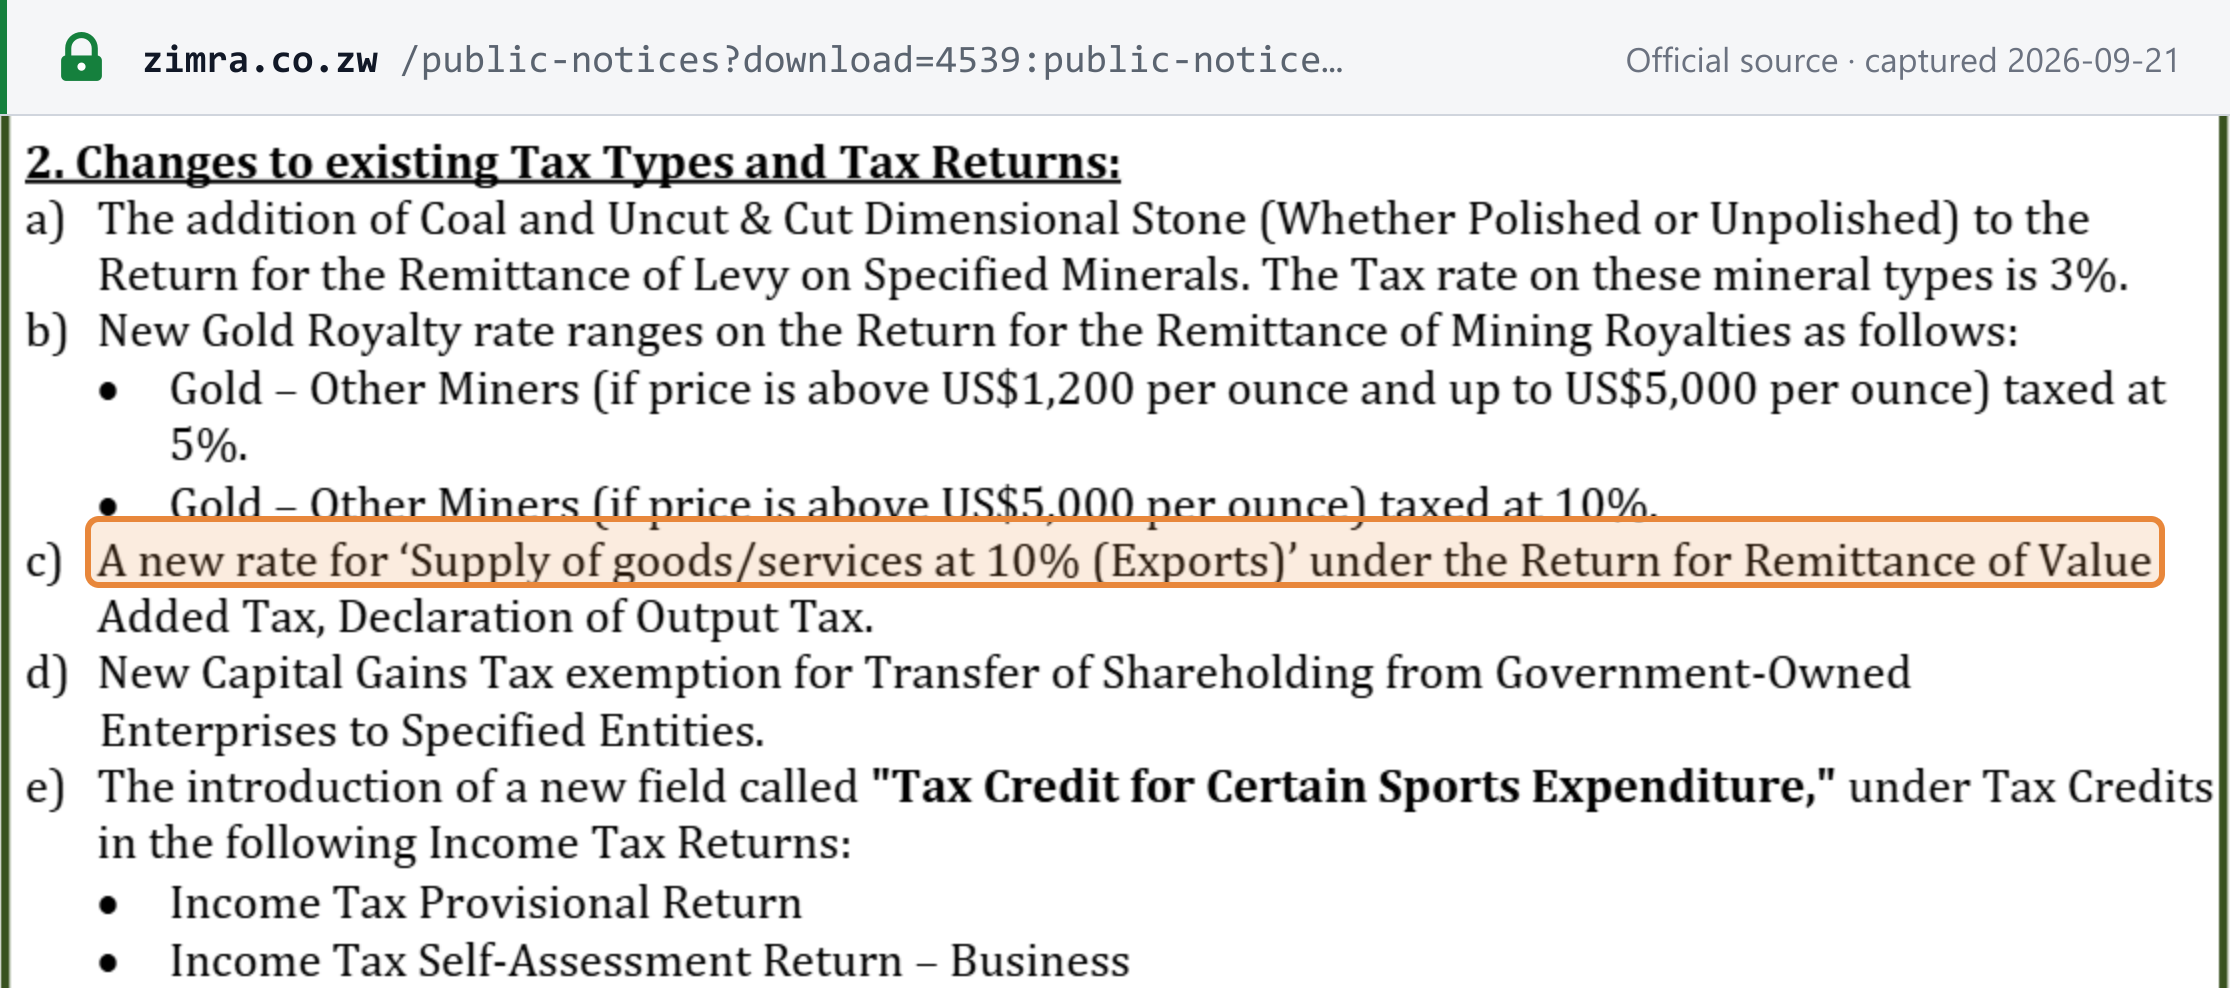 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · ZIMRA Public Notice 50 of 2026, issued on 04/09/2026 — "New 2026 Legislation Changes Introduced by Finance Act No. 7 Of 2025, Deployed in TaRMS" (2 pp.) · www.zimra.co.zw