Canada compliance calendar

21 recurring Goods and services tax / harmonized sales tax (GST/HST), Québec sales tax (QST) and Excise duty (Excise Act, 2001) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Canada rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Return filing Payment Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Canada applies one — 14 of 21 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

GST/HST return and payment — monthly filers

Goods and services tax / harmonized sales tax (GST/HST) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-14
Who files
GST/HST registrants with annual taxable supplies over CAD 6,000,000 (assigned monthly), and any smaller registrant that elects monthly filing
Notes
File and pay by the end of the following month — the CRA's own example puts a July period at 31 August. A return is required for every month, including months with no sales and no tax to remit. The September 2026 return moves to Monday 2 November because 31 October is a Saturday. Most registrants must file electronically. Québec businesses whose GST/HST is administered by Revenu Québec follow its schedule, which put the November 2026 deadline at 5 January 2027.
Source
Reporting requirements and deadlines – File your GST/HST return Canada Revenue Agency
See the source text
“If your reporting period is monthly or quarterly, your filing and payment deadline is 1 month after the end of the reporting period.”
Screenshot of Canada Revenue Agency showing the GST/HST return and payment — monthly filers deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST return and payment — quarterly filers

Goods and services tax / harmonized sales tax (GST/HST) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-14
Who files
GST/HST registrants with annual taxable supplies over CAD 1,500,000 up to CAD 6,000,000 (assigned quarterly), and smaller registrants that elect quarterly filing; quarters follow the registrant's fiscal year
Notes
Quarterly filers have until the last day of the month after the quarter: a quarter ending 31 March is due 30 April. The dates shown assume a 31 December year-end; a business with another year-end has quarters that close in different months, with the same one-month gap. Weekends push the deadline out — the fourth quarter of 2026 is due Monday 1 February 2027 — and the CRA also accepts the Tuesday after the Civic Holiday outside Québec, for instance 3 August 2027 for the second quarter.
Source
Reporting requirements and deadlines – File your GST/HST return Canada Revenue Agency
See the source text
“If your reporting period is monthly or quarterly, your filing and payment deadline is 1 month after the end of the reporting period.”
Screenshot of Canada Revenue Agency showing the GST/HST return and payment — quarterly filers deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST annual return and payment — 31 December year-end

Goods and services tax / harmonized sales tax (GST/HST) · Annually · return filing

31st March each year Verified 2026-10-14
Who files
Annual filers (annual taxable supplies of CAD 1,500,000 or less, unless they elect a shorter period) with a fiscal year ending 31 December, other than sole proprietors with business income and listed financial institutions
Notes
Corporations and other annual filers with a calendar fiscal year file and pay the balance by 31 March — Wednesday 31 March 2027 for 2026. For an annual filer this is the only return of the year. If you owed CAD 3,000 or more in net tax, quarterly instalments are due during the year as well, and the 31 March payment settles whatever they did not cover.
Source
Reporting requirements and deadlines – File your GST/HST return (Annual reporting periods) Canada Revenue Agency
See the source text
“For most businesses that file annually, your filing and final payment deadline is 3 months after your fiscal year-end.”
Screenshot of Canada Revenue Agency showing the GST/HST annual return and payment — 31 December year-end deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST annual return and payment — fiscal years not ending 31 December

Goods and services tax / harmonized sales tax (GST/HST) · Annually · return filing

within 3 months of the end of the fiscal year Verified 2026-10-14
Who files
Annual filers whose fiscal year ends on a date other than 31 December (listed financial institutions excepted)
Notes
An annual filer whose year ends in any other month has three months after the year-end: the CRA's example is a 31 August year-end due 30 November. A sole proprietor with a non-calendar year is on this three-month rule too, because the 15 June concession needs a 31 December year-end.
Source
Reporting requirements and deadlines – File your GST/HST return (Annual reporting periods) Canada Revenue Agency
See the source text
“For most businesses that file annually, your filing and final payment deadline is 3 months after your fiscal year-end.”
Screenshot of Canada Revenue Agency showing the GST/HST annual return and payment — fiscal years not ending 31 December deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST annual return — sole proprietors with business income (file by 15 June)

Goods and services tax / harmonized sales tax (GST/HST) · Annually · return filing

15th June each year Verified 2026-10-14
Who files
Individuals (sole proprietors) who file GST/HST annually, have a 31 December fiscal year-end and had business income for income-tax purposes that year
Notes
A self-employed individual gets until 15 June to file the year's return — Tuesday 15 June 2027 for 2026 — matching the income-tax filing date. The extension covers the paperwork only: the tax is due six weeks earlier, on 30 April, and interest runs on anything paid after that.
Source
Reporting requirements and deadlines – File your GST/HST return (Exception for sole proprietors) Canada Revenue Agency
See the source text
“If you meet all of the following criteria, your payment deadline is April 30 and your filing deadline is June 15:”
Screenshot of Canada Revenue Agency showing the GST/HST annual return — sole proprietors with business income (file by 15 June) deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST payment — sole proprietors filing annually (pay by 30 April)

Goods and services tax / harmonized sales tax (GST/HST) · Annually · payment

30th April each year Verified 2026-10-14
Who files
The same sole proprietors who file by 15 June: individuals with business income, a 31 December year-end and annual GST/HST filing
Notes
Pay the year's net GST/HST by 30 April even though the return can wait until June. In 2028, 30 April is a Sunday, so the payment is on time on Monday 1 May. A sole proprietor who also pays instalments has two payments on the same day: the balance for last year and the first instalment for this one.
Source
Reporting requirements and deadlines – File your GST/HST return (Exception for sole proprietors) Canada Revenue Agency
See the source text
“If you meet all of the following criteria, your payment deadline is April 30 and your filing deadline is June 15:”
Screenshot of Canada Revenue Agency showing the GST/HST payment — sole proprietors filing annually (pay by 30 April) deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST quarterly instalments — annual filers

Goods and services tax / harmonized sales tax (GST/HST) · Quarterly · payment

last day of the month after the quarter ends Verified 2026-10-14
Who files
Annual filers whose net tax was CAD 3,000 or more for the previous fiscal year and is CAD 3,000 or more for the current one; dates shown are for a 31 December year-end
Notes
An annual filer that owes CAD 3,000 or more pays a quarter of its expected tax four times a year, on 30 April, 31 July, 31 October and 31 January for a calendar year. Below CAD 3,000 in either year there are no instalments. The CRA counts a payment as on time if it is received, or postmarked, by the next business day after a weekend or holiday, so the October 2026 instalment can be paid on Monday 2 November.
Source
When to pay – GST/HST instalments Canada Revenue Agency
See the source text
“Instalment payments are due within one month after the end of each of your fiscal quarters.”
Screenshot of Canada Revenue Agency showing the GST/HST quarterly instalments — annual filers deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

Simplified GST/HST return and payment — non-resident digital suppliers and platform operators

Goods and services tax / harmonized sales tax (GST/HST) — simplified registration · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-14
Who files
Non-resident vendors of digital products and services, and distribution and accommodation platform operators, registered under the simplified GST/HST regime (not carrying on business in Canada)
Notes
Simplified registrants always report by calendar quarter, online only, and pay by the return's due date: 30 April, 31 July, 31 October and 31 January. There is no monthly or annual option. A due date on a weekend or federal holiday moves to the next business day, so the third quarter of 2026 is due Monday 2 November and the fourth quarter Monday 1 February 2027.
Source
Complete and file a return: GST/HST for digital-economy businesses Canada Revenue Agency
See the source text
“Your reporting period is a calendar quarter. You are required to file your return within one month after the end of the reporting period.”
Screenshot of Canada Revenue Agency showing the Simplified GST/HST return and payment — non-resident digital suppliers and platform operators deadline Open full size Captured from Canada Revenue Agency on 2026-10-14

GST/HST registration — 30-day window after ceasing to be a small supplier

Goods and services tax / harmonized sales tax (GST/HST) · One-off · registration

within 29 days of the first taxable supply made in Canada other than as a small supplier Verified 2026-10-14
Who files
Persons making taxable supplies in Canada whose worldwide taxable supplies (with associates) exceed CAD 30,000 in a single calendar quarter or over four consecutive quarters (CAD 50,000 for public service bodies); taxi and ride-sharing operators regardless of revenue
Notes
Apply before the 30th day after your first taxable sale made other than as a small supplier — in the CRA's words, within 29 days. Crossing CAD 30,000 in a single quarter ends small-supplier status on the very sale that crosses it, and GST/HST is chargeable on that sale; crossing it only over four quarters ends the status at the end of the month after that quarter. Taxi and ride-sharing drivers must register from their first fare.
Source
Excise Tax Act (R.S.C. 1985, c. E-15), s. 240(2.1) Justice Laws Website (Department of Justice Canada)
See the source text
“must apply to the Minister for registration before the day that is 30 days after”
Screenshot of Justice Laws Website (Department of Justice Canada) showing the GST/HST registration — 30-day window after ceasing to be a small supplier deadline Open full size Captured from Justice Laws Website (Department of Justice Canada) on 2026-10-14

Simplified GST/HST registration — non-resident vendors and platform operators

Goods and services tax / harmonized sales tax (GST/HST) — simplified registration · One-off · registration

no later than the day of crossing the CAD 30,000 threshold over any 12-month period Verified 2026-10-14
Who files
Non-resident vendors of digital products and services, and distribution and accommodation platform operators, not carrying on business in Canada, whose taxable supplies to Canadian consumers exceed CAD 30,000 in any 12-month period
Notes
Unlike the regular 30-day window, there is no grace period here: the application, made online, is due on or before the first day you are required to be registered, which is the day your sales to Canadian consumers over the past 12 months pass CAD 30,000. Keep a running 12-month total rather than checking once a year.
Source
Excise Tax Act (R.S.C. 1985, c. E-15), s. 211.12(2)–(3) Justice Laws Website (Department of Justice Canada)
See the source text
“is to be filed with the Minister by way of electronic filing on or before the first day on which the person is required to be registered under this Subdivision.”
Screenshot of Justice Laws Website (Department of Justice Canada) showing the Simplified GST/HST registration — non-resident vendors and platform operators deadline Open full size Captured from Justice Laws Website (Department of Justice Canada) on 2026-10-14

QST return and remittance — monthly filers (Revenu Québec)

Québec sales tax (QST) · Monthly · return filing

last day of the month after the month ends Verified 2026-10-14
Who files
QST registrants on a monthly filing frequency — assigned when total annual taxable sales made in Canada exceed CAD 6,000,000, or elected; the frequency must match the registrant's GST/HST frequency
Notes
The QST is reported to Revenu Québec, usually on the same return as the GST/HST and with the same frequency, and the amount owing is remitted when the return is filed. Revenu Québec publishes the exact dates each year: the last day of the next month, moved to the next business day when it is closed. Its offices close from 24 December to early January, so the November 2026 return is due 5 January 2027, later than shown here.
Source
Remittance Schedules of the QST and GST/HST Revenu Québec
See the source text
“If your filing deadline falls on a Saturday, Sunday or statutory holiday, the deadline is extended to the next day that is not a Saturday, Sunday or statutory holiday.”
Screenshot of Revenu Québec showing the QST return and remittance — monthly filers (Revenu Québec) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST return and remittance — quarterly filers (Revenu Québec)

Québec sales tax (QST) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-14
Who files
QST registrants on a quarterly filing frequency — total annual taxable sales in Canada over CAD 1,500,000 up to CAD 6,000,000, or elected; quarters follow the fiscal year shared with the GST/HST
Notes
Quarterly QST returns follow the GST/HST quarters exactly, because Revenu Québec requires the same fiscal year for both taxes. For a calendar year the third quarter of 2026 is due Monday 2 November and the fourth Monday 1 February 2027. A fiscal quarter ending in November falls due in the year-end closure, which Revenu Québec set at 5 January for 2026.
Source
Remittance Schedules of the QST and GST/HST Revenu Québec
See the source text
“If your filing deadline falls on a Saturday, Sunday or statutory holiday, the deadline is extended to the next day that is not a Saturday, Sunday or statutory holiday.”
Screenshot of Revenu Québec showing the QST return and remittance — quarterly filers (Revenu Québec) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST annual return and remittance — 31 December year-end

Québec sales tax (QST) · Annually · return filing

31st March each year Verified 2026-10-14
Who files
Annual QST filers (total annual taxable sales in Canada of CAD 1,500,000 or less) with a 31 December fiscal year, other than individuals with business income and listed financial institutions
Notes
Revenu Québec's schedule puts the 2026 annual return for corporations at 31 March 2027. With another year-end the return is due three months after it, so a 30 September year-end ran into the January closure and was due 5 January 2027. Listed financial institutions have six months instead.
Source
Filing frequency — Reporting the GST/HST and QST Revenu Québec
See the source text
“We must generally receive annual returns no later than three months following the end of the period covered by the return.”
Screenshot of Revenu Québec showing the QST annual return and remittance — 31 December year-end deadline Open full size Captured from Revenu Québec on 2026-10-14

QST annual return — individuals with business income (file by 15 June)

Québec sales tax (QST) · Annually · return filing

15th June each year Verified 2026-10-14
Who files
Individual QST registrants with business income (other than property income), an annual filing frequency and a 31 December fiscal year
Notes
Self-employed individuals in Québec file their QST and GST/HST returns for the year by 15 June, alongside their income-tax return. Property income alone does not qualify: the business income has to come from carrying on a business.
Source
Filing frequency — Reporting the GST/HST and QST Revenu Québec
See the source text
“you have until June 15 of the following year to file your GST/HST return and QST return:”
Screenshot of Revenu Québec showing the QST annual return — individuals with business income (file by 15 June) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST remittance — individuals with business income filing annually (pay by 30 April)

Québec sales tax (QST) · Annually · payment

30th April each year Verified 2026-10-14
Who files
The same individual registrants who file by 15 June: business income, annual filing frequency, 31 December fiscal year
Notes
The later filing date does not delay the money: QST and GST/HST owed for the year reach Revenu Québec by 30 April, which is the date its remittance schedule shows for these individuals. Friday 30 April 2027 is the next one; in 2028 the date falls on a Sunday and moves to Monday 1 May.
Source
Filing frequency — Reporting the GST/HST and QST Revenu Québec
See the source text
“Keep in mind, however, that you must remit any GST/HST or QST due by April 30 of the following year.”
Screenshot of Revenu Québec showing the QST remittance — individuals with business income filing annually (pay by 30 April) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST quarterly instalments — annual filers (Revenu Québec)

Québec sales tax (QST) · Quarterly · payment

last day of the month after the quarter ends Verified 2026-10-14
Who files
Annual QST filers whose net QST expected for the current year and paid for the previous year are each CAD 3,000 or more; dates shown are for a 31 December year-end
Notes
Revenu Québec applies the GST/HST instalment test to the QST separately: CAD 3,000 or more of net QST this year and last means four instalments, each due by the last day of the month after a fiscal quarter. Payments of CAD 10,000 or more must be made electronically. The annual return then reconciles the instalments against the tax actually owed.
Source
GST and QST instalments Revenu Québec
See the source text
“You must make your payments no later than one month after the last day of each quarter of your fiscal year.”
Screenshot of Revenu Québec showing the QST quarterly instalments — annual filers (Revenu Québec) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST return and remittance — specified system (suppliers outside Québec)

Québec sales tax (QST) — specified registration system · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-14
Who files
Suppliers outside Québec (including outside Canada) and digital platform operators registered under the specified QST system for supplies to Québec consumers
Notes
Specified-system registrants report each calendar quarter online through My Account for suppliers outside Québec, and file and pay by the last day of the following month. Revenu Québec does not say whether this date moves off a weekend, so treat a Saturday or Sunday as no extension: the third quarter of 2026 is due Saturday 31 October, so file by Friday the 30th, and the fourth quarter's Sunday 31 January 2027 deadline means paying by Friday 29 January.
Source
Reporting the QST — suppliers outside Québec (specified system) Revenu Québec
See the source text
“The filing and remittance deadline is the last day of the month following the calendar quarter that corresponds to the reporting period.”
Screenshot of Revenu Québec showing the QST return and remittance — specified system (suppliers outside Québec) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST registration — general system

Québec sales tax (QST) · One-off · registration

at least 1 day before your first taxable supply in Québec made other than as a small supplier Verified 2026-10-14
Who files
Persons making taxable supplies in Québec whose worldwide taxable supplies (with associates) exceed CAD 30,000 in a calendar quarter or over four consecutive quarters; retail tobacco vendors and vendors of new tyres and of new or used road vehicles regardless of revenue
Notes
You must apply for QST registration before you make your first taxable supply in Québec other than as a small supplier. That is stricter than the GST, which allows until the 30th day after that supply, so a business crossing CAD 30,000 can be late for the QST while still in time for the GST. Some sellers — of tobacco at retail, new tyres, and new or used road vehicles — must register for the QST whatever their sales.
Source
How to register for the GST and QST Revenu Québec
See the source text
“As a rule, you must apply for registration under the QST system before you make your first taxable supply in Québec other than as a small supplier”
Screenshot of Revenu Québec showing the QST registration — general system deadline Open full size Captured from Revenu Québec on 2026-10-14

QST registration — specified system (suppliers outside Québec)

Québec sales tax (QST) — specified registration system · One-off · registration

no later than the day of crossing the CAD 30,000 threshold over any 12-month period Verified 2026-10-14
Who files
Suppliers outside Canada not registered under the general GST/HST system (and other suppliers outside Québec eligible for the specified system) whose taxable supplies to Québec consumers exceed CAD 30,000 over 12 months
Notes
Foreign sellers of digital products and services — in Revenu Québec's words, incorporeal movable property or services — to Québec consumers register for the QST as soon as their Québec sales pass CAD 30,000 over a 12-month period; there is no grace period. Sales made through a platform that is itself QST-registered under the specified system do not count towards the total.
Source
Registration under the specified system — suppliers outside Canada who are not registered under the general GST/HST system Revenu Québec
See the source text
“However, as soon as your threshold amount exceeds $30,000, you must register under the specified system.”
Screenshot of Revenu Québec showing the QST registration — specified system (suppliers outside Québec) deadline Open full size Captured from Revenu Québec on 2026-10-14

QST platform information returns (VD-477.18.7-V and VD-477.18.8-V)

Québec sales tax (QST) — digital platform operators · Annually · report / listing

1st July each year Verified 2026-10-14
Who files
Operators of distribution platforms used for supplies of goods delivered in Québec, and of accommodation platforms used for short-term accommodation in Québec, that are QST-registered or required to be
Notes
Platform operators report the year's third-party sales made through their platform to Revenu Québec once a year, by 1 July of the following year: VD-477.18.7-V for goods marketplaces and VD-477.18.8-V for accommodation platforms. 1 July is Canada Day and Revenu Québec does not say whether the date moves, so file by 30 June. The federal equivalents are suspended — the CRA does not currently require them — but Québec's are not.
Source
Information returns and notices — suppliers outside Québec Revenu Québec
See the source text
“for every calendar year in which such supplies were made using their platform and file it by July 1 of the following calendar year.”
Screenshot of Revenu Québec showing the QST platform information returns (VD-477.18.7-V and VD-477.18.8-V) deadline Open full size Captured from Revenu Québec on 2026-10-14

Excise duty return and payment — Excise Act, 2001 licensees

Excise duty (Excise Act, 2001) — spirits, wine, tobacco, cannabis and vaping products · Monthly · return filing

last day of the month after the month ends Verified 2026-10-14
Who files
Persons licensed under the Excise Act, 2001 (spirits, wine, tobacco, cannabis and vaping-product licensees) with fiscal-month reporting periods; small spirits, wine and warehouse licensees (duty of CAD 120,000 or less) may be authorised to report by fiscal half-year
Notes
Licensed producers and warehouses file an excise return and pay the duty by the last day of the month after each reporting period, normally a month. When that day is a weekend or holiday the deadline moves to the next business day: the December 2026 return is due Monday 1 February 2027 and the January 2027 return Monday 1 March. Beer is taxed under a different Act and is not shown here.
Source
Excise Act, 2001 (S.C. 2002, c. 22), s. 160 Justice Laws Website (Department of Justice Canada)
See the source text
“shall, not later than the last day of the first month after each reporting period of the person,”
Screenshot of Justice Laws Website (Department of Justice Canada) showing the Excise duty return and payment — Excise Act, 2001 licensees deadline Open full size Captured from Justice Laws Website (Department of Justice Canada) on 2026-10-14

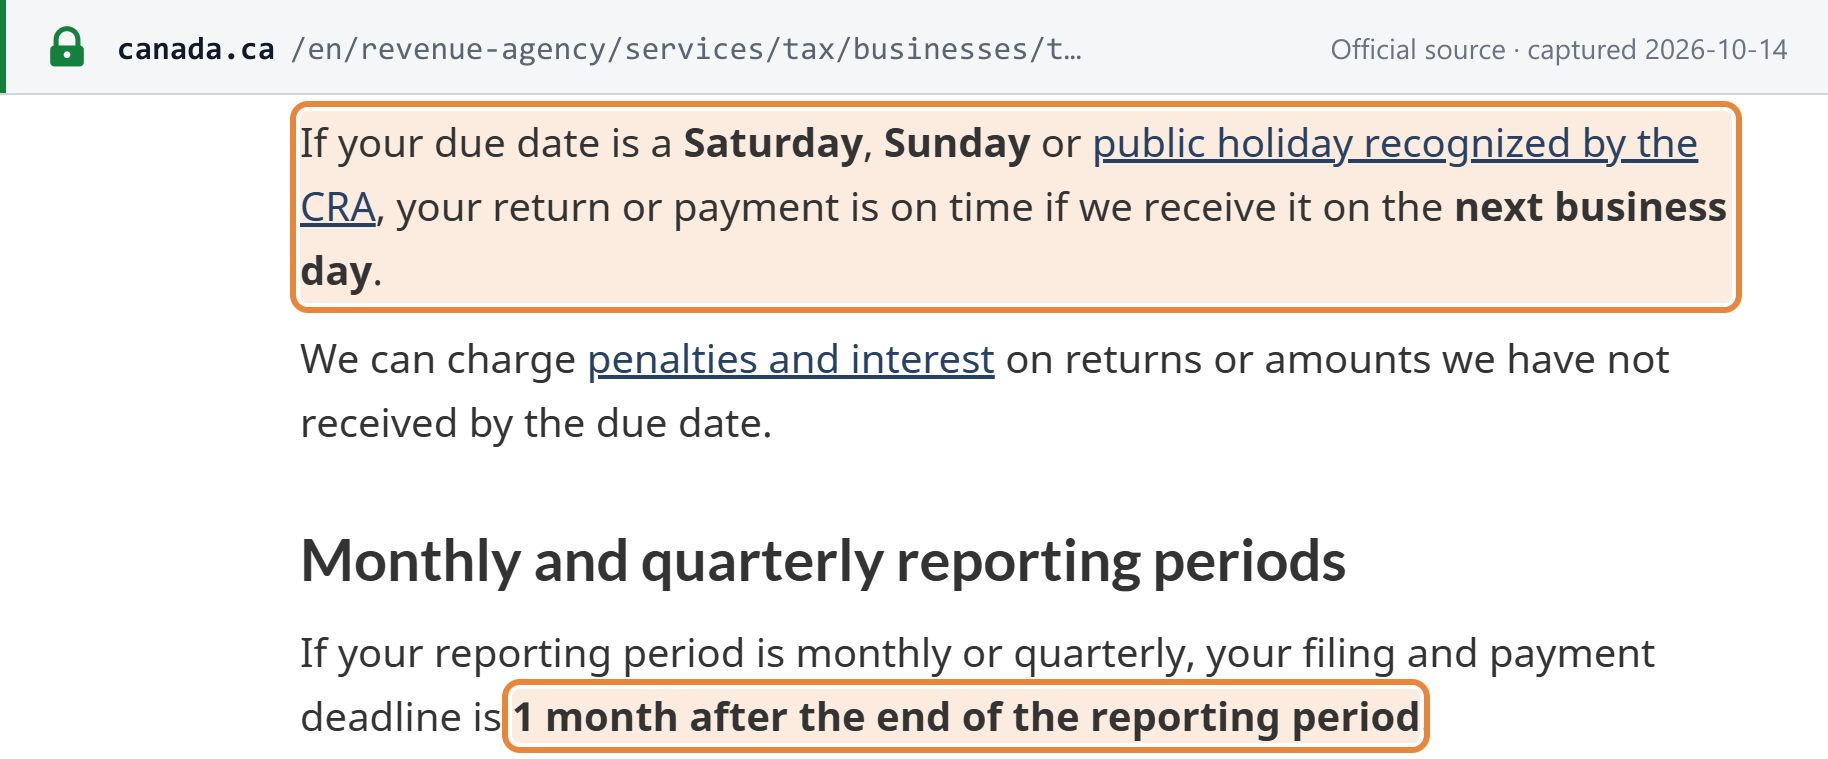
Canada's federal GST/HST return and its payment are due together, one month after each monthly or quarterly period ends; in practice both the CRA and Revenu Québec treat that as the last day of the following month. Annual filers have three months, or until 15 June (paying by 30 April) for sole proprietors with a 31 December year-end. The CRA accepts a return or payment on the next business day when the due date is a Saturday, Sunday or CRA public holiday. In Québec, Revenu Québec collects the Québec sales tax (QST) and, for most businesses, the GST/HST too, on the same return and the same schedule; its year-end office closures can push a 31 December deadline into early January. There is no separate annual reconciliation return for monthly or quarterly filers. Not covered here: the provincial sales taxes of British Columbia, Saskatchewan and Manitoba, which have their own returns, and GST on imports, which is paid to the Canada Border Services Agency.

“If your due date is a Saturday, Sunday or public holiday recognized by the CRA, your return or payment is on time if we receive it on the next business day.”
Screenshot of the official source stating the rule that governs Canada's deadlines
Reporting requirements and deadlines – File your GST/HST return — Canada Revenue Agency, captured 2026-10-14

What this calendar does not list

  • Not applicable Recapitulative listing — Canada has no recapitulative or sales listing: neither the CRA's GST/HST registrant guide (RC4022) nor Revenu Québec's GST/HST and QST reporting pages describe a periodic listing of a registrant's supplies (checked 2026-10-14). The federal platform information returns are suspended until further notice; Québec's annual platform information returns are shown separately.
  • Not applicable E-invoicing / e-reporting cycle — There is no federal e-invoicing or transaction-reporting mandate; the CRA requires electronic filing of returns, which is a format rule, not a reporting cycle. Québec's mandatory billing for restaurants, bars and paid passenger transport transmits each transaction as it happens, so it fixes no submission cadence.
  • Not yet covered Periodic return — Not yet covered: the provincial sales taxes administered by British Columbia (PST), Saskatchewan (PST) and Manitoba (RST), which have their own returns and due dates; GST/HST on imports, which is billed and collected by the Canada Border Services Agency; excise duty on beer, which falls under the older Excise Act rather than the Excise Act, 2001; and Revenu Québec's notice for operators of storage services in Québec (form VD-477.18.6-V).

About this calendar

Which Canada tax deadlines does this calendar cover?

21 recurring indirect-tax obligations — Goods and services tax / harmonized sales tax (GST/HST), Québec sales tax (QST) and Excise duty (Excise Act, 2001) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-14). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.