Finland compliance calendar

11 recurring Arvonlisävero (ALV / VAT), Valmistevero (excise duty) and Jätevero (waste tax) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Finland rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Finland applies one — 6 of 11 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Arvonlisäveroilmoitus (kausiveroilmoitus) — monthly VAT return

Arvonlisävero (ALV / VAT) · Monthly · return filing

12th of the 2nd month after the month ends Verified 2026-10-08
Who files
VAT-registered businesses on the default calendar-month tax period — every registrant that has not chosen, or does not qualify for, a quarterly or annual period
Notes
File in MyTax and pay by the 12th of the second month after each month — the October 2026 return is due Monday 14 December, because the 12th is a Saturday. A return is required for every month, including months with no VAT activity. The Tax Administration does not extend VAT deadlines. Importers on the VAT register declare import VAT on this return rather than paying it to Customs, and EU sales for the same month must already have been listed by the 20th of the following month.
Source
Laki oma-aloitteisten verojen verotusmenettelystä (768/2016) — 17 § 2 mom; payment 32 § 2 mom; tax period 11 § 1 mom Finlex (oikeusministeriö)
See the source text
“on annettava verokauden veroilmoitus viimeistään verokautta seuraavan toisen kalenterikuukauden yleisenä eräpäivänä.”
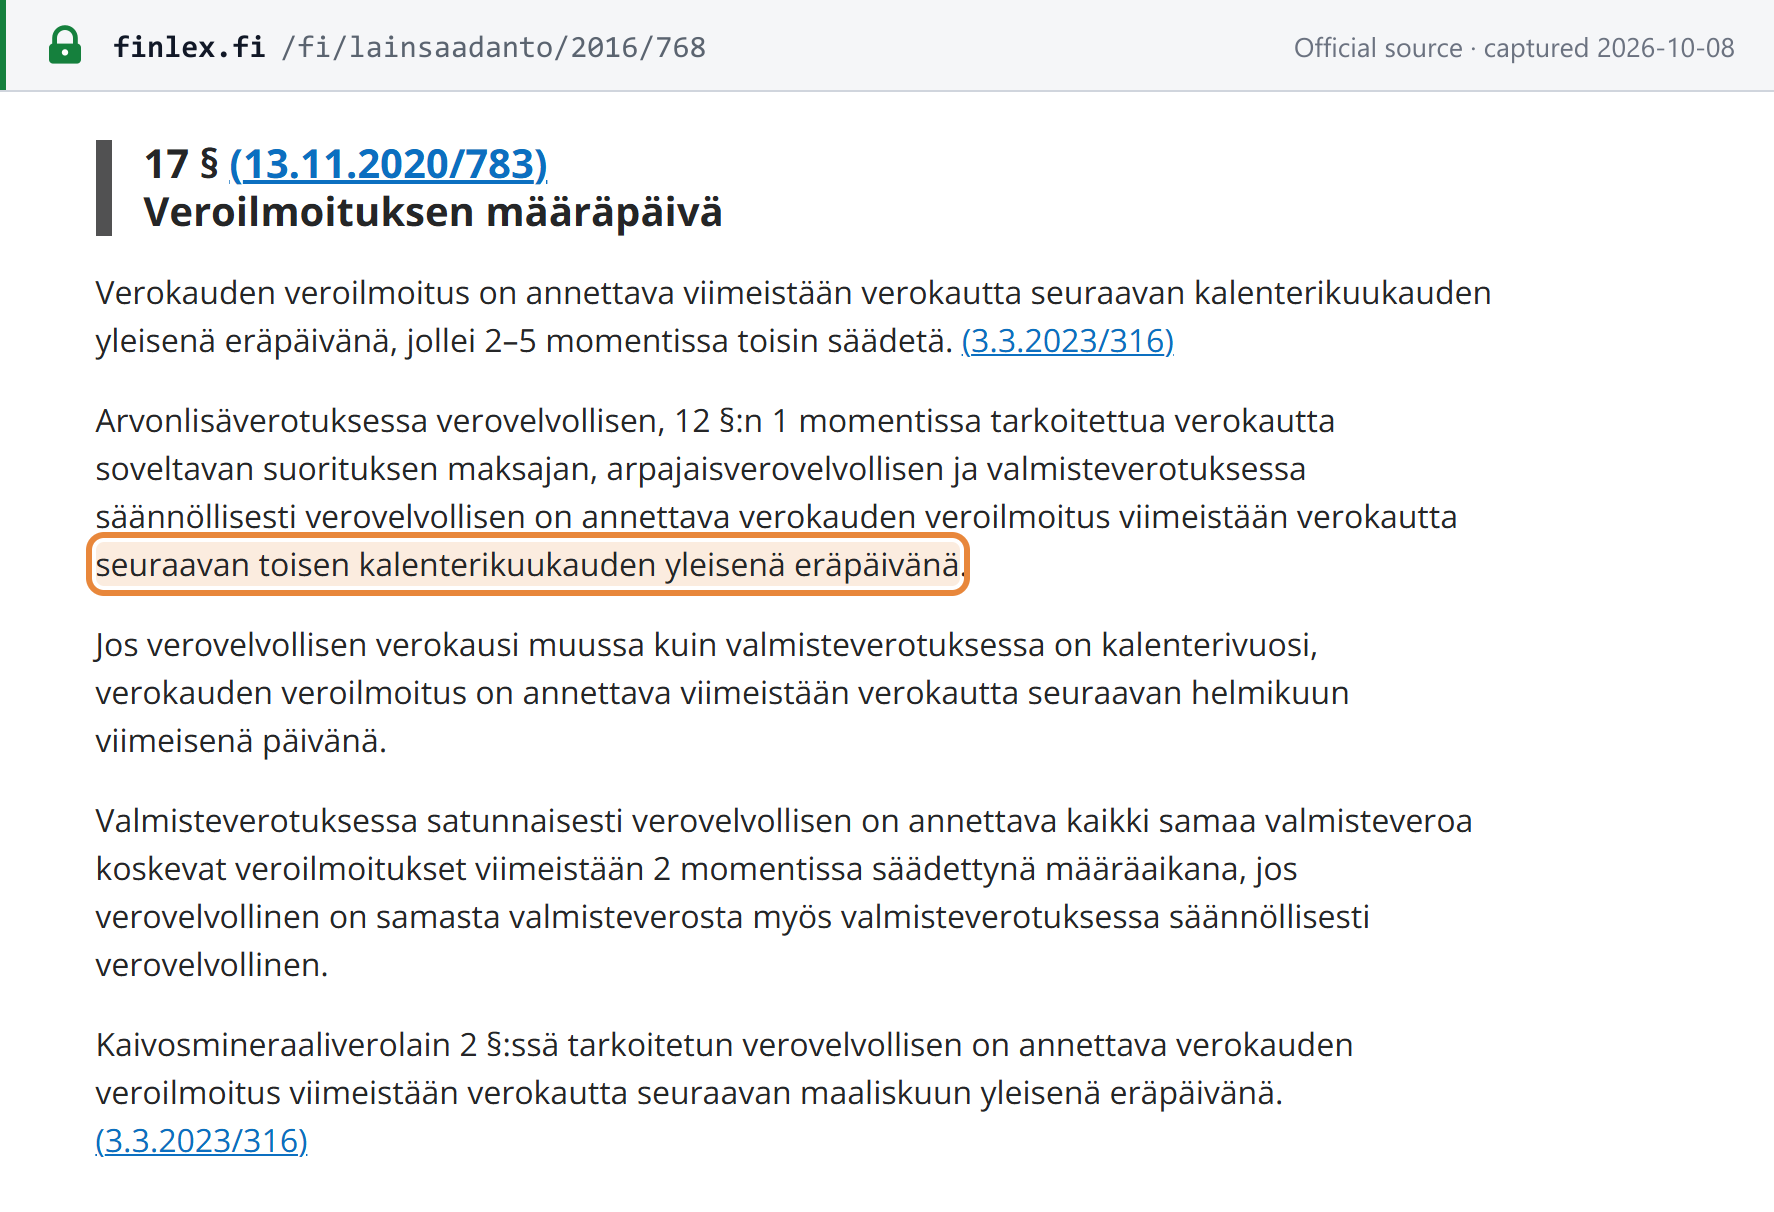
Screenshot of Finlex (oikeusministeriö) showing the Arvonlisäveroilmoitus (kausiveroilmoitus) — monthly VAT return deadline Open full size Captured from Finlex (oikeusministeriö) on 2026-10-08
Arvonlisäveroilmoitus — quarterly VAT return

Arvonlisävero (ALV / VAT) · Quarterly · return filing

12th of the 2nd month after the quarter ends Verified 2026-10-08
Who files
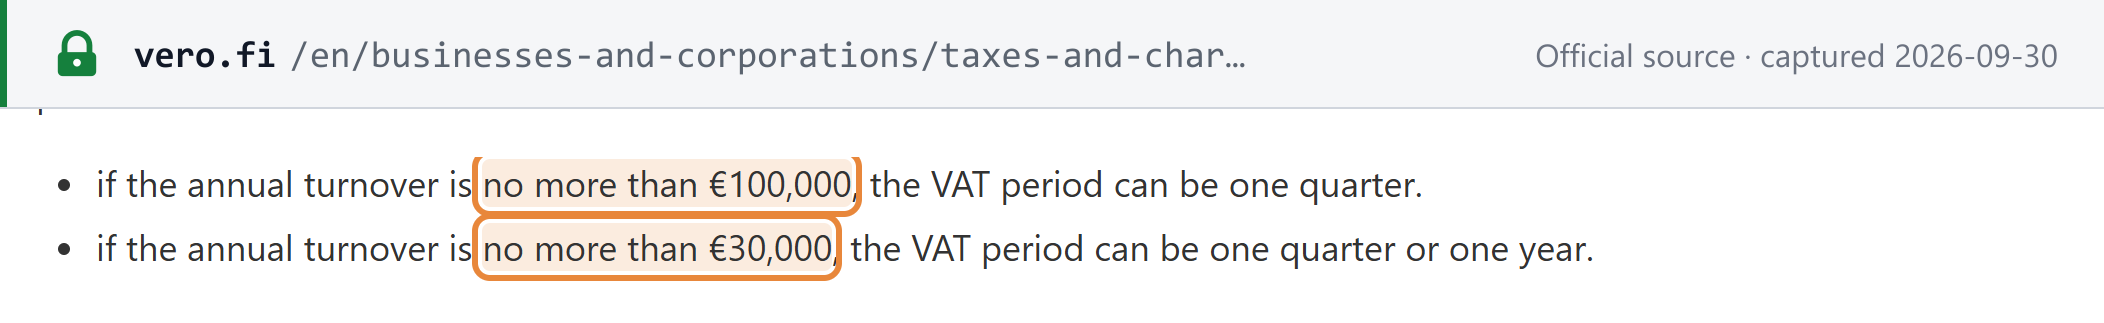
VAT-registered businesses with calendar-year turnover of no more than EUR 100,000 that have applied for a quarterly tax period
Notes
Smaller businesses can file once a quarter, by the 12th of the second month after it ends — 12 May, 12 August, 12 November and 12 February, or the next banking day when the 12th falls on a weekend or holiday. A chosen period must be kept for at least a year, and if turnover is likely to pass EUR 100,000 you must tell the Tax Administration without delay so you can be moved back to monthly returns.
Source
Verohallinto — Tax period (VAT); Laki oma-aloitteisten verojen verotusmenettelystä (768/2016) 12 § 1 mom and 17 § 2 mom Verohallinto
See the source text
“if the annual turnover is no more than €100,000, the VAT period can be one quarter.”
Screenshot of Verohallinto showing the Arvonlisäveroilmoitus — quarterly VAT return deadline Open full size Captured from Verohallinto on 2026-09-30

Arvonlisäveroilmoitus — annual VAT return (calendar-year period)

Arvonlisävero (ALV / VAT) · Annually · return filing

last day of the 2nd month after the year ends Verified 2026-10-08
Who files
Natural persons, estates and partnerships in primary production (farming, forestry, fishing) and visual artists with no other VAT-liable activity, who file annually by law; and businesses with turnover of no more than EUR 30,000 that have chosen a calendar-year period
Notes
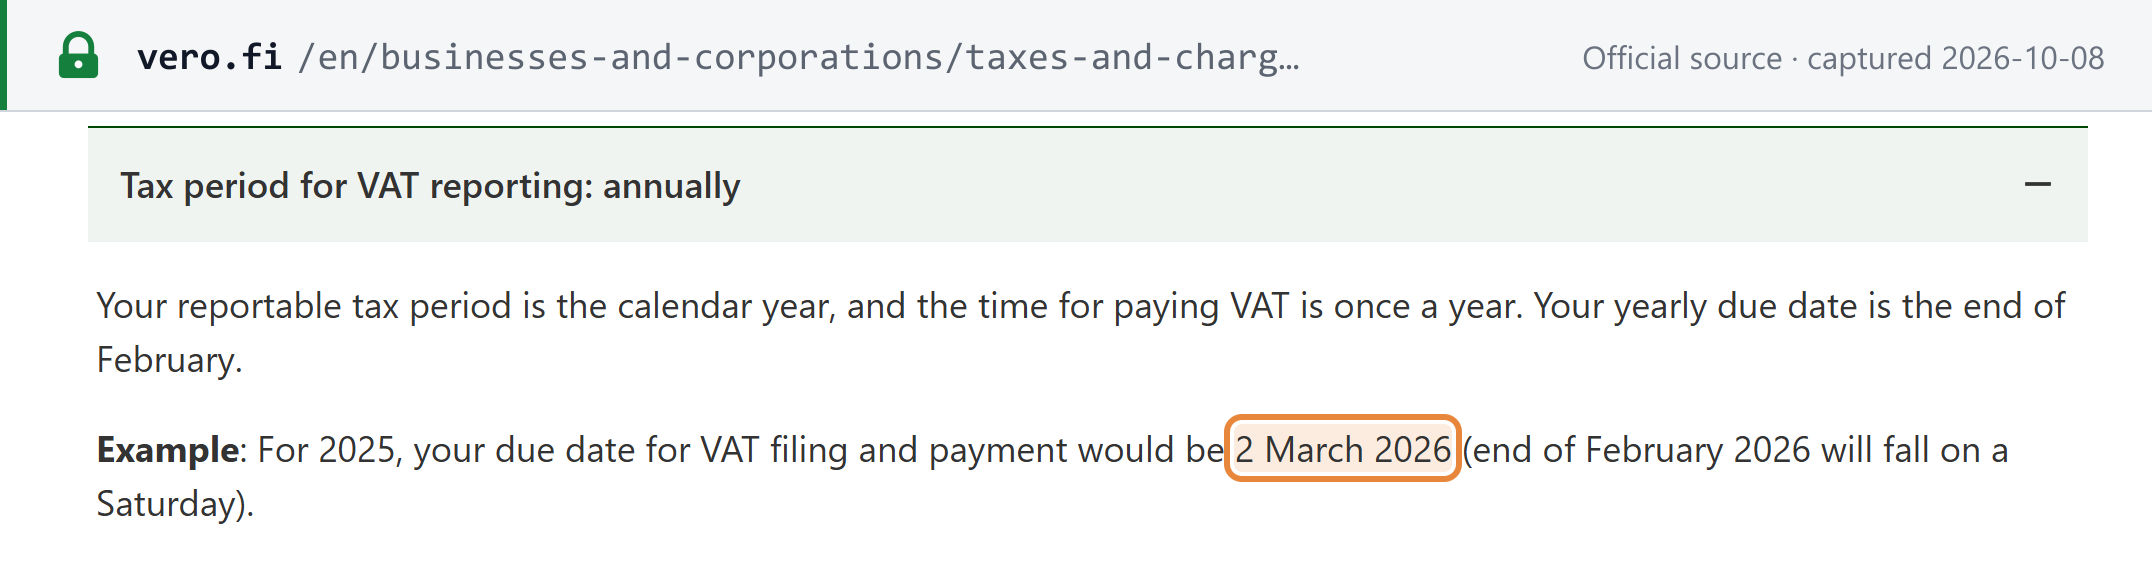
Annual filers report and pay a whole calendar year's VAT by the last day of February of the following year, moved to the next working day when it falls on a weekend or holiday: the 2026 return is due Monday 1 March 2027. If you stop trading part-way through the year, the final period ends on the day you stop and its return is due on the 12th of the second month after that month.
Source
Verohallinto — When to file and pay VAT; Laki oma-aloitteisten verojen verotusmenettelystä (768/2016) 17 § 3 mom and 32 § 3 mom Verohallinto
See the source text
“For 2025, your due date for VAT filing and payment would be 2 March 2026 (end of February 2026 will fall on a Saturday).”
Screenshot of Verohallinto showing the Arvonlisäveroilmoitus — annual VAT return (calendar-year period) deadline Open full size Captured from Verohallinto on 2026-10-08

Yhteenvetoilmoitus — EU sales recapitulative statement

Arvonlisävero (ALV / VAT) · Monthly · report / listing

20th of the month after the month ends Verified 2026-10-08
Who files
VAT-registered businesses that in the month made intra-EU supplies of goods, triangular-trade resales, call-off-stock transfers, or B2B services taxed in the customer's member state
Notes
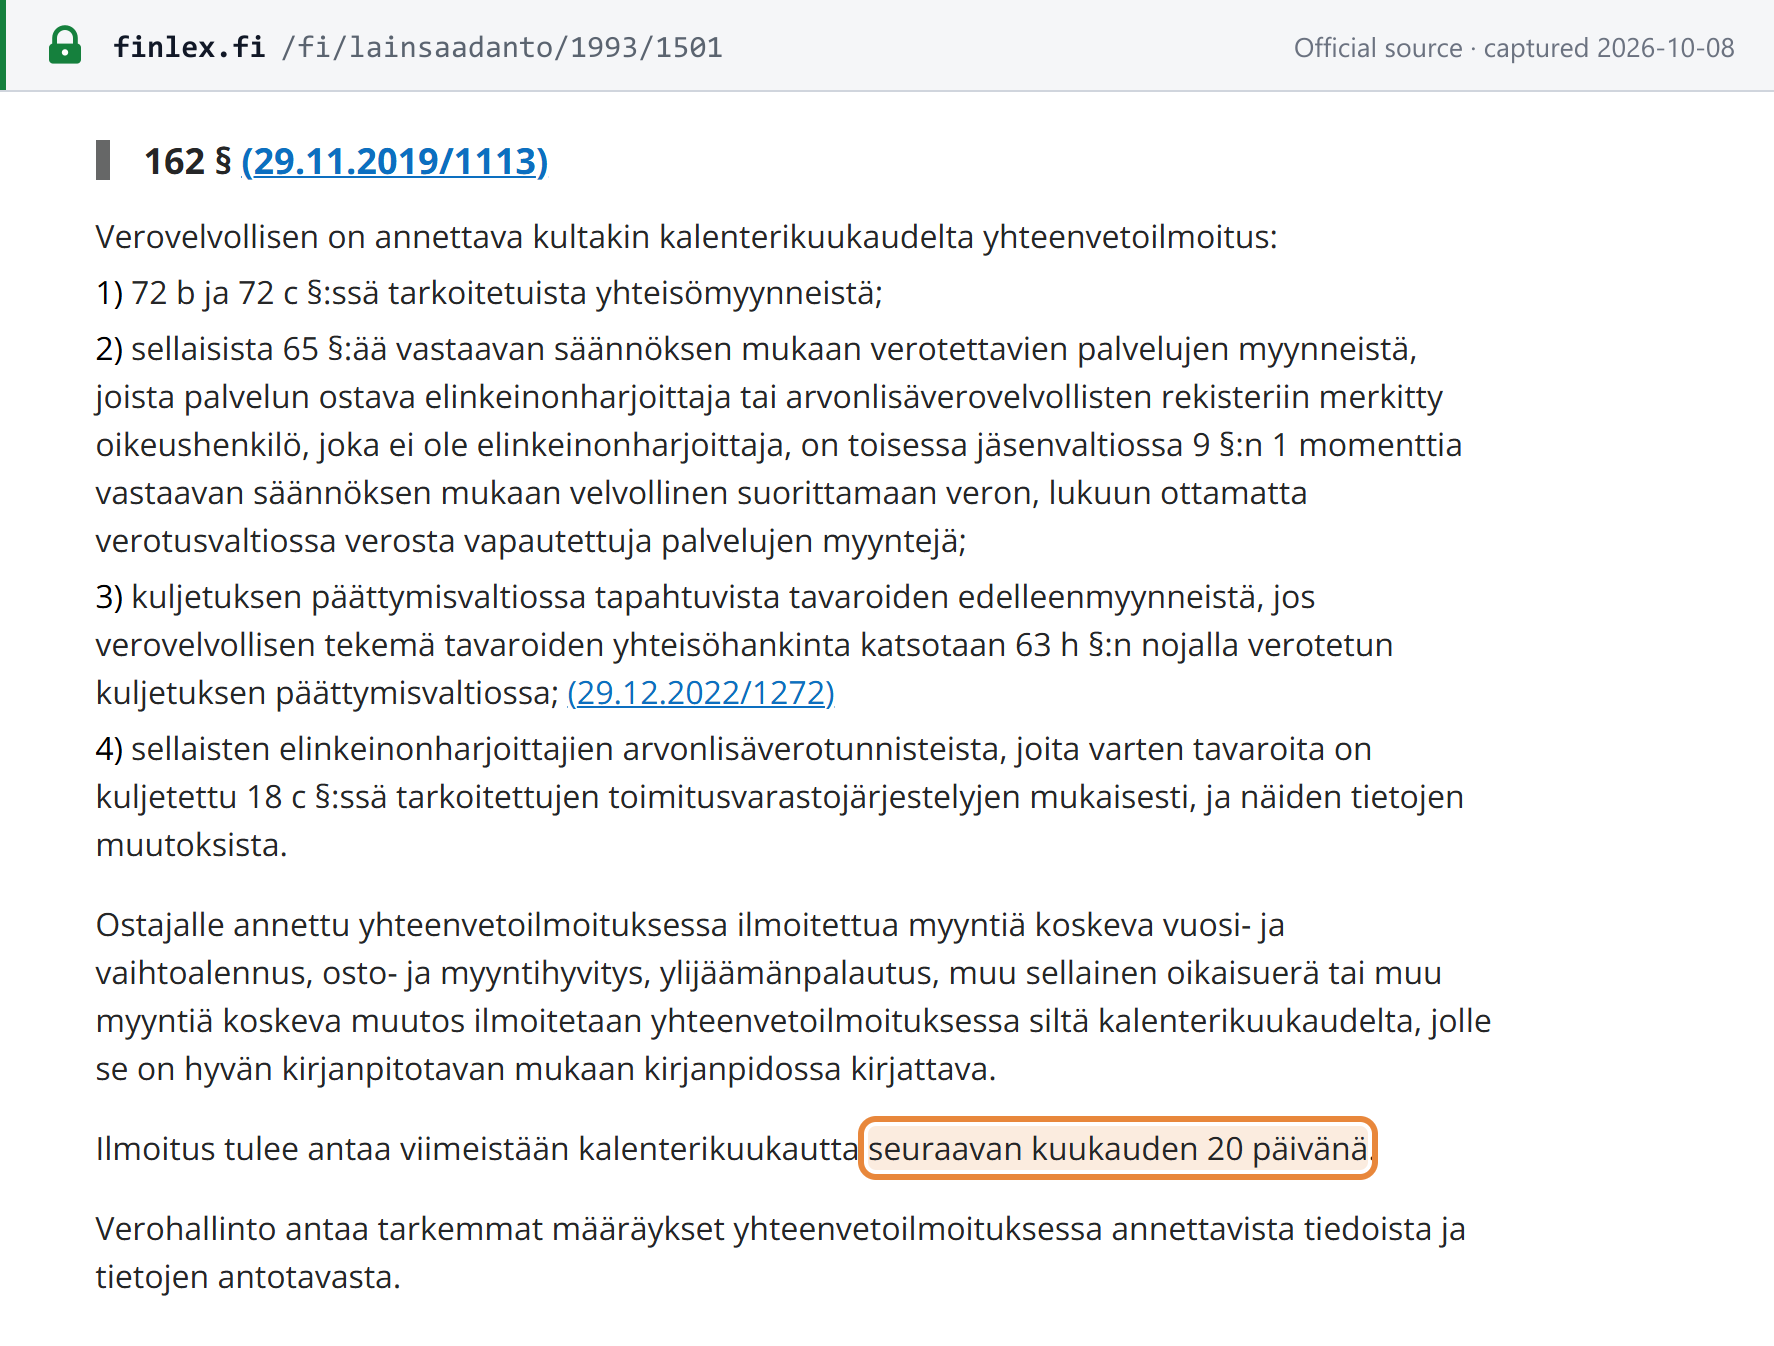
Finland's EU sales listing is monthly only — there is no quarterly option — and is due by the 20th of the following month, about three weeks before the VAT return for the same month. A Saturday, Sunday or public-holiday deadline moves to the next business day: the November 2026 statement is due Monday 21 December.
Source
Arvonlisäverolaki (1501/1993) — 162 § 1 and 3 mom Finlex (oikeusministeriö)
See the source text
“Ilmoitus tulee antaa viimeistään kalenterikuukautta seuraavan kuukauden 20 päivänä.”
Screenshot of Finlex (oikeusministeriö) showing the Yhteenvetoilmoitus — EU sales recapitulative statement deadline Open full size Captured from Finlex (oikeusministeriö) on 2026-10-08
OSS return — Union and non-Union schemes

Arvonlisävero (ALV / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Businesses using Finland as their member state of identification for the Union OSS (intra-EU distance sales of goods and B2C services) or the non-Union OSS (B2C services by non-EU businesses)
Notes
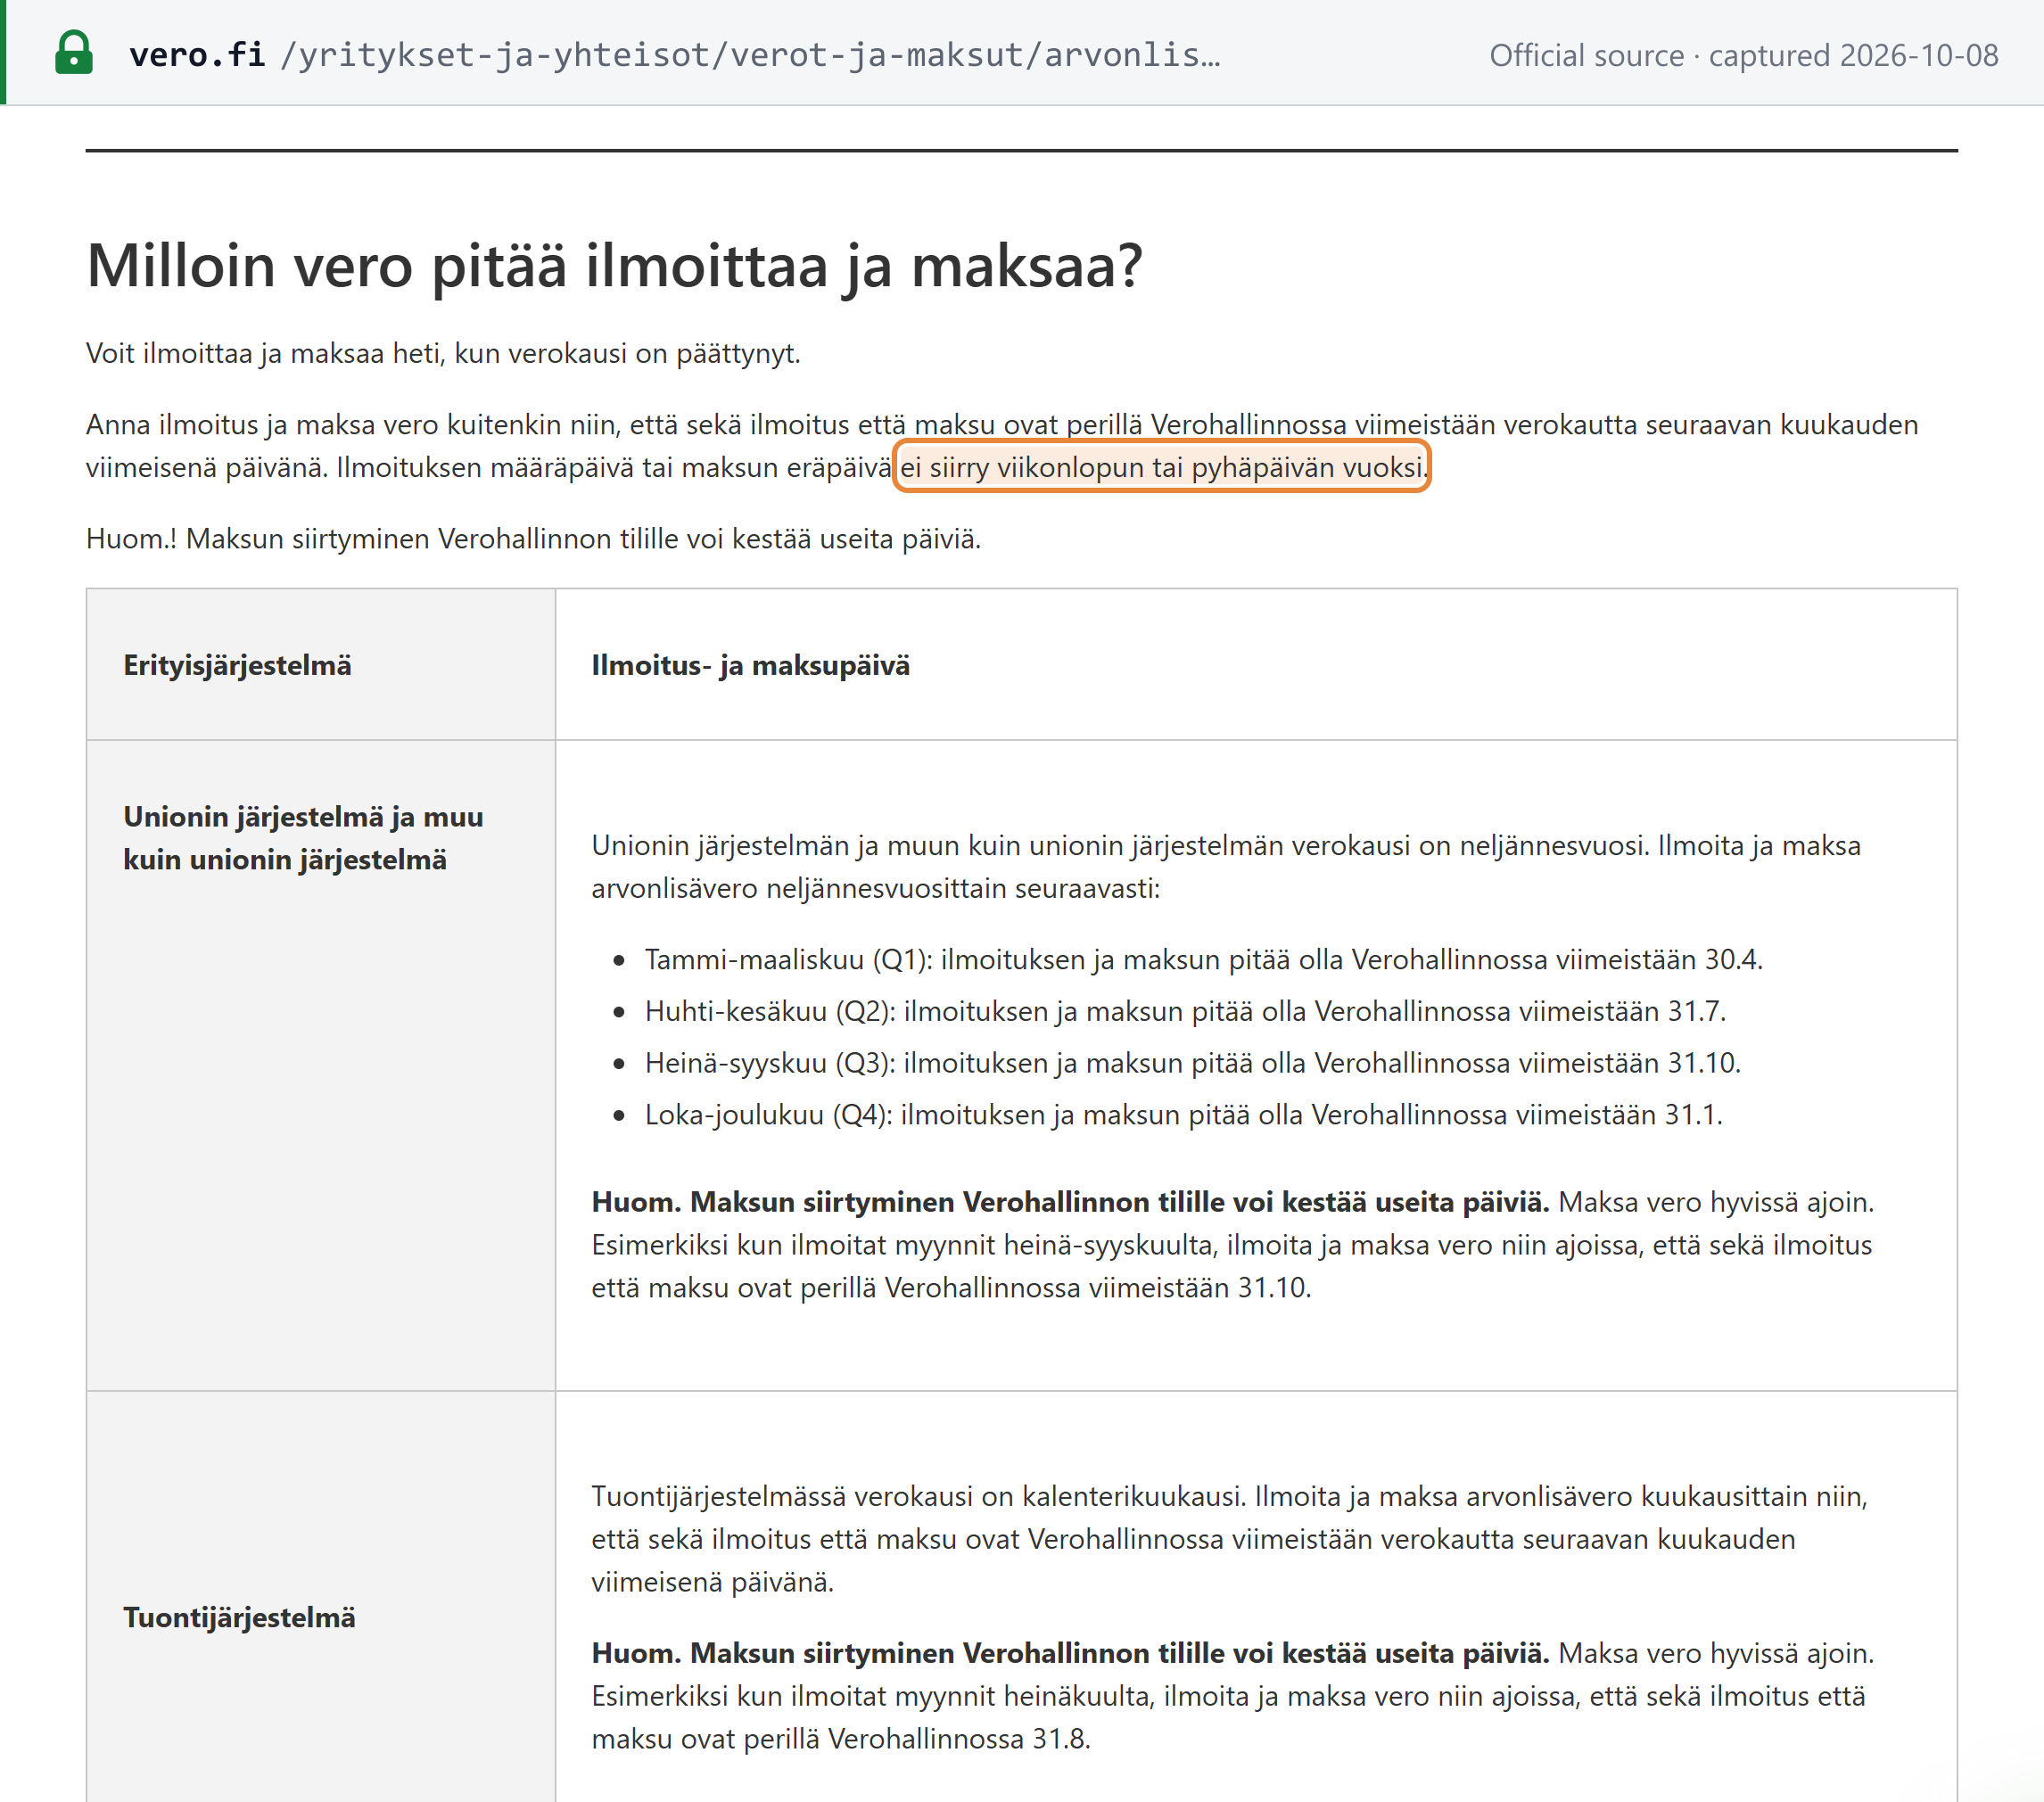
OSS returns are quarterly and both the return and the payment must reach the Tax Administration by the last day of the month after the quarter. File a nil return for a quarter with no sales. The date does not move for weekends or holidays — the third quarter of 2026 is due on Saturday 31 October itself, so in practice file by the last working day before it.
Source
Verohallinto — Arvonlisäveron erityisjärjestelmän ilmoitus- ja maksuohjeet; Arvonlisäverolaki (1501/1993) 133 h § and 133 o § Verohallinto
See the source text
“Ilmoituksen määräpäivä tai maksun eräpäivä ei siirry viikonlopun tai pyhäpäivän vuoksi.”
Screenshot of Verohallinto showing the OSS return — Union and non-Union schemes deadline Open full size Captured from Verohallinto on 2026-10-08

IOSS return — import scheme

Arvonlisävero (ALV / VAT) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-08
Who files
Businesses or intermediaries using Finland as their member state of identification for the Import OSS (B2C distance sales of imported goods in consignments up to EUR 150)
Notes
IOSS returns are monthly; the return and the payment must both arrive by the last day of the following month, and the deadline is not moved for weekends or holidays.
Source
Verohallinto — Arvonlisäveron erityisjärjestelmän ilmoitus- ja maksuohjeet; Arvonlisäverolaki (1501/1993) 133 w § 3 mom Verohallinto
See the source text
“Ilmoita ja maksa arvonlisävero kuukausittain niin, että sekä ilmoitus että maksu ovat Verohallinnossa viimeistään verokautta seuraavan kuukauden viimeisenä päivänä.”
Screenshot of Verohallinto showing the IOSS return — import scheme deadline Open full size Captured from Verohallinto on 2026-10-08

Neljänneskalenterivuosi-ilmoitus — EU cross-border SME scheme quarterly report

Arvonlisävero (ALV / VAT) — EU SME scheme · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Finland-established businesses registered in the EU cross-border SME scheme (EX identifier), using the VAT exemption in other member states
Notes
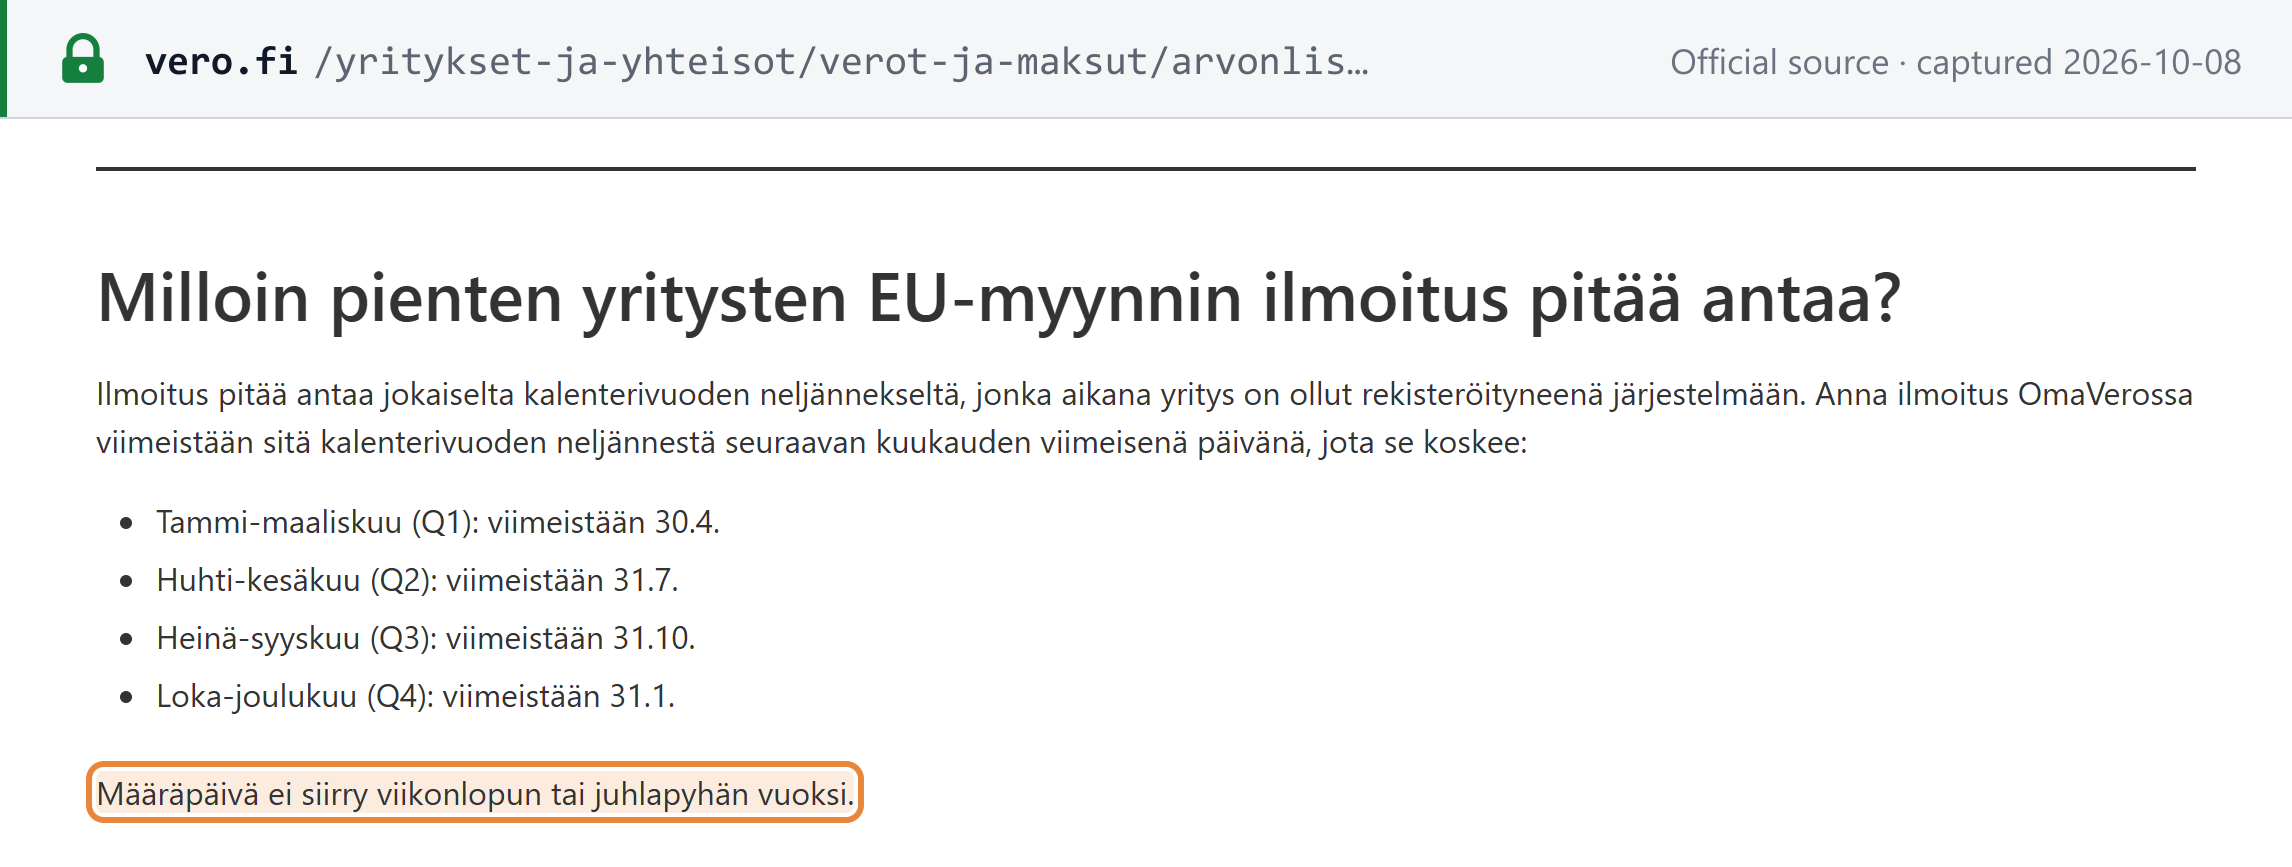
Small businesses using the EU-wide exemption report their Finnish turnover and their turnover in each other member state every quarter in MyTax, by the last day of the following month — reporting zero for a quarter with no sales. The deadline does not move for weekends or holidays.
Source
Verohallinto — Näin ilmoitat pienten yritysten EU-myynnit; Arvonlisäverolaki (1501/1993) 149 e § 5 mom Verohallinto
See the source text
“Määräpäivä ei siirry viikonlopun tai juhlapyhän vuoksi.”
Screenshot of Verohallinto showing the Neljänneskalenterivuosi-ilmoitus — EU cross-border SME scheme quarterly report deadline Open full size Captured from Verohallinto on 2026-10-08

Valmisteveroilmoitus — excise duty return (regular taxpayers)

Valmistevero (excise duty) · Monthly · return filing

12th of the 2nd month after the month ends Verified 2026-10-08
Who files
Regular excise taxpayers — authorised warehousekeepers, registered consignees and tax representatives — for alcohol, tobacco, soft drinks, beverage packaging, electricity and fuels
Notes
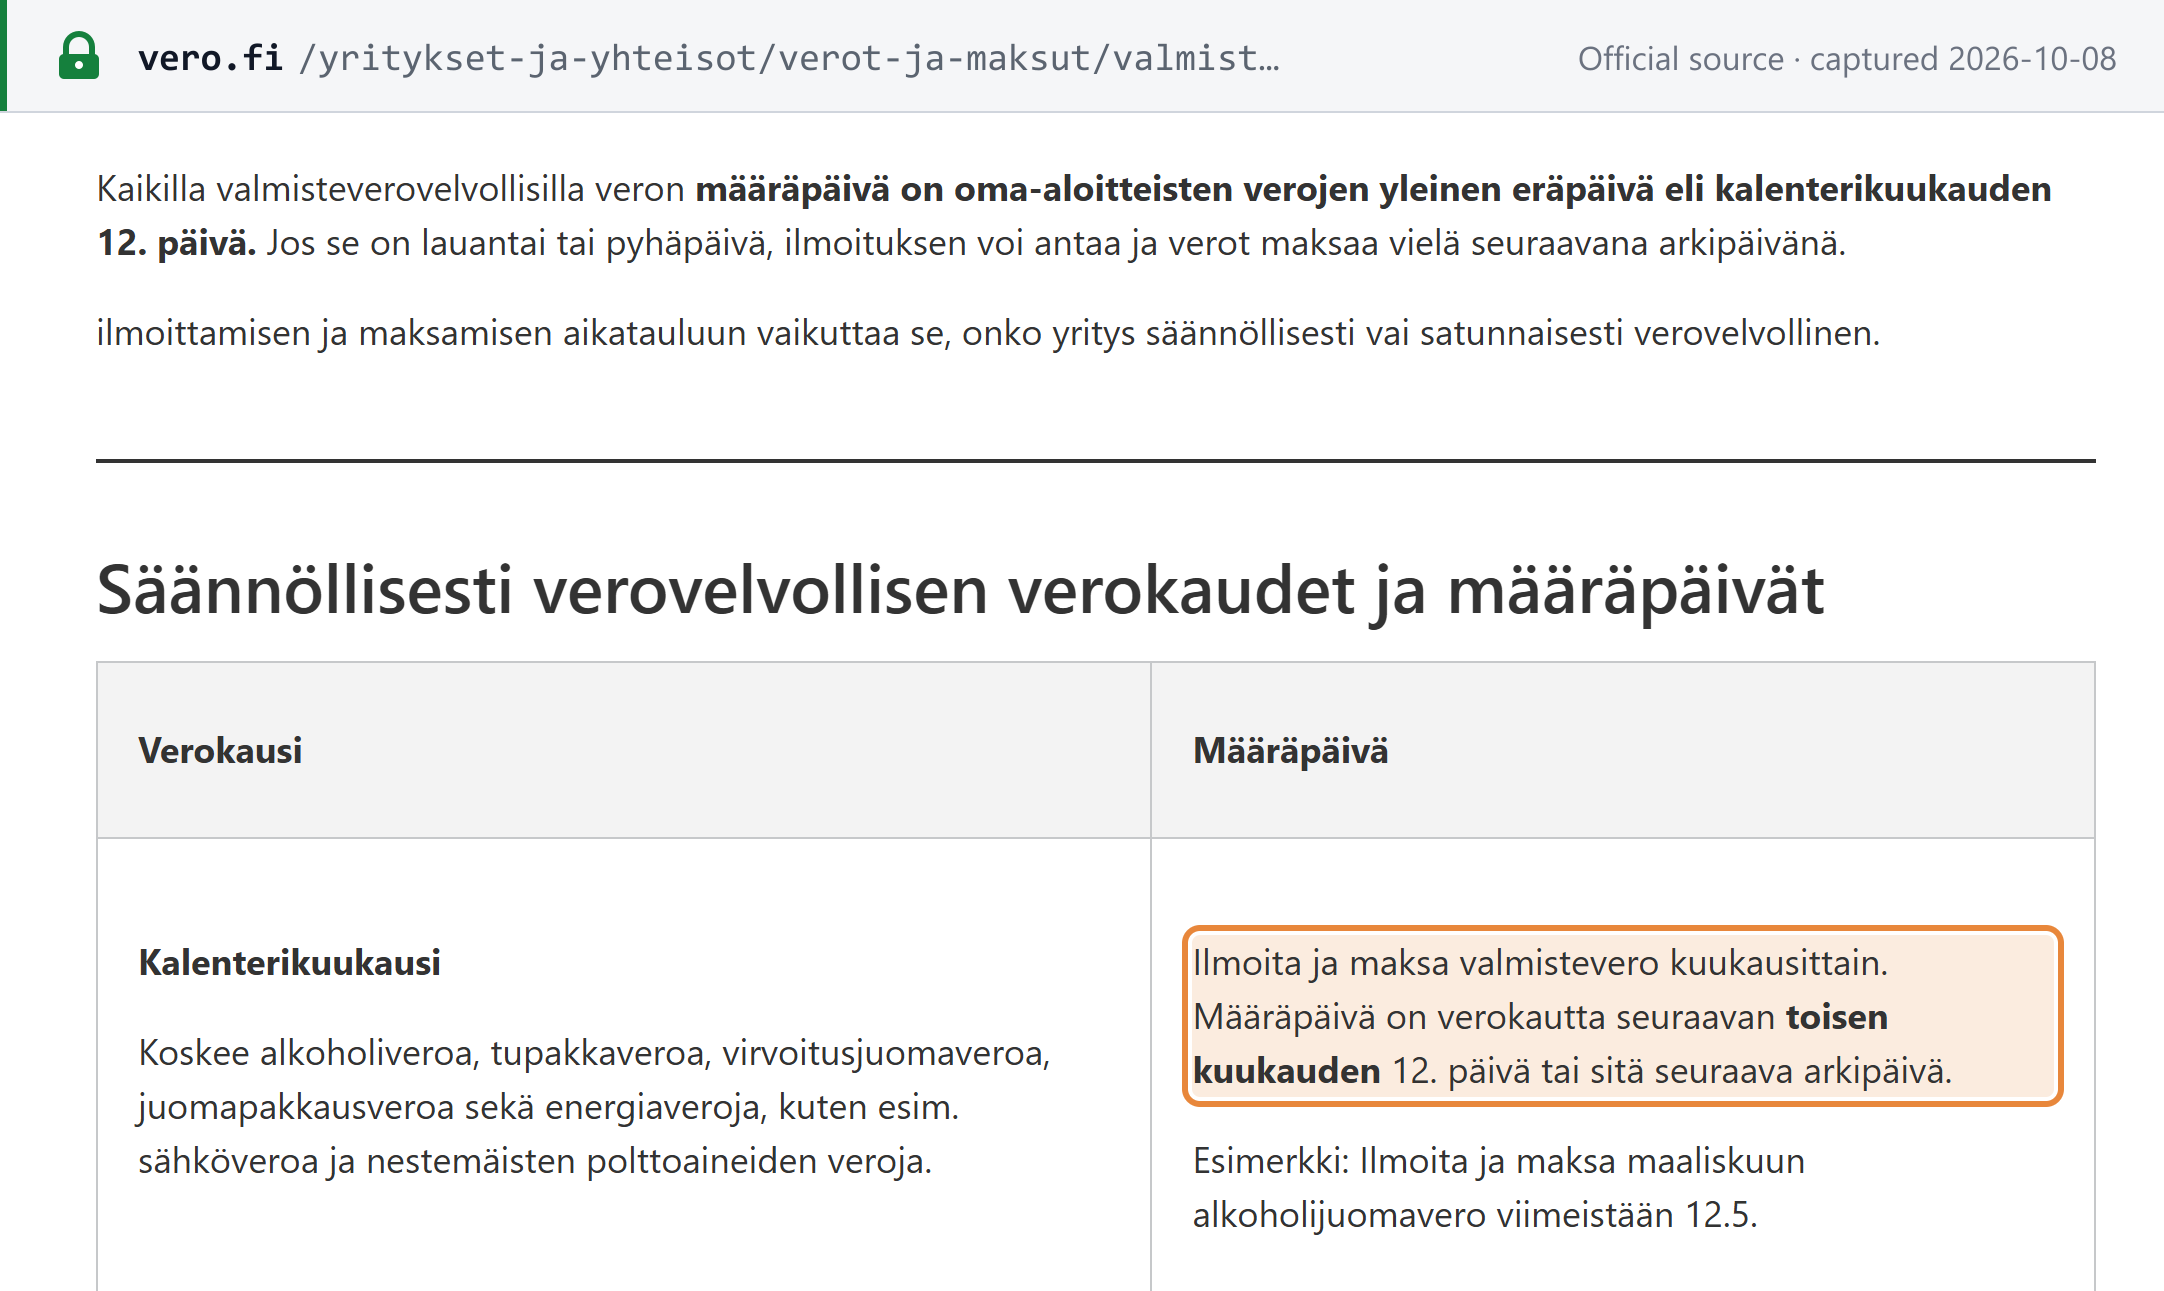
Regular excise taxpayers file and pay monthly, on the same 12th-of-the-second-month timetable as VAT. Occasional excise taxpayers file only for months with excisable activity, a month sooner — by the 12th of the following month. Small electricity and biogas producers and small peat users report once a year, by 12 February.
Source
Verohallinto — Valmisteverotuksen verokaudet ja määräpäivät; Laki oma-aloitteisten verojen verotusmenettelystä (768/2016) 17 § 2 mom Verohallinto
See the source text
“Ilmoita ja maksa valmistevero kuukausittain. Määräpäivä on verokautta seuraavan toisen kuukauden 12. päivä tai sitä seuraava arkipäivä.”
Screenshot of Verohallinto showing the Valmisteveroilmoitus — excise duty return (regular taxpayers) deadline Open full size Captured from Verohallinto on 2026-10-08

Jäteveroilmoitus — waste tax return

Jätevero (waste tax) · Quarterly · return filing

12th of the 2nd month after the quarter ends Verified 2026-10-08
Who files
Operators of landfill sites liable to waste tax
Notes
Landfill operators file and pay waste tax every three months, by the 12th of the second month after the quarter — the January–March tax by 12 May — moved to the next weekday when the 12th is a weekend or holiday.
Source
Verohallinto — Valmisteverotuksen verokaudet ja määräpäivät; Laki oma-aloitteisten verojen verotusmenettelystä (768/2016) 11 § 5 mom Verohallinto
See the source text
“Ilmoita ja maksa jätevero kolmen kuukauden välein. Määräpäivä on verokautta seuraavan toisen kuukauden 12. päivä tai sitä seuraava arkipäivä.”
Captured from Verohallinto on 2026-10-08

VAT registration — turnover over EUR 20,000

Arvonlisävero (ALV / VAT) · One-off · registration

no later than the day of turnover exceeding the EUR 20,000 registration threshold Verified 2026-10-08
Who files
Businesses whose turnover in the current calendar year exceeds EUR 20,000, or whose turnover in the preceding calendar year exceeded it
Notes
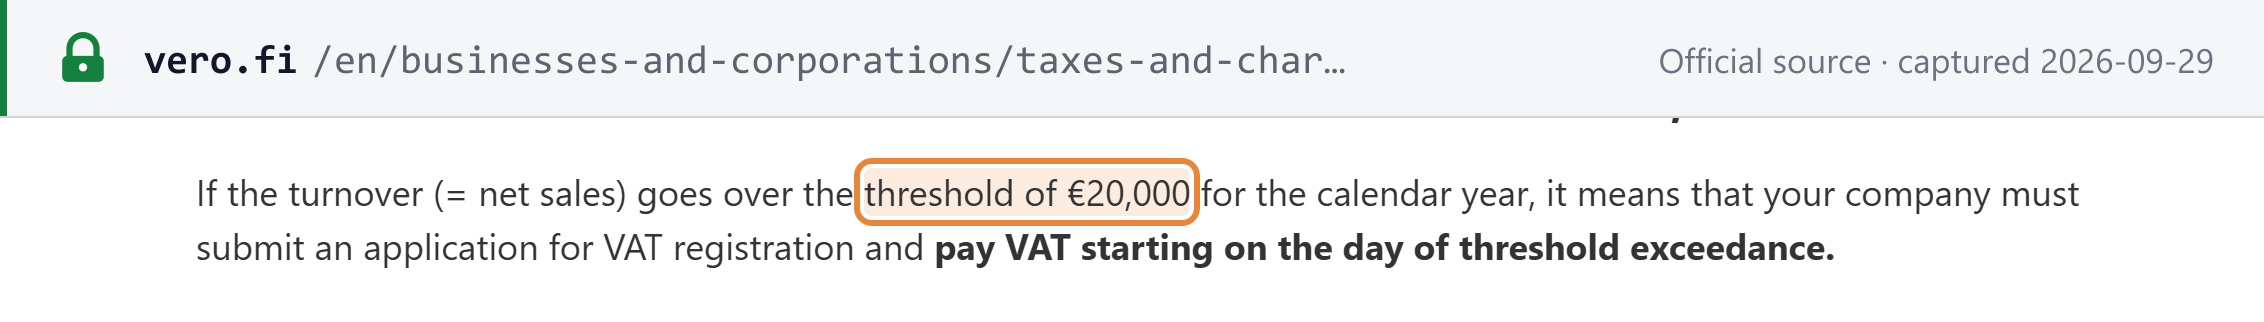
There is no grace period: VAT liability starts on the day turnover for the calendar year passes EUR 20,000, and the Tax Administration registers you from that day, so apply in advance. A business whose turnover passed EUR 20,000 in the previous calendar year stays liable from 1 January. A business starting VAT-liable activity files its start-up notification before it begins trading, and changes to registered details or the end of VAT-liable activity must be notified without delay.
Source
Verohallinto — How to register for VAT; Arvonlisäverolaki (1501/1993) 3 § and 173 § 2 mom Verohallinto
See the source text
“pay VAT starting on the day of threshold exceedance.”
Screenshot of Verohallinto showing the VAT registration — turnover over EUR 20,000 deadline Open full size Captured from Verohallinto on 2026-09-29

EU SME scheme — notice of exceeding the EUR 100,000 Union threshold

Arvonlisävero (ALV / VAT) — EU SME scheme · One-off · registration

within 15 business days of EU-wide turnover exceeding EUR 100,000 Verified 2026-10-08
Who files
Finland-established businesses in the EU cross-border SME scheme whose EU-wide turnover passes EUR 100,000
Notes
A business that passes EUR 100,000 of EU-wide turnover leaves the cross-border exemption and must tell the Tax Administration within 15 working days.
Source
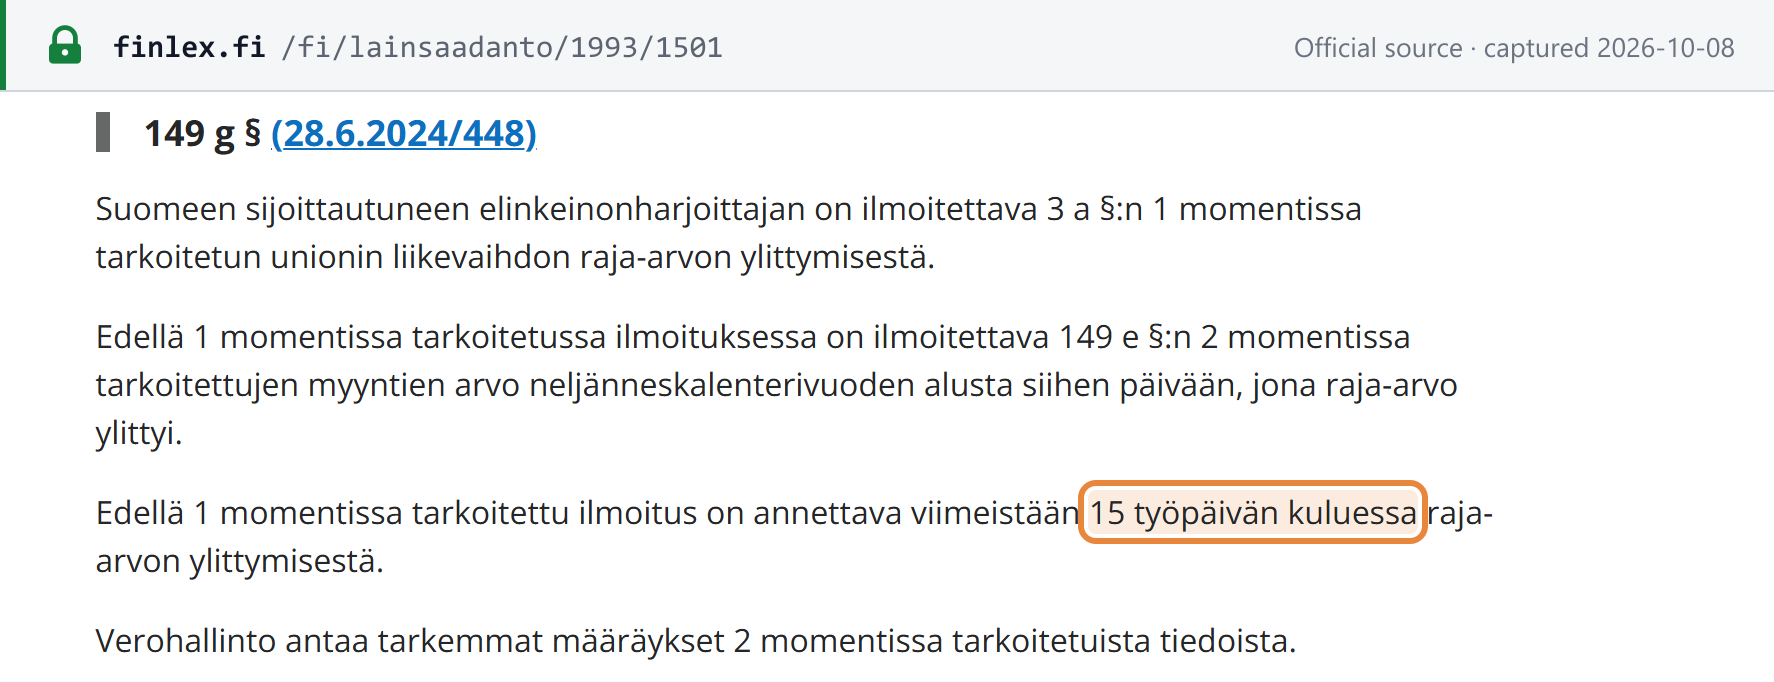
Arvonlisäverolaki (1501/1993) — 149 g § 3 mom Finlex (oikeusministeriö)
See the source text
“Edellä 1 momentissa tarkoitettu ilmoitus on annettava viimeistään 15 työpäivän kuluessa raja-arvon ylittymisestä.”
Screenshot of Finlex (oikeusministeriö) showing the EU SME scheme — notice of exceeding the EUR 100,000 Union threshold deadline Open full size Captured from Finlex (oikeusministeriö) on 2026-10-08
Finnish VAT is filed and paid on the 12th of the second month after the tax period — the September return is due 12 November — and the 12th moves to the next banking day when it falls on a weekend or public holiday. Monthly filing is the default; businesses with turnover up to EUR 100,000 can choose quarterly periods and those up to EUR 30,000 a calendar year. The EU sales listing comes earlier, on the 20th of the following month. OSS, IOSS and EU small-business scheme reports are due at the end of the following month and, as the Tax Administration states expressly, do not move for weekends or holidays. Importers on the VAT register report import VAT on the ordinary VAT return.

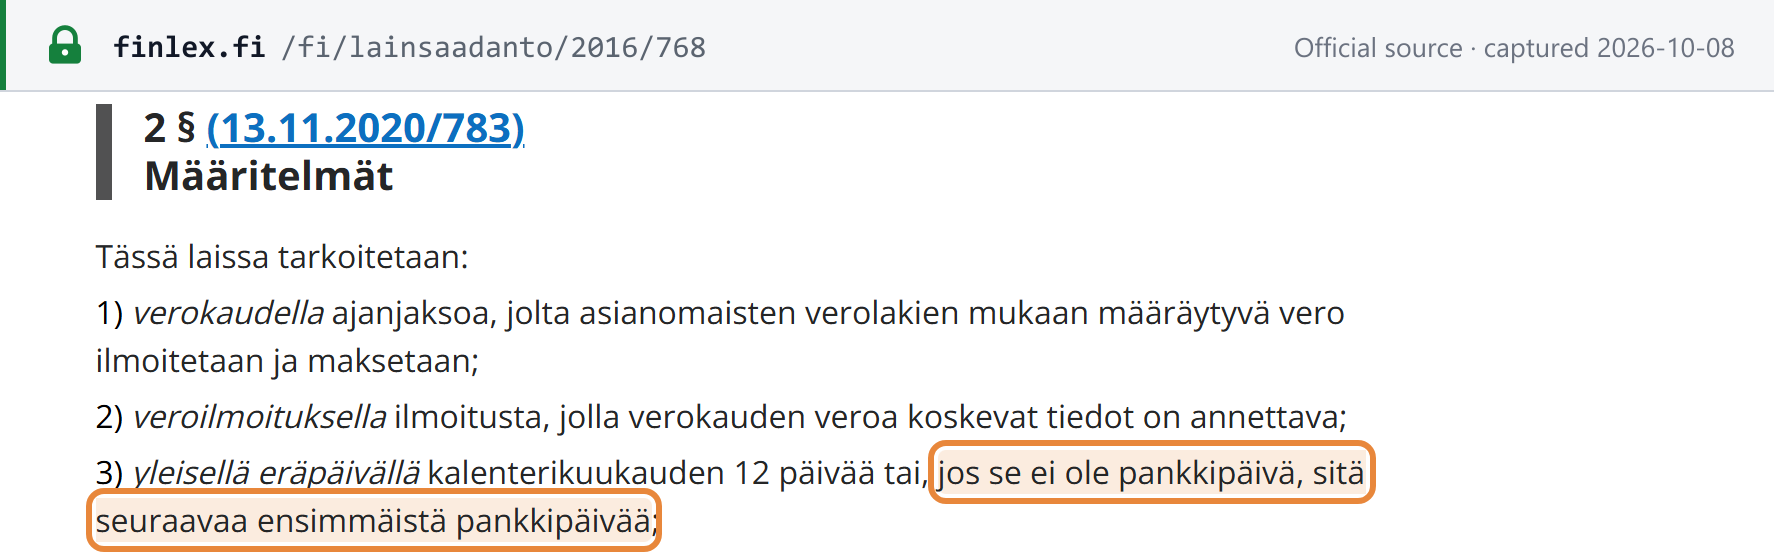
“yleisellä eräpäivällä kalenterikuukauden 12 päivää tai, jos se ei ole pankkipäivä, sitä seuraavaa ensimmäistä pankkipäivää;”
Screenshot of the official source stating the rule that governs Finland's deadlines
Laki oma-aloitteisten verojen verotusmenettelystä (768/2016) — 2 § 3 kohta — Finlex (oikeusministeriö), captured 2026-10-08

What this calendar does not list

  • Not applicable E-invoicing / e-reporting cycle — Finland has no e-invoicing clearance or reporting mandate. Act 241/2019 gives contracting authorities and businesses a right to receive an e-invoice on request, which is triggered per invoice and fixes no filing cycle. The EU adopted digital reporting under VAT in the Digital Age in 2025, but Finland had not legislated any domestic reporting requirement as of 2026-10-08.
  • Not yet covered Periodic return — Not yet modelled: insurance premium tax (vakuutusmaksuvero), due on the 12th of the month after the month it concerns (OVML 17 § 1; shown on each 12th of the Tax Administration's calendar); lottery tax (arpajaisvero), filed monthly on the VAT timetable (OVML 17 § 2); pharmacy tax (apteekkivero), on a calendar-year period due at the end of February; and mining mineral tax (kaivosmineraalivero), due 12 March. Identified in research and verification on 2026-10-08.

About this calendar

Which Finland tax deadlines does this calendar cover?

11 recurring indirect-tax obligations — Arvonlisävero (ALV / VAT), Valmistevero (excise duty) and Jätevero (waste tax) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-08). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.