Greece compliance calendar

15 recurring Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Greece rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Report / listing Return filing Payment Law change takes effect

Dates already include the weekend and public-holiday shift where Greece applies one — 8 of 15 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Δήλωση ΦΠΑ (F2 / έντυπο 050) — monthly

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) · Monthly · return filing

last business day of the month after the month ends Verified 2026-10-08
Who files
VAT-registered businesses keeping double-entry books (and the State); single-entry businesses that started trading on or after 1 January 2024, for their first 24 months; and older single-entry businesses that opted into monthly filing. Businesses that have declared dormancy or suspension file none
Notes
Double-entry businesses file every calendar month, and so — since decision Α.1049/2025 — do single-entry businesses for their first two years of trading. The return and the payment are both due by the last working day of the following month. When that month ends on a weekend the deadline comes forward to the Friday: the September 2026 return is due Friday 30 October because the 31st is a Saturday. A payable balance of EUR 30 or less is carried to the next month instead of paid. Classify the purchase invoices you received in myDATA before you file.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 43 παρ. 1 και 4, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 (εγκ. Ε.2019/2026) ΑΑΔΕ
See the source text
“Οι δηλώσεις ΦΠΑ των παρ. 1 και 2 υποβάλλονται μέχρι την τελευταία εργάσιμη για τις δημόσιες υπηρεσίες ημέρα του μήνα που ακολουθεί τη λήξη της φορολογικής περιόδου.”
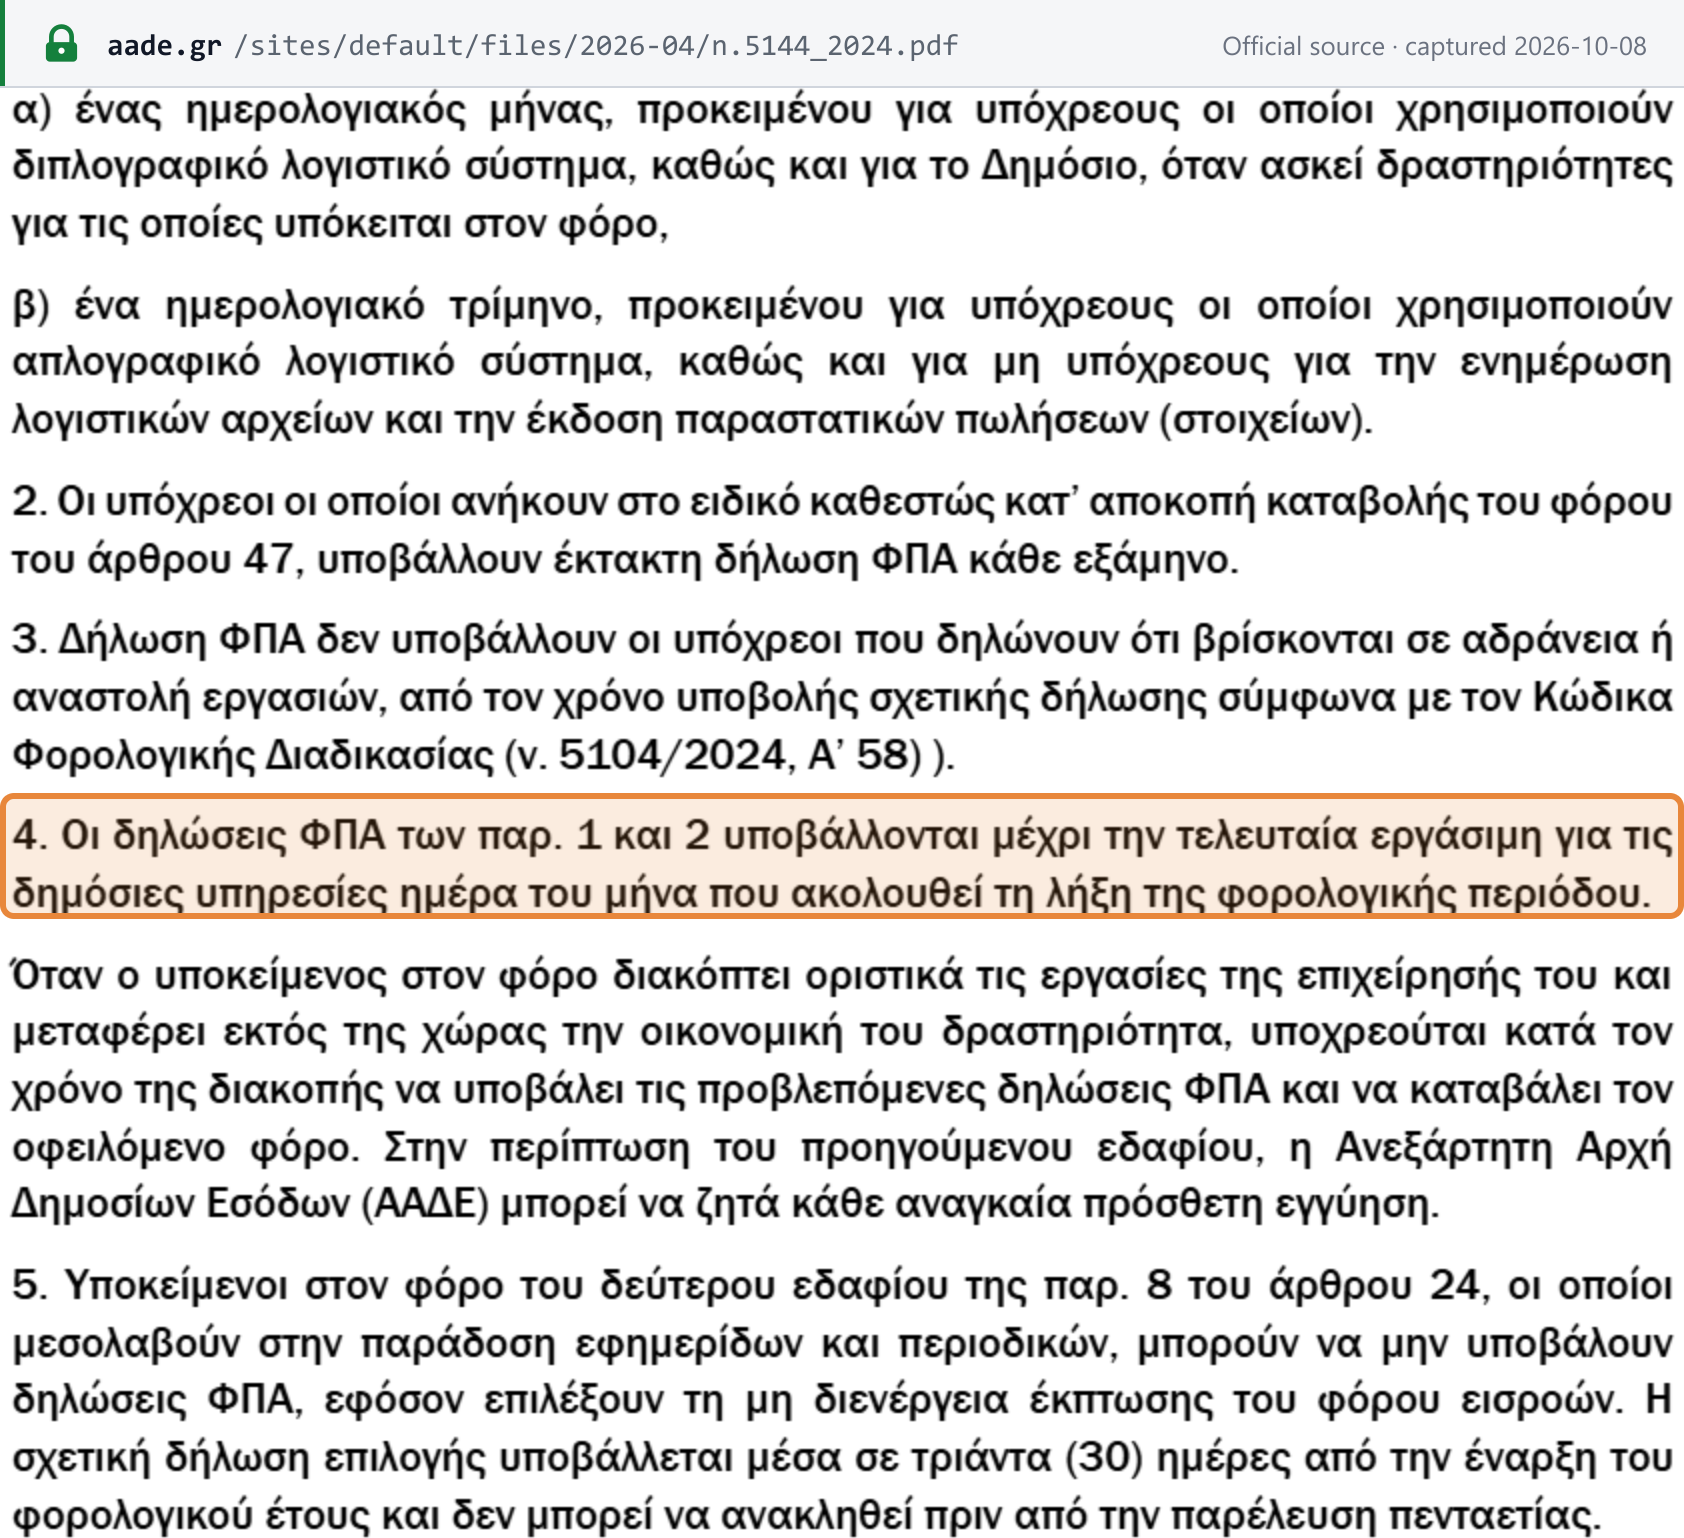
Screenshot of ΑΑΔΕ showing the Δήλωση ΦΠΑ (F2 / έντυπο 050) — monthly deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Δήλωση ΦΠΑ (F2 / έντυπο 050) — quarterly

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) · Quarterly · return filing

last business day of the month after the quarter ends Verified 2026-10-08
Who files
Single-entry businesses that began trading before 1 January 2024, or have completed 24 months of monthly filing, and have not opted into monthly returns
Notes
Quarterly filing is now the exception rather than the single-entry default: it is open to single-entry businesses that started trading before 2024, or that have completed their first two years of monthly returns. Each quarter is due, with its payment, by the last working day of the month after it ends — the first quarter of 2027 by Thursday 29 April, a day before Good Friday. A business that registers as dormant files nothing until it resumes.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 43 παρ. 1 και 4, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 (εγκ. Ε.2019/2026) ΑΑΔΕ
See the source text
“Οι δηλώσεις ΦΠΑ των παρ. 1 και 2 υποβάλλονται μέχρι την τελευταία εργάσιμη για τις δημόσιες υπηρεσίες ημέρα του μήνα που ακολουθεί τη λήξη της φορολογικής περιόδου.”
Screenshot of ΑΑΔΕ showing the Δήλωση ΦΠΑ (F2 / έντυπο 050) — quarterly deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Έκτακτη δήλωση ΦΠΑ — six-monthly return under the flat-rate scheme (άρθρο 47)

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) · Bi-annually · return filing

last business day of the month after the half-year ends Verified 2026-10-08
Who files
Sole traders, civil partnerships and co-ownerships admitted to the article 47 flat-rate payment scheme — chiefly coastal fishing boats up to 12 metres and sponge fishers
Notes
Businesses on the flat-rate scheme pay a fixed amount of VAT rather than accounting for it transaction by transaction, and file a special return every six months, due by the last working day of the month after each half-year ends.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 43 παρ. 2 και 4, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 ΑΑΔΕ
See the source text
“Οι υπόχρεοι οι οποίοι ανήκουν στο ειδικό καθεστώς κατ’ αποκοπή καταβολής του φόρου του άρθρου 47, υποβάλλουν έκτακτη δήλωση ΦΠΑ κάθε εξάμηνο.”
Screenshot of ΑΑΔΕ showing the Έκτακτη δήλωση ΦΠΑ — six-monthly return under the flat-rate scheme (άρθρο 47) deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Δεύτερη δόση ΦΠΑ — optional second instalment of VAT due

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) · Monthly · payment

last business day of the 2nd month after the month ends Verified 2026-10-08
Who files
Filers who submitted their F2 on time with more than EUR 100 payable and chose to pay in two equal interest-free instalments
Notes
Only relevant if you take the option. A return filed on time showing more than EUR 100 due can be paid in two equal halves without interest: the first by the normal deadline, the second by the last working day of the month after. For the September 2026 return that means the second half by Monday 30 November 2026. Quarterly filers can use the same option; their second half falls a month after the quarterly deadline.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 43 παρ. 6, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 ΑΑΔΕ
See the source text
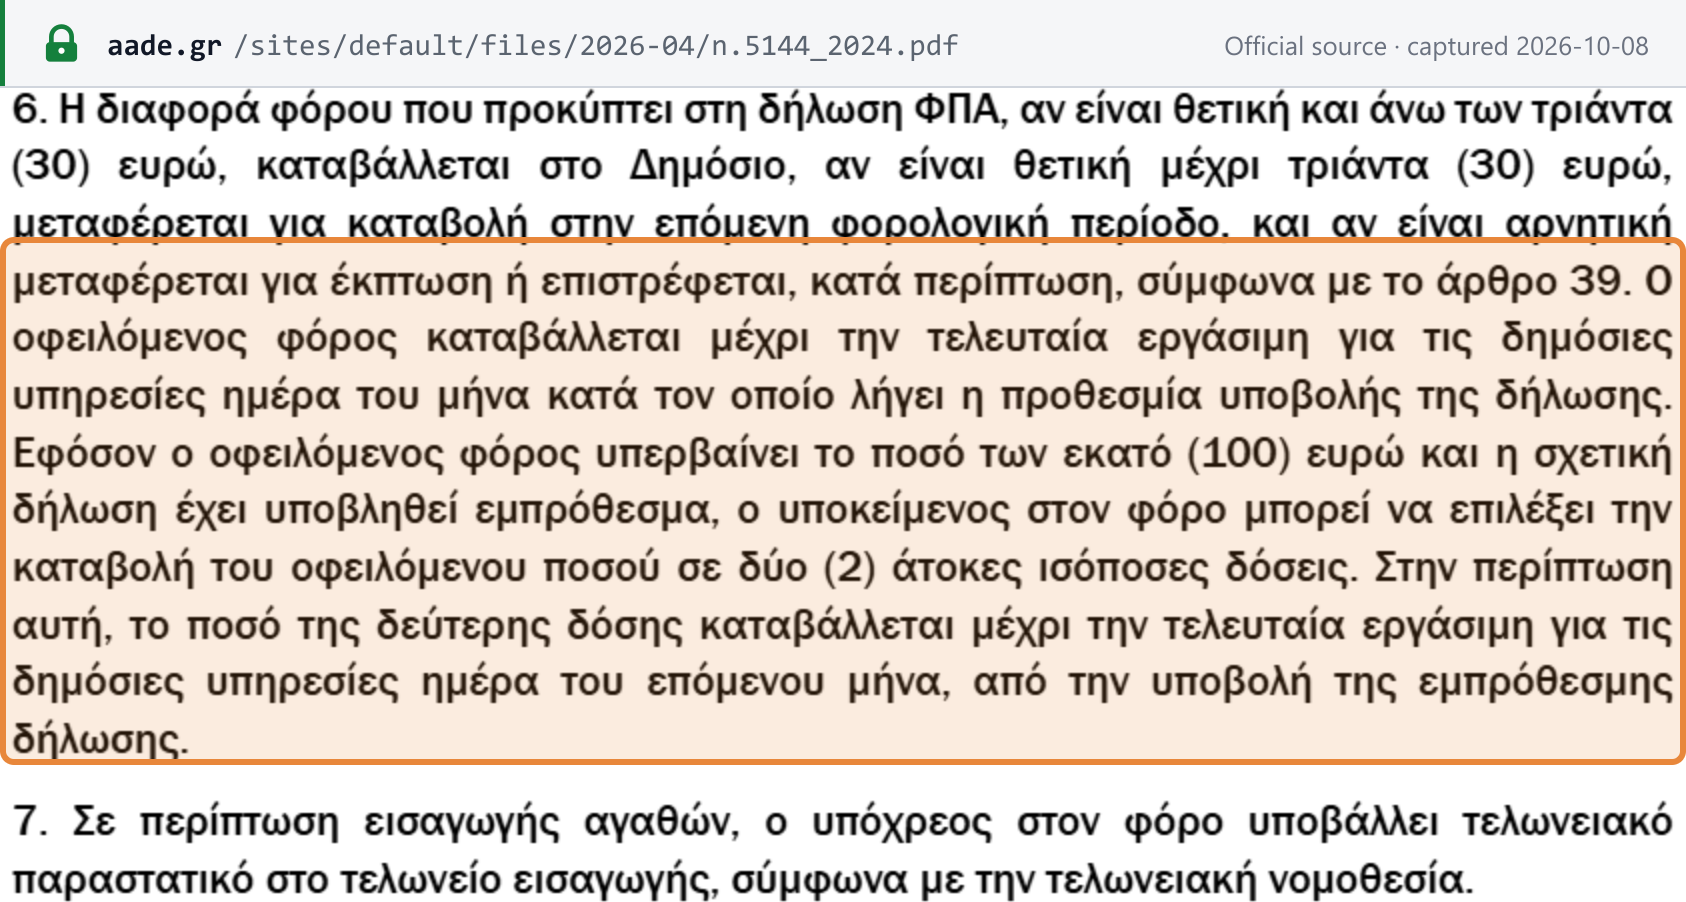
“Στην περίπτωση αυτή, το ποσό της δεύτερης δόσης καταβάλλεται μέχρι την τελευταία εργάσιμη για τις δημόσιες υπηρεσίες ημέρα του επόμενου μήνα, από την υποβολή της εμπρόθεσμης δήλωσης.”
Screenshot of ΑΑΔΕ showing the Δεύτερη δόση ΦΠΑ — optional second instalment of VAT due deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Διακανονισμός εκπτώσεων (άρθρο 38) — annual adjustment of input-VAT deductions

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) · Annually · return filing

30th April each year Verified 2026-10-08
Who files
Businesses with mixed taxable and exempt activity, or other deductions computed provisionally during the year, on a calendar tax year
Notes
Greece has no annual VAT return. What it does have is a year-end settlement of the input VAT you deducted provisionally during the year, which must be included in a periodic return filed by the last working day of April. For 2026 that is Thursday 29 April 2027, a day earlier than usual because 30 April is Good Friday.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 38 παρ. 1, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 ΑΑΔΕ
See the source text
“Οι διακανονισμοί που αφορούν σε εκπτώσεις που διενεργήθηκαν σε ένα φορολογικό έτος περιλαμβάνονται σε δήλωση ΦΠΑ που υποβάλλεται το αργότερο μέχρι την τελευταία εργάσιμη για τις δημόσιες υπηρεσίες ημέρα του τέταρτου μήνα από το τέλος του φορολογικού έτους.”
Captured from ΑΑΔΕ on 2026-10-08

Ανακεφαλαιωτικός πίνακας Φ4 / Φ5 (VIES) — recapitulative statements

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) · Monthly · report / listing

26th of the month after the month ends Verified 2026-10-08
Who files
Businesses with intra-EU supplies of goods, call-off stock transfers or B2B services (Φ4), or intra-EU acquisitions and services received from EU suppliers (Φ5), in the month
Notes
Every month, with no quarterly option, by the 26th of the following month. Unlike most EU listings Greece also wants the purchase side: Φ5 reports acquisitions and services bought from other member states. Months with nothing to report need no statement. When the 26th is a weekend or holiday the deadline moves forward — November 2026 is due Monday 28 December, because the 26th is both a Saturday and the second day of Christmas.
Source
Απόφαση Α.1222/2020 (ΦΕΚ Β΄ 4274/01.10.2020) — άρθρο 2 ΑΑΔΕ
See the source text
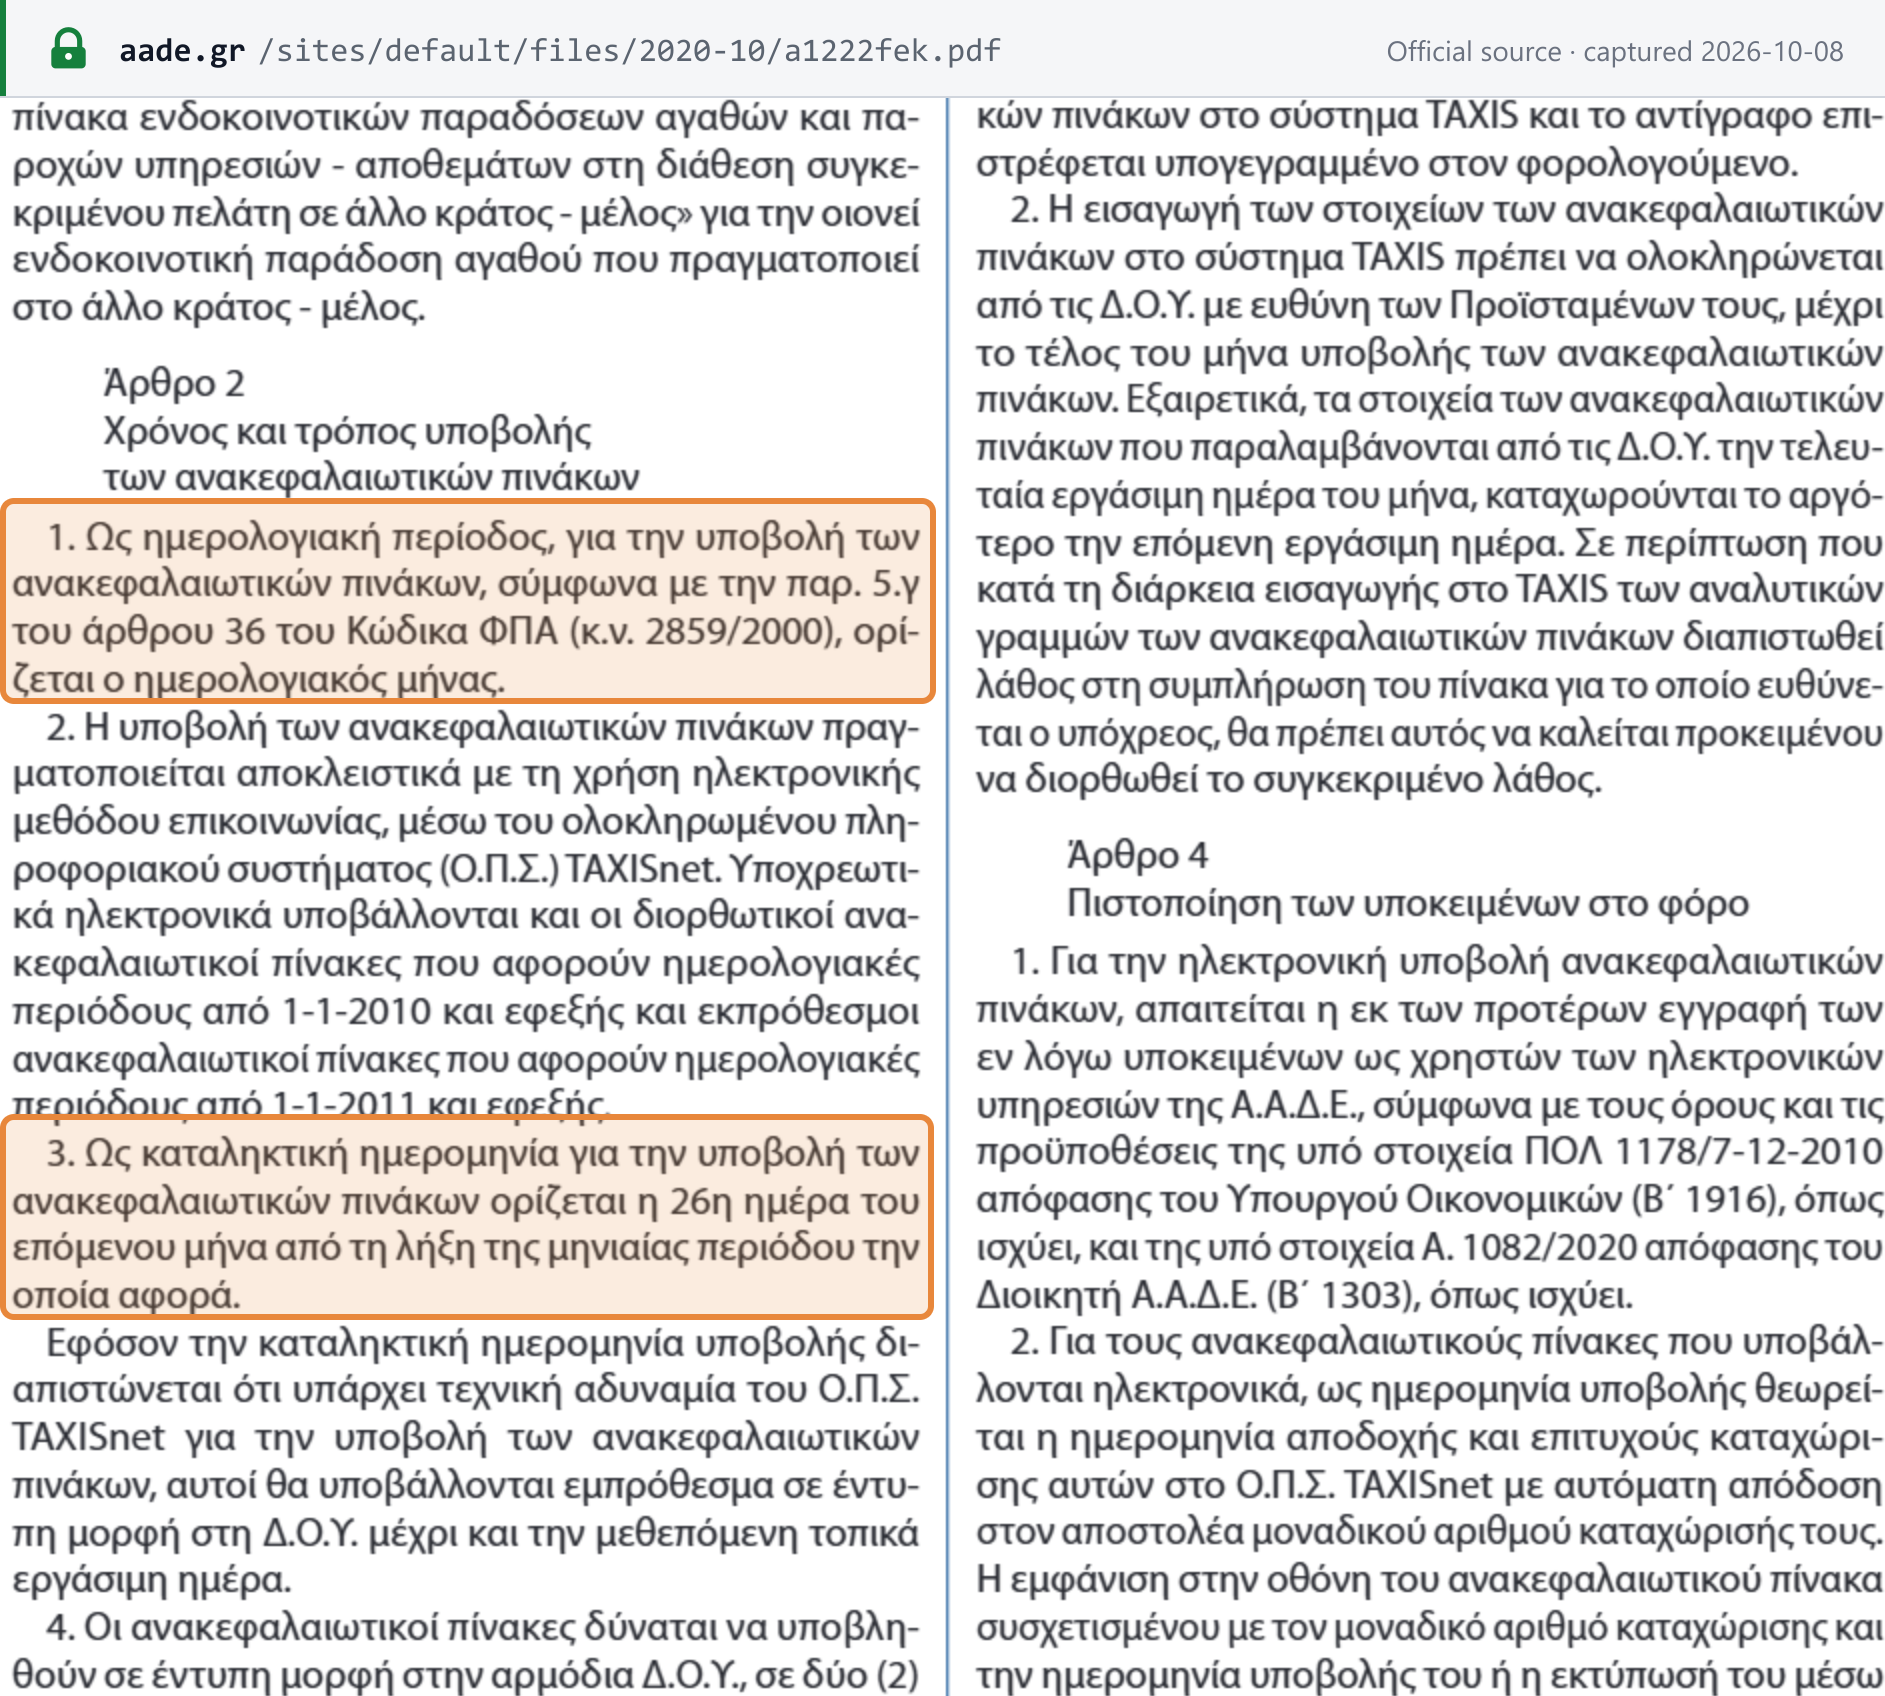
“3. Ως καταληκτική ημερομηνία για την υποβολή των ανακεφαλαιωτικών πινάκων ορίζεται η 26η ημέρα του επόμενου μήνα από τη λήξη της μηνιαίας περιόδου την οποία αφορά.”
Screenshot of ΑΑΔΕ showing the Ανακεφαλαιωτικός πίνακας Φ4 / Φ5 (VIES) — recapitulative statements deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
myDATA — expense classification and recipient-side transmissions

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — ηλεκτρονικά βιβλία (myDATA) · Monthly · report / listing

last business day of the month after the month ends Verified 2026-10-08
Who files
Every business keeping books in Greece: the deadline for classifying received invoices and transmitting recipient-side data follows its own F2 period — monthly for most businesses, quarterly for those still filing quarterly
Notes
Sales invoices reach myDATA in real time, but the buyer's side has a deadline: classifying the purchase invoices you received, and transmitting any the issuer failed to send, must be done by your VAT return date. Leave it late and the pre-filled F2 will be missing your input VAT. Businesses that still file VAT quarterly work to their quarterly return date instead of the monthly dates shown here. The B2B e-invoicing mandate phasing in from 2026 changes how invoices are issued, not this deadline.
Source
Απόφαση Α.1138/2020 (myDATA), κωδικοποίηση ΑΑΔΕ με Α.1048 και Α.1049/2024 — άρθρο 5 παρ. 3 ΑΑΔΕ
See the source text
“Στις περιπτώσεις α΄ έως και ε΄ της παρ. 4 του άρθρου 4, η διαβίβαση πραγματοποιείται έως την ημερομηνία υποβολής της οικείας δήλωσης Φ.Π.Α., ανάλογα με το λογιστικό σύστημα που τηρεί ο λήπτης (απλογραφικό-διπλογραφικό).”
Screenshot of ΑΑΔΕ showing the myDATA — expense classification and recipient-side transmissions deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Τριμηνιαία έκθεση ειδικού καθεστώτος μικρών επιχειρήσεων (άρθρο 44γ) — EU cross-border SME scheme report

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — EU SME scheme · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Greek-established small businesses using other member states' VAT exemption under the EU cross-border SME scheme (EX-suffixed number)
Notes
Small businesses using the EU-wide exemption report their turnover in Greece and in every other member state each quarter, within a month of the quarter ending, including quarters with nothing to report. Passing EUR 100,000 of EU-wide turnover triggers a separate notification within 15 working days.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 44γ παρ. 3, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 ΑΑΔΕ
See the source text
“μηνός από το τέλος του ημερολογιακού τριμήνου με ηλεκτρονικά μέσα και αποτελεί δήλωση πληροφοριακού χαρακτήρα.”
Captured from ΑΑΔΕ on 2026-10-08
Δήλωση ΦΠΑ ειδικού καθεστώτος της Ένωσης (OSS) — Union scheme

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Businesses registered in Greece for the Union OSS scheme (intra-EU distance sales of goods and B2C services taxed in other member states)
Notes
Due every quarter, even if nothing was sold, by the end of the following month, with the payment on the same day. Unlike domestic Greek deadlines this one never moves: the third quarter of 2026 is due Saturday 31 October 2026, the day after the domestic F2 deadline of Friday the 30th.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 57 παρ. 6 και 9, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 ΑΑΔΕ
See the source text
“υποβάλλει με ηλεκτρονικά μέσα, δήλωση ΦΠΑ για κάθε ημερολογιακό τρίμηνο είτε έχουν πραγματοποιηθεί παραδόσεις αγαθών και παροχές υπηρεσιών που υπάγονται στο παρόν ειδικό καθεστώς είτε όχι. Η δήλωση ΦΠΑ υποβάλλεται μέχρι το τέλος του μήνα που ακολουθεί τη λήξη της φορολογικής περιόδου την οποία καλύπτει η δήλωση.”
Screenshot of ΑΑΔΕ showing the Δήλωση ΦΠΑ ειδικού καθεστώτος της Ένωσης (OSS) — Union scheme deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Δήλωση ΦΠΑ μη ενωσιακού καθεστώτος (OSS) — non-Union scheme

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Businesses established outside the EU registered in Greece for the non-Union OSS scheme (B2C services to EU consumers)
Notes
Non-EU sellers of digital and other services to EU consumers who chose Greece as their OSS member state file quarterly by the last day of the following month and pay at the same time. A Saturday or Sunday deadline is not extended, so plan to file on the last working day before it.
Source
European Commission — VAT One Stop Shop, national VAT rules: Greece European Commission (text supplied by Greece)
See the source text
“In case the final date for submitting the return is Saturday, Sunday or public holiday, the submission and payment of the tax is not extended to the next working day in accordance with the second paragraph of paragraph 1 of article 7 of law 5104/2024.”
Screenshot of European Commission (text supplied by Greece) showing the Δήλωση ΦΠΑ μη ενωσιακού καθεστώτος (OSS) — non-Union scheme deadline Open full size Captured from European Commission (text supplied by Greece) on 2026-10-08

Δήλωση ΦΠΑ ειδικού καθεστώτος εισαγωγής (IOSS)

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-08
Who files
Sellers and intermediaries registered in Greece for IOSS (distance sales of imported goods in consignments up to EUR 150)
Notes
IOSS returns are monthly and required even for a month with no sales. The return and the VAT are due by the last day of the next month — on the calendar day itself, whatever day of the week it is. January 2027's return is therefore due Sunday 28 February 2027.
Source
Κώδικας ΦΠΑ (ν. 5144/2024) — άρθρο 58 παρ. 9 και 11, κωδικοποίηση ΑΑΔΕ έως 1.1.2026 ΑΑΔΕ
See the source text
“υποβάλλει με ηλεκτρονικά μέσα δήλωση ΦΠΑ για κάθε μήνα είτε έχουν πραγματοποιηθεί εξ αποστάσεως πωλήσεις αγαθών που εισάγονται από τρίτες χώρες ή τρίτα εδάφη, είτε όχι. Η δήλωση υποβάλλεται μέχρι το τέλος του μήνα που ακολουθεί τη λήξη της φορολογικής περιόδου την οποία καλύπτει η δήλωση.”
Screenshot of ΑΑΔΕ showing the Δήλωση ΦΠΑ ειδικού καθεστώτος εισαγωγής (IOSS) deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Δήλωση έναρξης εργασιών — start-of-business declaration

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — μητρώο · One-off · registration

at least 1 day before the first business transaction Verified 2026-10-08
Who files
Every natural person starting a business activity in Greece — there is no VAT registration threshold; the declaration states which VAT regime applies
Notes
Greece has no turnover threshold for registering: everyone starting a business files a start declaration before the first sale or purchase, and the declaration itself sets whether you are in the normal VAT regime or the small-business exemption. Companies and other legal persons have 30 days from incorporation instead.
Source
Κώδικας Φορολογικής Διαδικασίας (ν. 5104/2024) — άρθρο 11 παρ. 2, κωδικοποίηση ΑΑΔΕ έως ν. 5259/2025 ΑΑΔΕ
See the source text
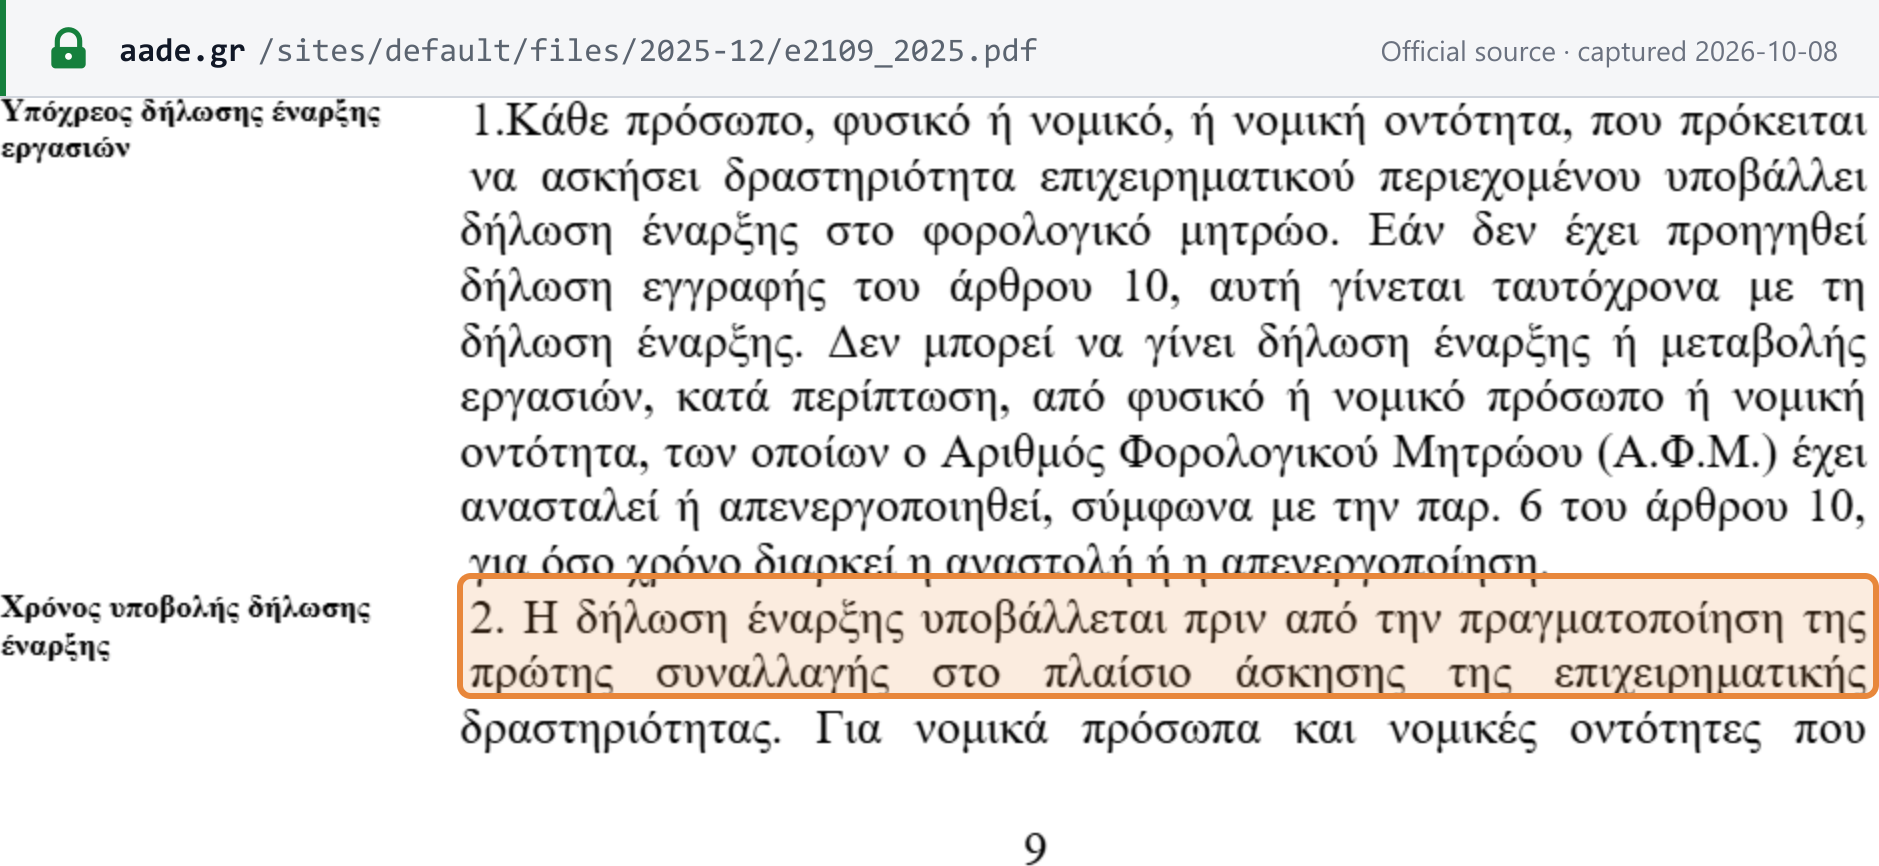
“2. Η δήλωση έναρξης υποβάλλεται πριν από την πραγματοποίηση της πρώτης συναλλαγής στο πλαίσιο άσκησης της επιχειρηματικής δραστηριότητας.”
Screenshot of ΑΑΔΕ showing the Δήλωση έναρξης εργασιών — start-of-business declaration deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
Δήλωση ενδοκοινοτικών συναλλαγών — registering for intra-EU transactions

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — μητρώο VIES · One-off · registration

at least 1 day before the first intra-EU transaction Verified 2026-10-08
Who files
Businesses (including small-business-exempt and farmers) that will make intra-EU supplies or acquisitions
Notes
A Greek VAT number is not automatically valid in VIES. Before your first cross-border EU sale or purchase you must declare that you will trade intra-EU; without it, suppliers in other member states cannot zero-rate their invoices to you.
Source
ν. 5104/2024 Κώδικας Φορολογικής Διαδικασίας (ΦΕΚ Α΄ 58/19.04.2024) — άρθρο 11 παρ. 12 Εθνικό Τυπογραφείο
See the source text
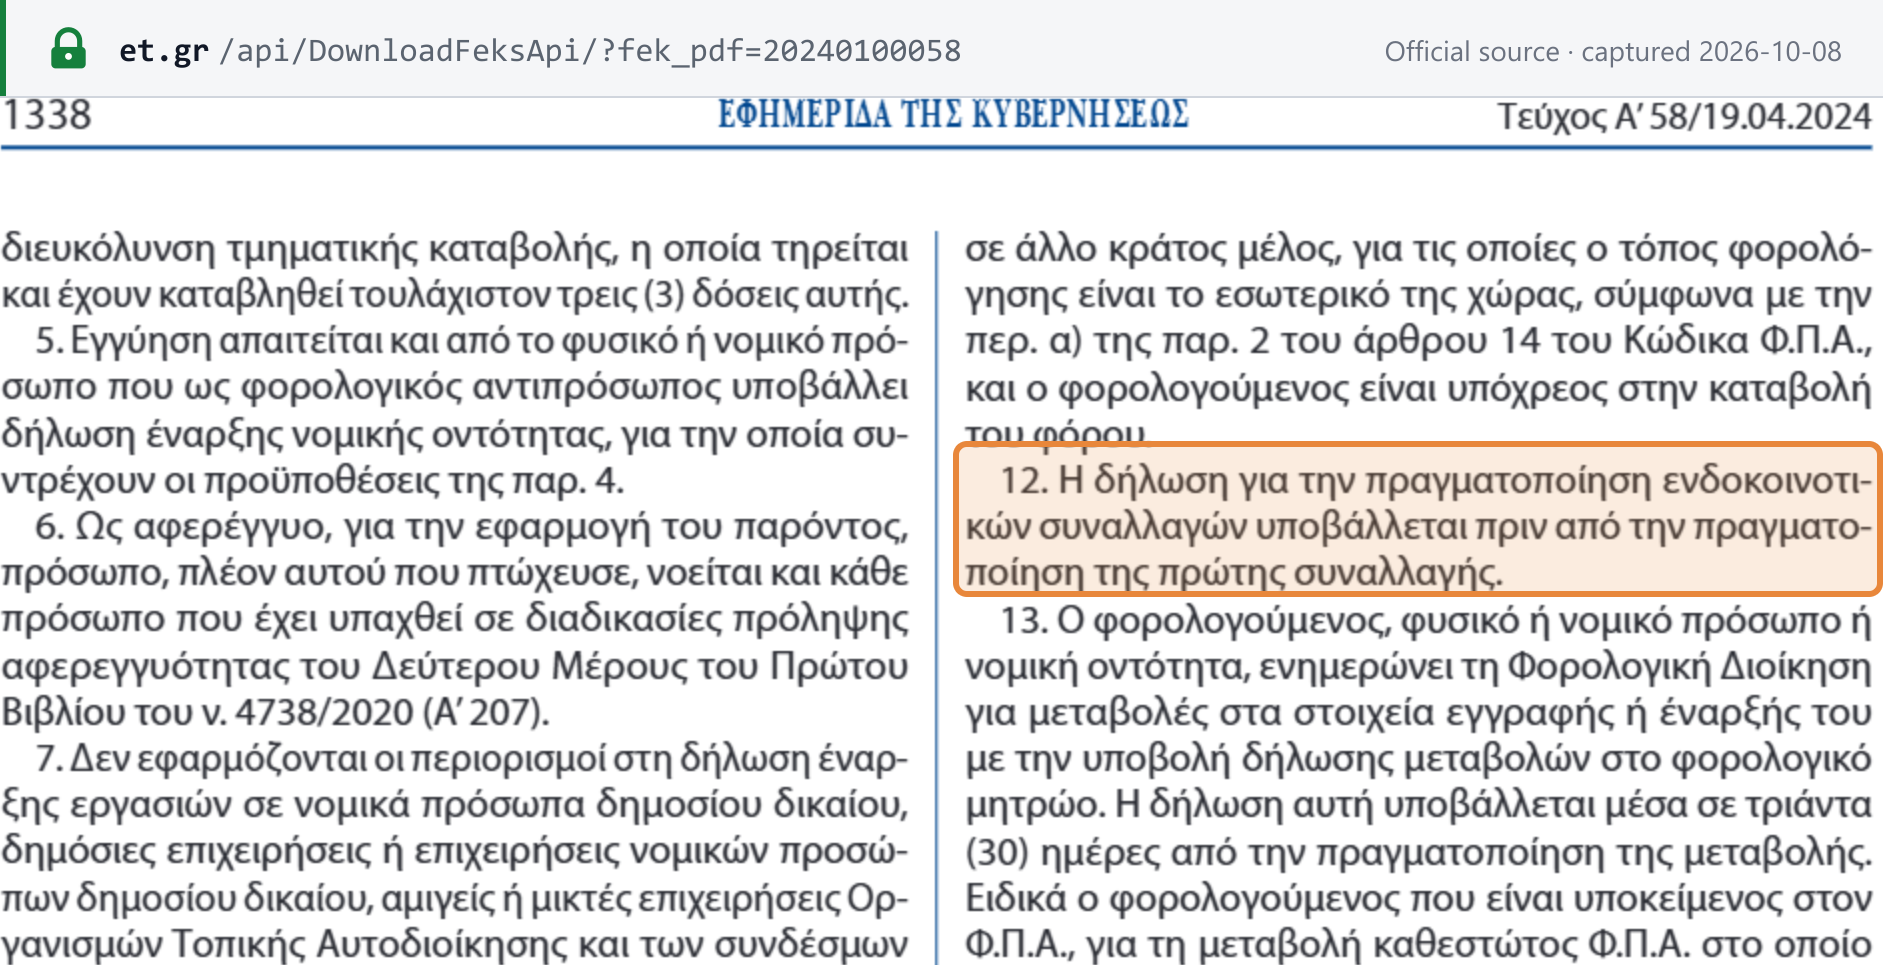
“12. Η δήλωση για την πραγματοποίηση ενδοκοινοτικών συναλλαγών υποβάλλεται πριν από την πραγματοποίηση της πρώτης συναλλαγής.”
Screenshot of Εθνικό Τυπογραφείο showing the Δήλωση ενδοκοινοτικών συναλλαγών — registering for intra-EU transactions deadline Open full size Captured from Εθνικό Τυπογραφείο on 2026-10-08

Δήλωση μεταβολών / μετάταξης — changes, including leaving the small-business exemption

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — μητρώο · One-off · registration

within 30 days of the change (for exempt small businesses, the transaction that crosses the EUR 10,000 limit) Verified 2026-10-08
Who files
Registered businesses whose registration details or VAT regime change — including a small business whose turnover crosses the EUR 10,000 exemption limit
Notes
The 30 days is for the paperwork only. A small business that crosses EUR 10,000 is in the normal VAT regime from the very sale that takes it over the limit, and charges VAT on the whole of that sale; the declaration moving it across can follow within 30 days. Since 2025 a business can also leave the exemption voluntarily at any point in the year. The 30-day rule gives way where the VAT Code sets its own timing, as it does for the flat-rate and farmers' schemes.
Source
ν. 5104/2024 Κώδικας Φορολογικής Διαδικασίας (ΦΕΚ Α΄ 58/19.04.2024) — άρθρο 11 παρ. 13 Εθνικό Τυπογραφείο
See the source text
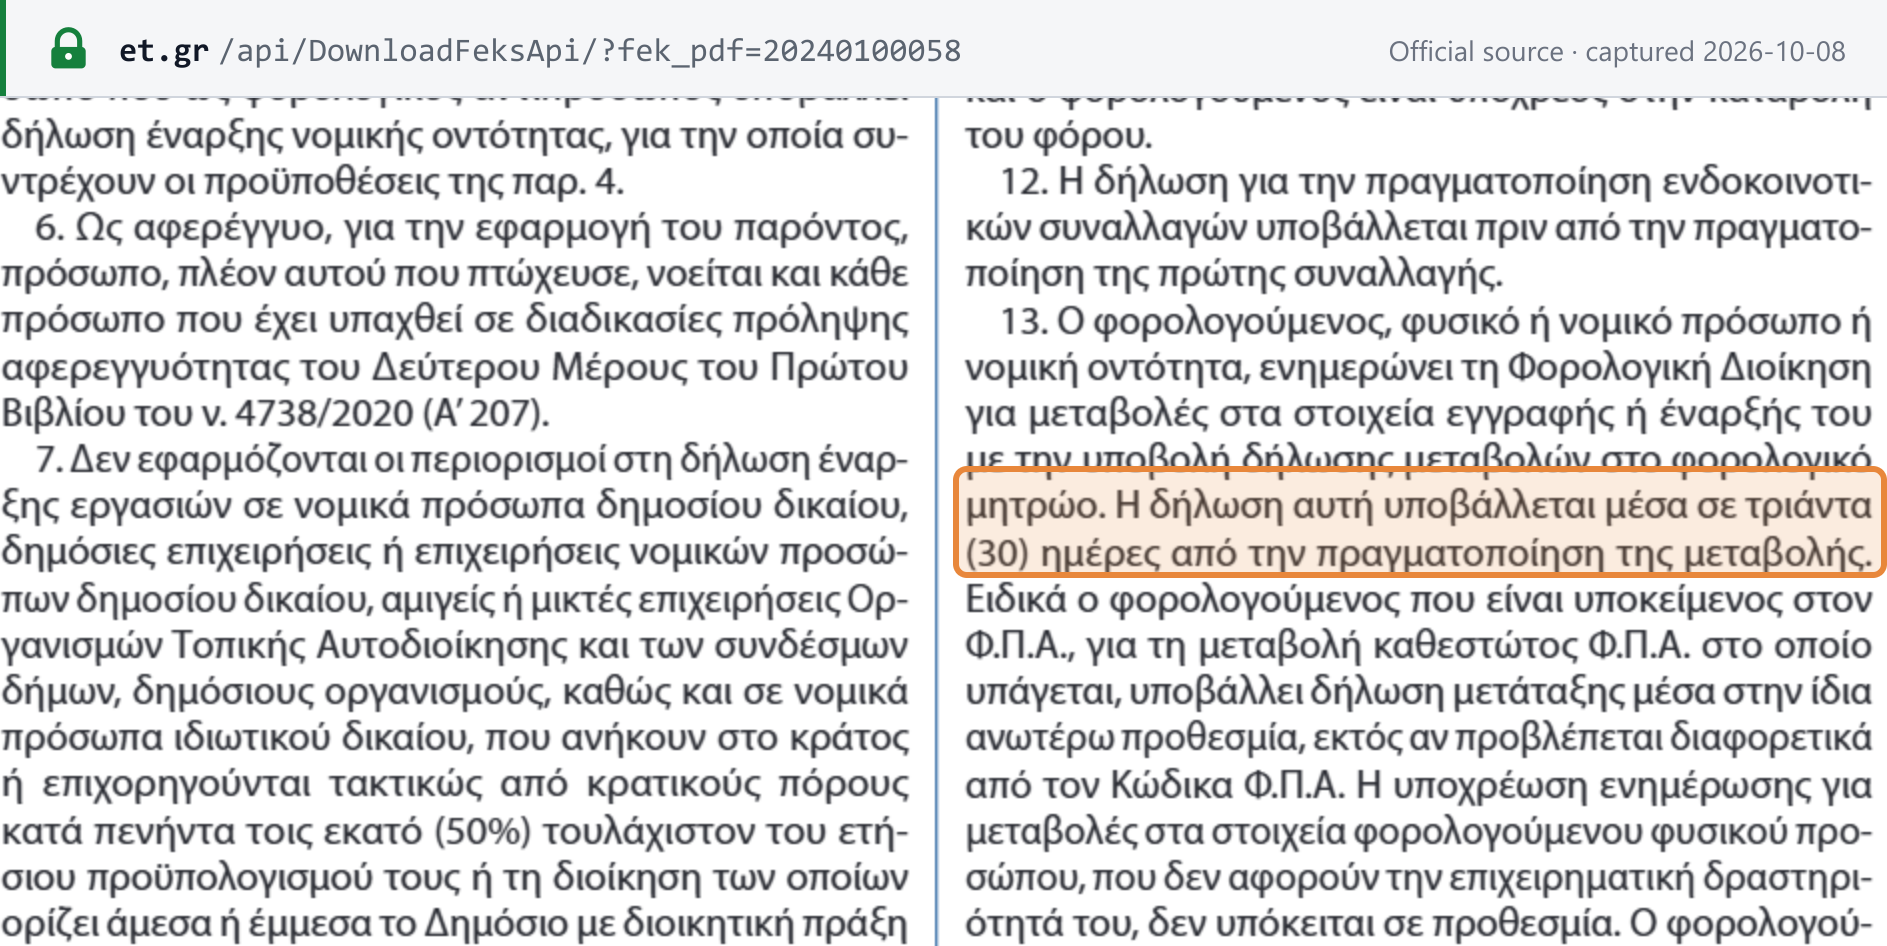
“Η δήλωση αυτή υποβάλλεται μέσα σε τριάντα (30) ημέρες από την πραγματοποίηση της μεταβολής. Ειδικά ο φορολογούμενος που είναι υποκείμενος στον Φ.Π.Α., για τη μεταβολή καθεστώτος Φ.Π.Α. στο οποίο υπάγεται, υποβάλλει δήλωση μετάταξης μέσα στην ίδια ανωτέρω προθεσμία”
Screenshot of Εθνικό Τυπογραφείο showing the Δήλωση μεταβολών / μετάταξης — changes, including leaving the small-business exemption deadline Open full size Captured from Εθνικό Τυπογραφείο on 2026-10-08

Δήλωση διακοπής εργασιών — cessation of business

Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) — μητρώο · One-off · registration

within 30 days of the final cessation of business Verified 2026-10-08
Who files
Natural persons finally ceasing business activity (legal persons: 30 days from dissolution or the end of liquidation)
Notes
Closing down is declared within 30 days of stopping for good. The VAT returns for the final periods are still owed, and the cessation does not wipe out VAT already due.
Source
Κώδικας Φορολογικής Διαδικασίας (ν. 5104/2024) — άρθρο 11 παρ. 16, κωδικοποίηση ΑΑΔΕ έως ν. 5259/2025 ΑΑΔΕ
See the source text
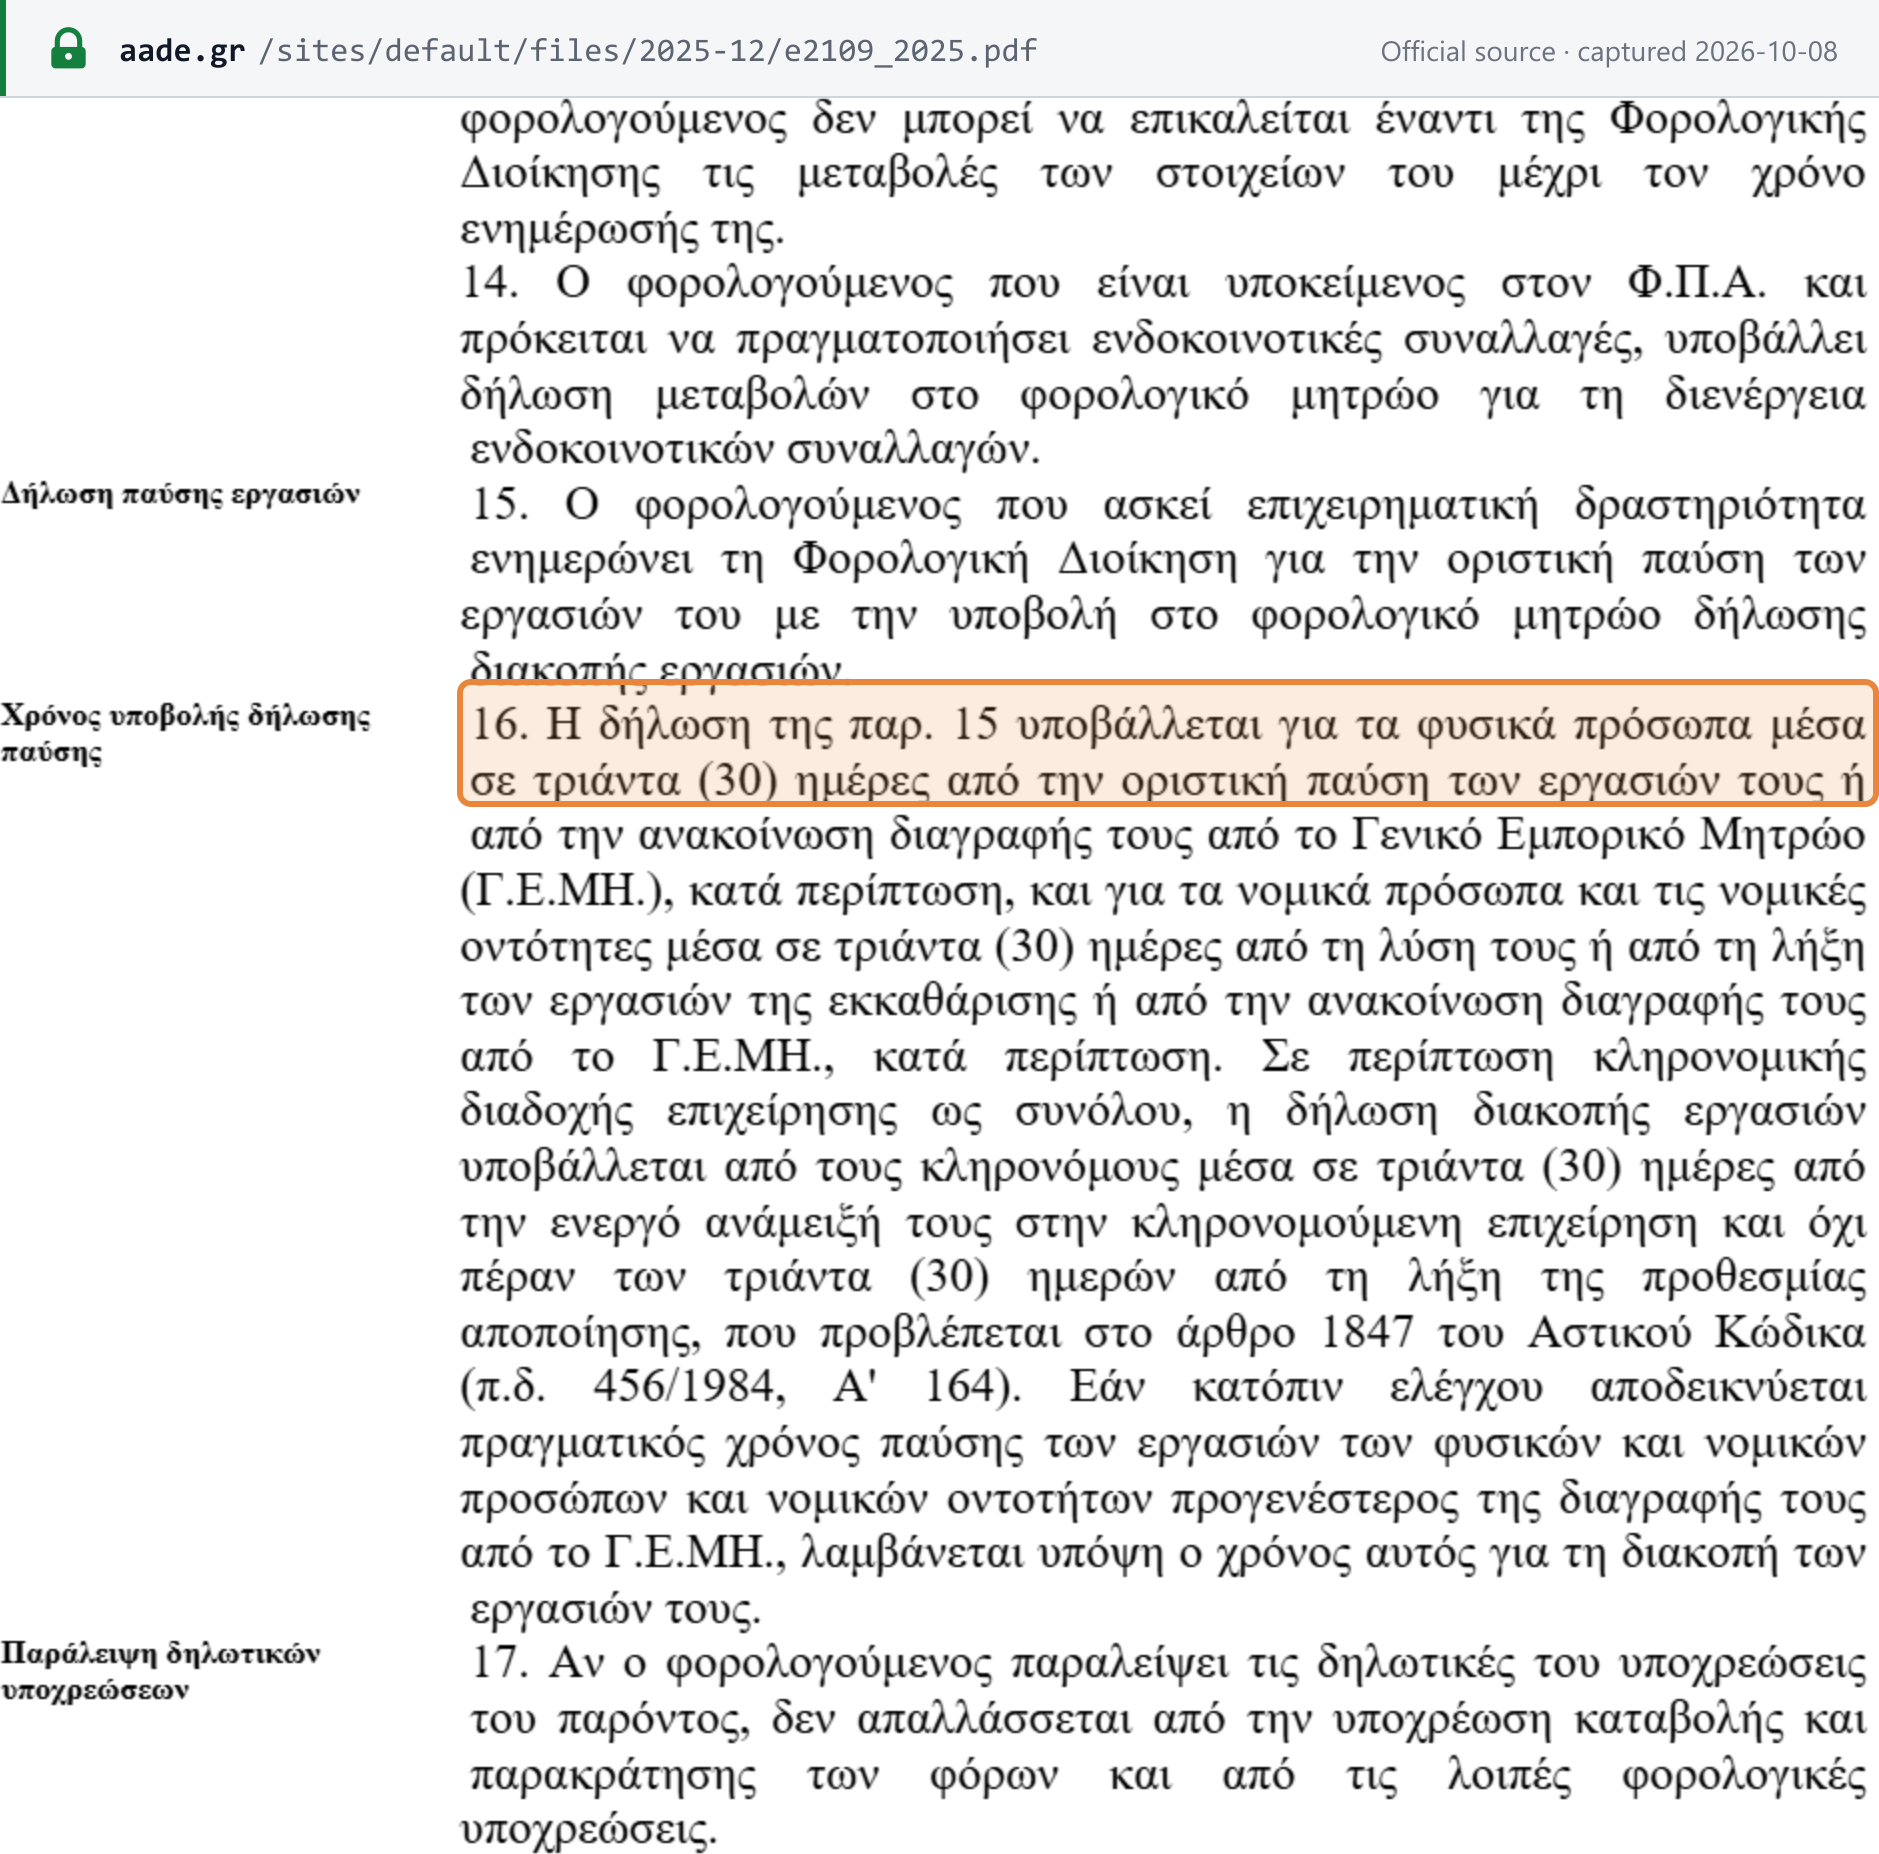
“16. Η δήλωση της παρ. 15 υποβάλλεται για τα φυσικά πρόσωπα μέσα σε τριάντα (30) ημέρες από την οριστική παύση των εργασιών τους”
Screenshot of ΑΑΔΕ showing the Δήλωση διακοπής εργασιών — cessation of business deadline Open full size Captured from ΑΑΔΕ on 2026-10-08
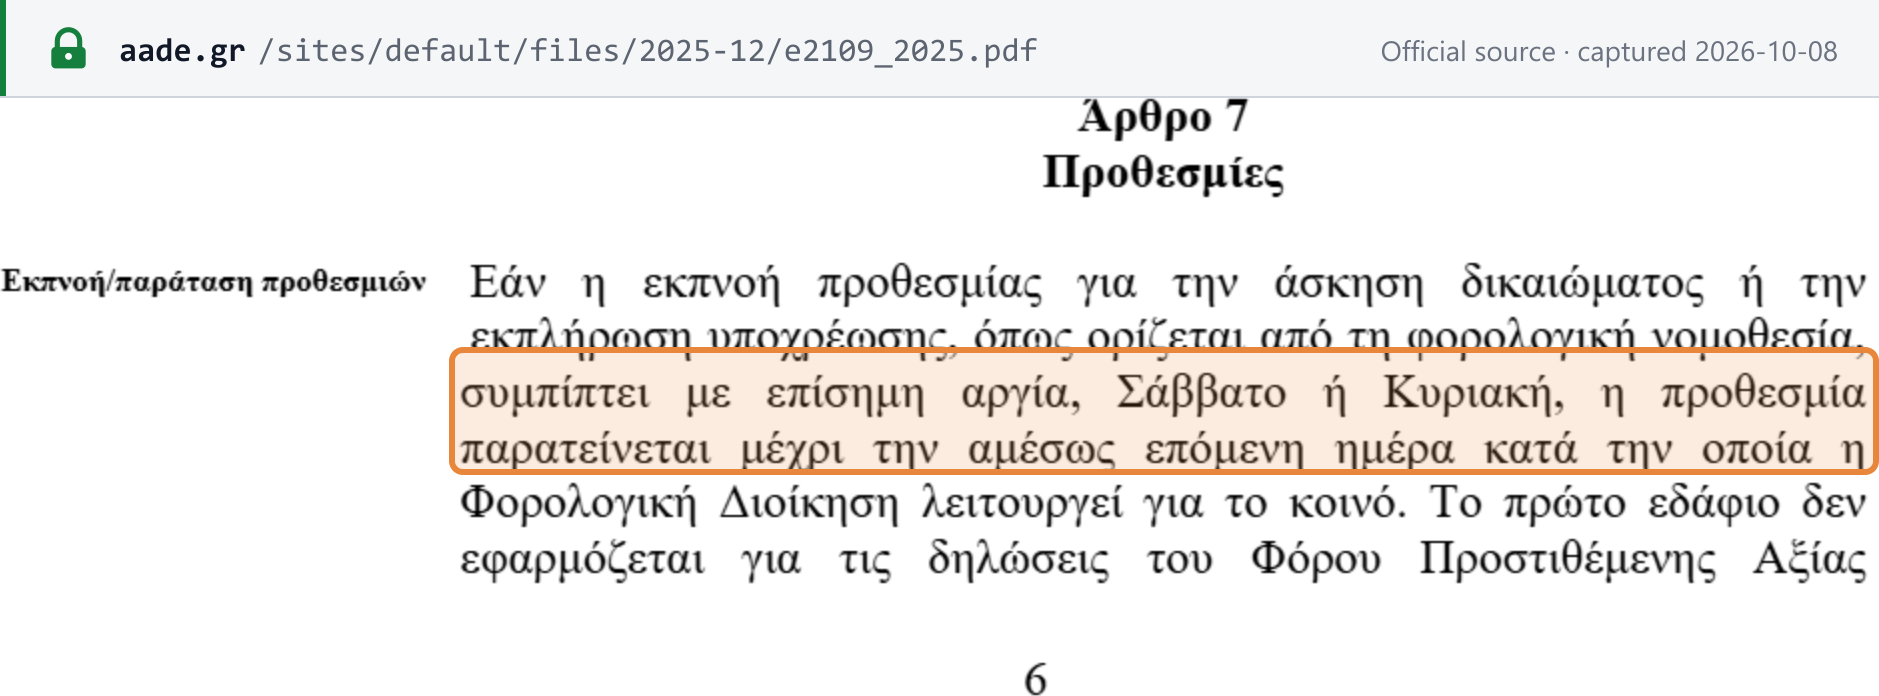
Most Greek VAT deadlines are set as the last working day for public services of a month, so when the month ends on a weekend or public holiday the deadline moves EARLIER, not later — the March 2027 return is due on Thursday 29 April 2027 because 30 April is Good Friday. Recapitulative statements, due on the 26th, move the other way, to the next working day. One Stop Shop returns do not move at all. Local patron-saint days are not on this calendar; filing is electronic through TAXISnet, so they rarely matter. The climate resilience fee on accommodation and excise duties are not on this calendar yet; income tax, payroll and stamp duties are outside it.

“Εάν η εκπνοή προθεσμίας για την άσκηση δικαιώματος ή την εκπλήρωση υποχρέωσης, όπως ορίζεται από τη φορολογική νομοθεσία, συμπίπτει με επίσημη αργία, Σάββατο ή Κυριακή, η προθεσμία παρατείνεται μέχρι την αμέσως επόμενη ημέρα κατά την οποία η Φορολογική Διοίκηση λειτουργεί για το κοινό.”
Screenshot of the official source stating the rule that governs Greece's deadlines
Κώδικας Φορολογικής Διαδικασίας (ν. 5104/2024) — άρθρο 7 παρ. 1, κωδικοποίηση ΑΑΔΕ έως ν. 5259/2025 (εγκ. Ε.2109/2025) — ΑΑΔΕ, captured 2026-10-08

What this calendar does not list

  • Not yet covered Periodic return — Not yet modelled: the climate resilience fee (τέλος ανθεκτικότητας στην κλιματική κρίση), declared monthly by accommodation providers by the last day of the following month (AADE FAQ, Q7), and excise duty (ΕΦΚ) returns under the Customs Code (ν. 2960/2001), whose cadences were not researched. Farmers and VAT-exempt small businesses also owe an F2 for any period with intra-EU acquisitions or reverse-charge purchases (VAT Code art. 43(8)); that deadline was not researched separately. Identified by verification on 2026-10-08.

About this calendar

Which Greece tax deadlines does this calendar cover?

15 recurring indirect-tax obligations — Φόρος Προστιθέμενης Αξίας (ΦΠΑ / VAT) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-08). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.