Latvia compliance calendar

17 recurring Pievienotās vērtības nodoklis (PVN / VAT), Strukturēti elektroniskie rēķini (e-invoicing) and Akcīzes nodoklis (excise duty) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Latvia rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Payment Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Latvia applies one — 8 of 17 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

PVN deklarācija — monthly VAT return

Pievienotās vērtības nodoklis (PVN / VAT) · Monthly · return filing

20th day after the month ends Verified 2026-10-13
Who files
Registered VAT payers whose taxable supplies exceeded EUR 50,000 in the previous or current year; anyone making intra-EU supplies of goods, B2B services taxed in another member state, triangular or call-off-stock supplies; every new registrant for its first six calendar months; VAT groups and fiscal representatives
Notes
File the return and its annexes through VID's Electronic Declaration System within 20 days of the month's end, including months with no taxable transactions. The November 2026 return is due Monday 21 December, because the 20th is a Sunday; the December return follows on 20 January 2027. A quarterly filer who passes EUR 50,000 or starts supplying other EU businesses switches to monthly from that month until the end of the year.
Source
Pievienotās vērtības nodokļa likums — 118. pants, 1. daļa (period: 115. pants, 1., 2. un 7. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
“Reģistrēts nodokļa maksātājs deklarāciju un tās pielikumus iesniedz Valsts ieņēmumu dienestam 20 dienu laikā pēc taksācijas perioda beigām, ja šajā likumā nav noteikts citādi.”
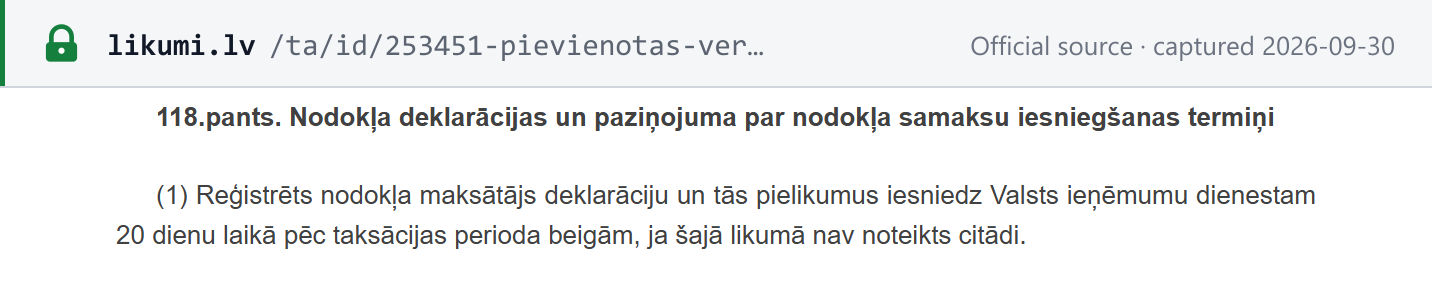
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN deklarācija — monthly VAT return deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-09-30
PVN deklarācija — quarterly VAT return

Pievienotās vērtības nodoklis (PVN / VAT) · Quarterly · return filing

20th day after the quarter ends Verified 2026-10-13
Who files
Registered VAT payers meeting none of the monthly conditions — taxable supplies of EUR 50,000 or less, no intra-EU supplies, and more than six months since registration; also state and municipal bodies registered only to receive construction services
Notes
Smaller businesses file once a quarter, by 20 January, 20 April, 20 July and 20 October; the first of them to land on a weekend is Saturday 20 January 2029, which moves to Monday the 22nd. A business that wants to move from monthly to quarterly filing has to notify VID by 31 January, and the change then runs for the calendar year.
Source
Pievienotās vērtības nodokļa likums — 115. pants, 3. daļa (deadline: 118. pants, 1. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
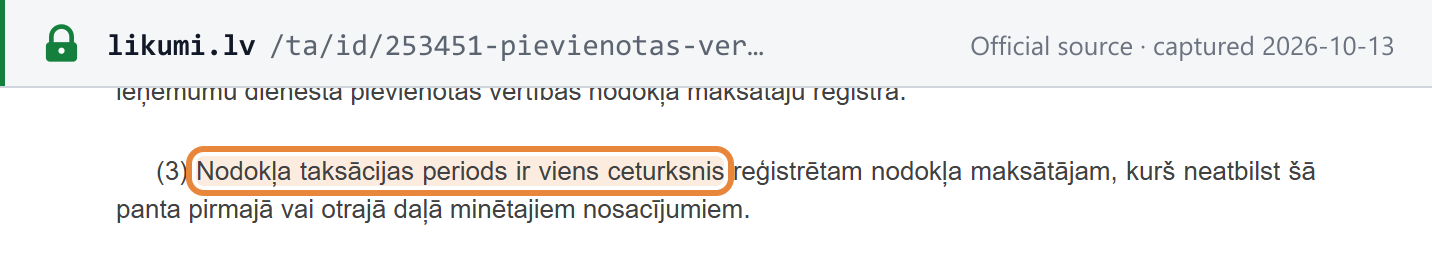
“Nodokļa taksācijas periods ir viens ceturksnis reģistrētam nodokļa maksātājam, kurš neatbilst šā panta pirmajā vai otrajā daļā minētajiem nosacījumiem.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN deklarācija — quarterly VAT return deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

PVN samaksa — VAT payment, monthly filers

Pievienotās vērtības nodoklis (PVN / VAT) · Monthly · payment

23rd day after the month ends Verified 2026-10-13
Who files
Registered VAT payers on monthly tax periods with VAT payable for the month
Notes
The VAT is paid three days after the return is filed, into the single tax account. Midsummer bites here: the 23rd and 24th of June are public holidays, so the May 2027 payment falls on Friday 25 June — or Monday 28 June if the government confirms 25 June as a transferred rest day, which it had not done as of July 2026. Paying on the 25th is safe either way. Late payment costs 0.05% a day, although no late-payment interest is charged if the money arrives by the last day of the month in which it was due.
Source
Pievienotās vērtības nodokļa likums — 119. pants, 1. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
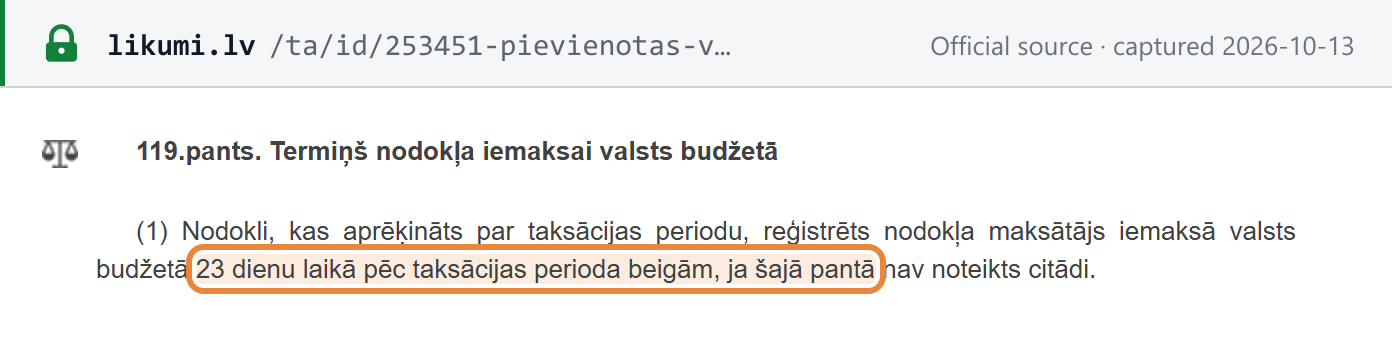
“Nodokli, kas aprēķināts par taksācijas periodu, reģistrēts nodokļa maksātājs iemaksā valsts budžetā 23 dienu laikā pēc taksācijas perioda beigām, ja šajā pantā nav noteikts citādi.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN samaksa — VAT payment, monthly filers deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

PVN samaksa — VAT payment, quarterly filers

Pievienotās vērtības nodoklis (PVN / VAT) · Quarterly · payment

23rd day after the quarter ends Verified 2026-10-13
Who files
Registered VAT payers on quarterly tax periods with VAT payable for the quarter
Notes
Quarterly VAT is due 23 days after the quarter ends. When the 23rd falls on a weekend the payment moves to Monday: the fourth-quarter 2026 payment is due 25 January 2027 and the third-quarter 2027 payment 25 October.
Source
Pievienotās vērtības nodokļa likums — 119. pants, 1. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“Nodokli, kas aprēķināts par taksācijas periodu, reģistrēts nodokļa maksātājs iemaksā valsts budžetā 23 dienu laikā pēc taksācijas perioda beigām, ja šajā pantā nav noteikts citādi.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN samaksa — VAT payment, quarterly filers deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

Importa režīms nodokļa maksātājiem, kas uzrāda preces muitas iestādei — monthly import VAT payment

Pievienotās vērtības nodoklis (PVN / VAT) — import special arrangement · Monthly · payment

16th of the month after the month ends Verified 2026-10-13
Who files
Persons presenting low-value consignments (up to EUR 150) to customs — typically postal operators and couriers — who use the special arrangement instead of IOSS and whose payment is secured by a comprehensive customs guarantee
Notes
A carrier that collects VAT from recipients of low-value parcels under this special arrangement pays it once a month, by the 16th of the month after the goods were declared, based on the monthly total customs reports to it. A 16th falling on a weekend or holiday moves to the next working day — the December 2026 total is due Monday 18 January 2027.
Source
Pievienotās vērtības nodokļa likums — 140.⁵ pants, 6. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“šā panta pirmajā daļā minētais nodokļa maksātājs iemaksā valsts budžetā līdz mēnesim, kurā preces ir deklarētas, sekojošā mēneša sešpadsmitajam datumam.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the Importa režīms nodokļa maksātājiem, kas uzrāda preces muitas iestādei — monthly import VAT payment deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

PVN 4 — deklarācija par taksācijas gadu (annual VAT return)

Pievienotās vērtības nodoklis (PVN / VAT) · Annually · return filing

1st May each year Verified 2026-10-13
Who files
Only registered VAT payers whose taxable/exempt proportion changed over the year, who adjust output tax or deducted input tax, who made certain financial transactions under s.38(2)–(3), or who excluded deposit-packaging amounts from taxable value — including part-year filers in those cases
Notes
Not every business files this. It is where a business that makes both taxable and exempt supplies settles its input-VAT deduction on the year's actual proportion, or records other annual adjustments. The legal date is 1 May, but 1 May is Labour Day, a public holiday, so the deadline always moves: Monday 3 May in 2027 and Tuesday 2 May in 2028. Any VAT the annual return shows as due is payable by the same date.
Source
Pievienotās vērtības nodokļa likums — 118. pants, 5. daļa (payment: 119. pants, 6. daļa; who files: 117. pants, 5. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
“Reģistrēts nodokļa maksātājs iesniedz Valsts ieņēmumu dienestam deklarāciju par taksācijas gadu līdz nākamā taksācijas gada 1.maijam.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN 4 — deklarācija par taksācijas gadu (annual VAT return) deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

Pārskats par preču piegādēm un sniegtajiem pakalpojumiem Eiropas Savienības teritorijā — EC sales list

Pievienotās vērtības nodoklis (PVN / VAT) · Monthly · report / listing

20th day after the month ends Verified 2026-10-13
Who files
Registered VAT payers that, in the month, supplied goods to another EU member state, supplied B2B services taxed where the customer is established in another member state, or moved goods to a call-off stock in another member state
Notes
Latvia's EC sales list is filed as an annex to the VAT return, for every calendar month in which you made an EU supply, by the same 20-day deadline. There is no quarterly option and no threshold, and the same supplies also put you on monthly VAT returns, so the two travel together. Corrections to earlier months go on a separate correction annex.
Source
Pievienotās vērtības nodokļa likums — 118. pants, 6. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“Reģistrēts nodokļa maksātājs iesniedz Valsts ieņēmumu dienestam pārskatu par preču piegādēm un sniegtajiem pakalpojumiem Eiropas Savienības teritorijā par katru kalendāra mēnesi šā panta pirmajā daļā noteiktajā termiņā, ja tas:”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the Pārskats par preču piegādēm un sniegtajiem pakalpojumiem Eiropas Savienības teritorijā — EC sales list deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

PVN deklarācija — ārpussavienības režīms (non-Union OSS)

Pievienotās vērtības nodoklis (PVN / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Non-EU businesses using Latvia as member state of identification for the non-Union OSS scheme (B2C services to EU consumers)
Notes
One return a quarter, due with the payment by the last day of the following month, and owed even for a quarter with no sales. Treat a weekend as no extension: the third quarter of 2026 is due Saturday 31 October, so file on Friday the 30th.
Source
Pievienotās vērtības nodokļa likums — 140.² pants, 8. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“līdz taksācijas periodam sekojošā mēneša beigām iesniedz Valsts ieņēmumu dienestam, izmantojot Valsts ieņēmumu dienesta Elektroniskās deklarēšanas sistēmu, par katru ceturksni nodokļa deklarāciju par darījumiem, uz kuriem attiecas ārpussavienības režīms.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN deklarācija — ārpussavienības režīms (non-Union OSS) deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

PVN deklarācija — savienības režīms (Union OSS)

Pievienotās vērtības nodoklis (PVN / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Businesses using Latvia as member state of identification for the Union OSS scheme (intra-EU distance sales of goods and B2C services taxed in other member states)
Notes
Sellers registered in Latvia for the Union scheme report each quarter's cross-border consumer sales, nil quarters included, and pay by the end of the next month. Unlike the domestic return, the date does not roll forward: the fourth quarter of 2026 is due Sunday 31 January 2027.
Source
Pievienotās vērtības nodokļa likums — 140.³ pants, 8. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“līdz taksācijas periodam sekojošā mēneša beigām iesniedz Valsts ieņēmumu dienestam, izmantojot Valsts ieņēmumu dienesta Elektroniskās deklarēšanas sistēmu, par katru ceturksni nodokļa deklarāciju par darījumiem, uz kuriem attiecas savienības režīms.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN deklarācija — savienības režīms (Union OSS) deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

PVN deklarācija — importa režīms (IOSS)

Pievienotās vērtības nodoklis (PVN / VAT) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-13
Who files
Sellers and intermediaries registered in Latvia for IOSS (distance sales of imported goods in consignments up to EUR 150)
Notes
Monthly, nil months included, with return and payment both due on the last calendar day of the next month. Plan around year-end: the November 2026 return falls on 31 December, which is a public holiday in Latvia, and January 2027's on Sunday 28 February.
Source
Pievienotās vērtības nodokļa likums — 140.⁴ pants, 13. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“Šā panta otrajā daļā minētais nodokļa maksātājs vai starpnieks līdz taksācijas periodam sekojošā mēneša beigām iesniedz Valsts ieņēmumu dienestam, izmantojot Valsts ieņēmumu dienesta Elektroniskās deklarēšanas sistēmu, par katru mēnesi nodokļa deklarāciju par darījumiem, uz kuriem attiecas importa režīms.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN deklarācija — importa režīms (IOSS) deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

ES MVU režīms — ceturkšņa informācija (EU cross-border SME scheme report)

Pievienotās vērtības nodoklis (PVN / VAT) — EU SME scheme · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-13
Who files
Latvian businesses registered to use other member states' small-business exemption under the EU cross-border SME scheme
Notes
Small businesses using the EU-wide exemption report their Latvian and per-country turnover every quarter by the end of the following month, entering zero where they sold nothing. File by the last working day: no rule moves this report off a weekend. Crossing the EUR 100,000 EU turnover ceiling must be reported to VID within 15 working days.
Source
Pievienotās vērtības nodokļa likums — 139.¹ pants, 13. daļa Latvijas Vēstnesis (likumi.lv)
See the source text
“Iekšzemes nodokļa maksātājs, kas piemēro atbrīvojumu citā dalībvalstī, līdz kalendāra ceturksnim sekojošā mēneša beigām, aizpildot Valsts ieņēmumu dienesta Elektroniskās deklarēšanas sistēmā strukturētu datu formu, iesniedz Valsts ieņēmumu dienestam par katru kalendāra ceturksni šādu informāciju:”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the ES MVU režīms — ceturkšņa informācija (EU cross-border SME scheme report) deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

E-rēķina datu nodošana VID — structured e-invoice data to VID

Strukturēti elektroniskie rēķini (e-invoicing) · One-off · other

within 5 business days of sending a structured e-invoice to the customer Verified 2026-10-13
Who files
Since 1 January 2026, businesses issuing structured e-invoices to state and municipal budget institutions (and, per VID, those institutions' own invoices); every Latvian business invoicing another from 1 January 2028
Notes
Each structured e-invoice is reported to VID once, within five working days of the day it is sent — invoice by invoice, not in a monthly batch. Sending through the official e-address or a VID-integrated Peppol operator usually does this automatically. Today the duty covers invoices to public bodies; it extends to all business-to-business invoices from 1 January 2028, and businesses may report B2B invoices voluntarily before then.
Source
Ministru kabineta noteikumi Nr. 749 (09.12.2025.) — 14. punkts Latvijas Vēstnesis (likumi.lv)
See the source text
“E-rēķinu Valsts ieņēmumu dienestam iesniedz vienu reizi ne vēlāk kā piecu darbdienu laikā pēc tā nosūtīšanas dienas.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the E-rēķina datu nodošana VID — structured e-invoice data to VID deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

Reģistrācija PVN maksātāju reģistrā — mandatory VAT registration

Pievienotās vērtības nodoklis (PVN / VAT) · One-off · registration

within 15 days of the end of the month in which domestic supplies for the calendar year exceed EUR 55,000 (the EUR 50,000 threshold plus the EUR 5,000 tolerance) Verified 2026-10-13
Who files
Latvian taxable persons whose taxable supplies in a calendar year exceed EUR 50,000 by more than the EUR 5,000 tolerance (EUR 55,000 in total)
Notes
Apply to VID by the 15th of the month after the one in which your supplies for the year passed EUR 55,000. If you went over EUR 50,000 by no more than EUR 5,000, you may wait until the end of the year, applying by 30 November — or by 31 December if you crossed the threshold in December. The tolerance is not available if you also exceeded the threshold the year before. VAT on the supplies that took you over is payable within 23 days of that month's end; a business using the tolerance that is still unregistered on 1 January pays that VAT by 23 February.
Source
Pievienotās vērtības nodokļa likums — 59. pants, 5. daļa (tolerance: 4., 6. un 7. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
“Iekšzemes nodokļa maksātājs ne vēlāk kā līdz tā mēneša piecpadsmitajam datumam, kas seko mēnesim, kad ir pārsniegts šā panta pirmajā daļā minētais reģistrācijas slieksnis un ceturtajā daļā minētā vērtība, iesniedz Valsts ieņēmumu dienestam”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the Reģistrācija PVN maksātāju reģistrā — mandatory VAT registration deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-09-30
Reģistrācija — EU distance sellers not using the One Stop Shop

Pievienotās vērtības nodoklis (PVN / VAT) · One-off · registration

within 30 days of EU-wide distance sales and e-services to consumers reaching EUR 10,000 in the previous or current calendar year Verified 2026-10-13
Who files
Taxable persons established in another EU member state making distance sales of goods into Latvia (or telecoms, broadcasting and electronic services to Latvian consumers) who do not use the Union OSS
Notes
An EU seller whose cross-border sales to consumers reach EUR 10,000 across the EU must either register for VAT in Latvia within 30 days or account through the One Stop Shop in its home country. Sellers of excise goods register before the first supply.
Source
Pievienotās vērtības nodokļa likums — 60. pants, 2. daļa, 1. punkts Latvijas Vēstnesis (likumi.lv)
See the source text
“30 dienu laikā no brīža, kad preču piegāžu kopējā vērtība iepriekšējā vai kārtējā kalendāra gadā ir sasniegusi vai pārsniegusi 10 000 euro;”
Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

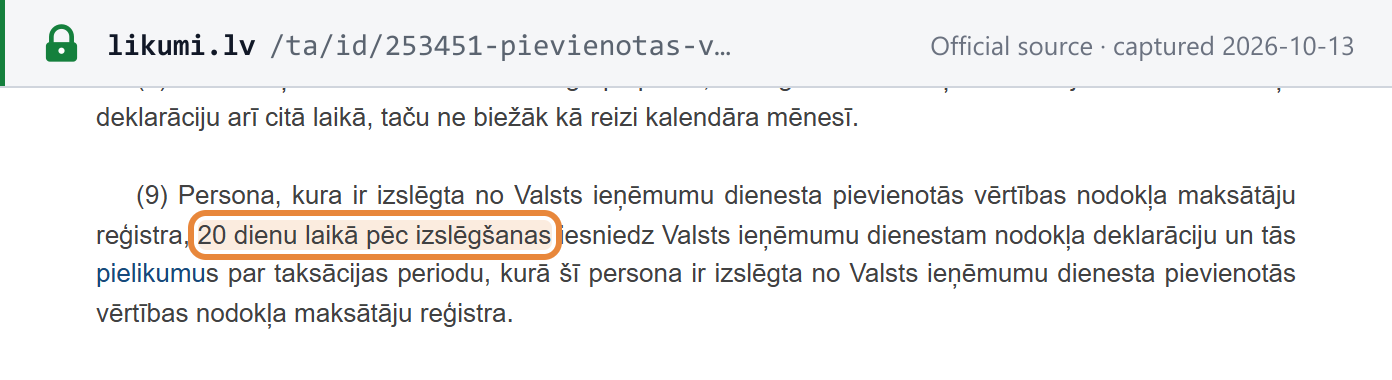
PVN deklarācija pēc izslēgšanas no reģistra — final return after deregistration

Pievienotās vērtības nodoklis (PVN / VAT) · One-off · registration

within 20 days of removal from the VAT register Verified 2026-10-13
Who files
Every person removed from the VAT register, on its own application or by VID
Notes
Leaving the register triggers a last return, with its annexes, for the period in which you were removed: it is due within 20 days of removal, and the VAT on it within 23 days. If the last day is a weekend or holiday, both move to the next working day. VID can also remove a business that has not filed a return within 30 days of its due date, after first sending a written warning and allowing 12 working days to put it right; removal then starts this same clock.
Source
Pievienotās vērtības nodokļa likums — 118. pants, 9. daļa (payment: 119. pants, 4. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
“Persona, kura ir izslēgta no Valsts ieņēmumu dienesta pievienotās vērtības nodokļa maksātāju reģistra, 20 dienu laikā pēc izslēgšanas iesniedz Valsts ieņēmumu dienestam nodokļa deklarāciju un tās pielikumus par taksācijas periodu, kurā šī persona ir izslēgta no Valsts ieņēmumu dienesta pievienotās vērtības nodokļa maksātāju reģistra.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the PVN deklarācija pēc izslēgšanas no reģistra — final return after deregistration deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

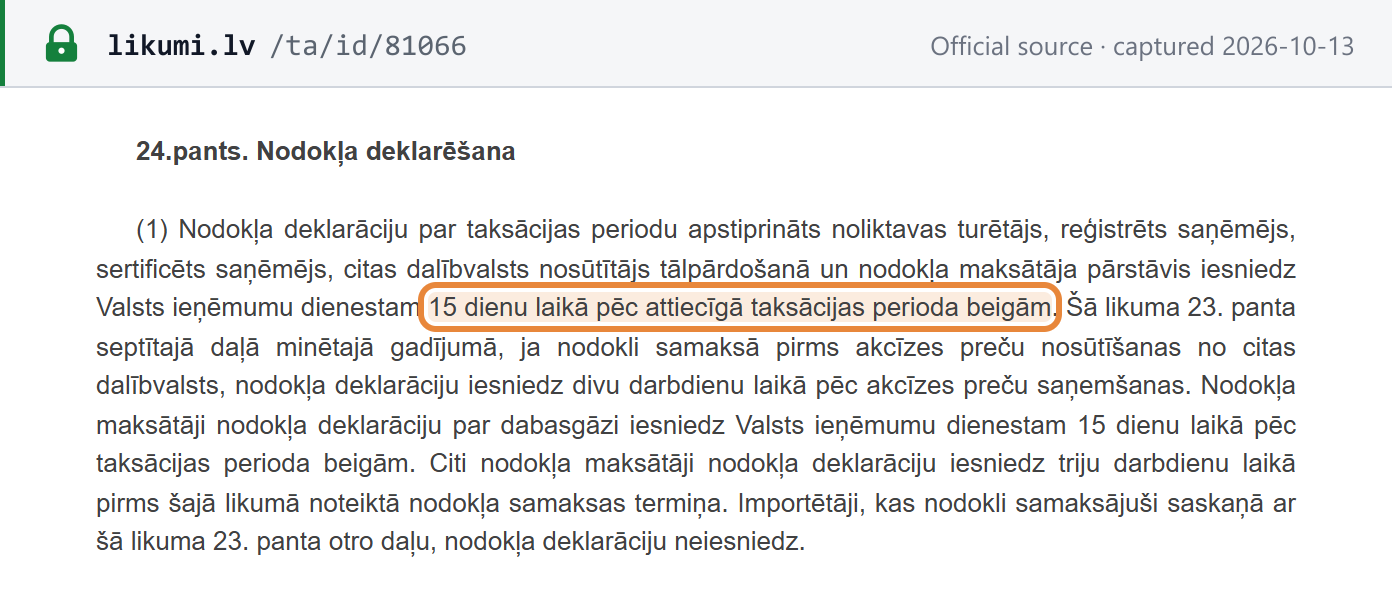
Akcīzes nodokļa deklarācija — monthly excise return

Akcīzes nodoklis (excise duty) · Monthly · return filing

15th day after the month ends Verified 2026-10-13
Who files
Authorised warehouse keepers (one return per warehouse), registered and certified consignees, distance sellers from other member states and tax representatives — for petroleum products, alcohol, tobacco, coffee and non-alcoholic drinks, e-cigarette liquids and tobacco substitutes, and natural gas
Notes
Excise runs on calendar months: the return is due within 15 days of the month's end, and the duty is paid later, by the 23rd. The excise law has no weekend rule for the return, so a 15th on a Saturday or Sunday — 15 November 2026, 15 May and 15 August 2027 — should be treated as the deadline itself. Temporary consignees and people bringing in duty-paid goods follow shorter, shipment-based deadlines instead.
Source
Likums "Par akcīzes nodokli" — 24. pants, 1. daļa (period: 23. pants, 1. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
“iesniedz Valsts ieņēmumu dienestam 15 dienu laikā pēc attiecīgā taksācijas perioda beigām.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the Akcīzes nodokļa deklarācija — monthly excise return deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

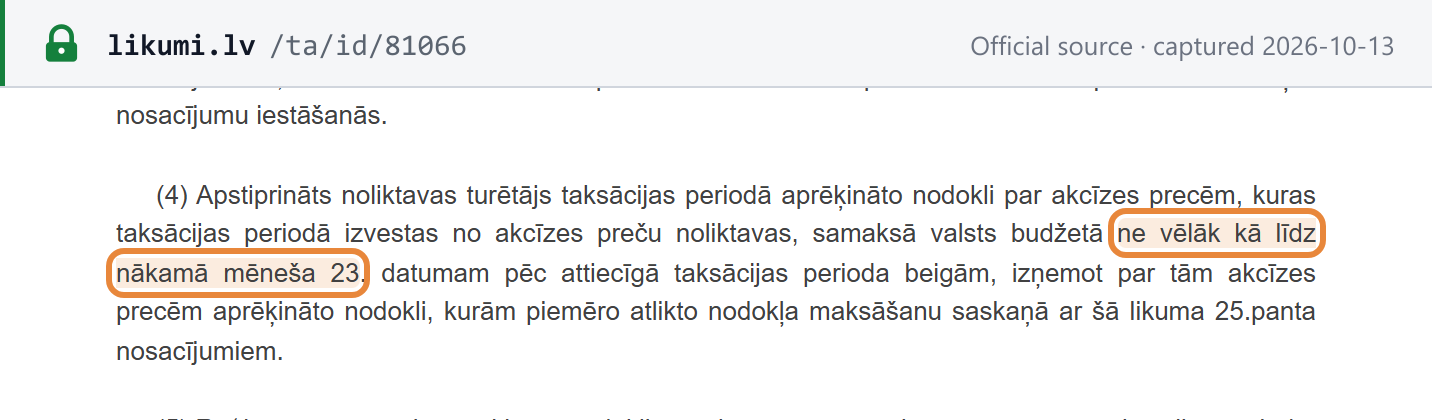
Akcīzes nodokļa samaksa — monthly excise payment

Akcīzes nodoklis (excise duty) · Monthly · payment

23rd of the month after the month ends Verified 2026-10-13
Who files
Authorised warehouse keepers, registered and certified consignees, distance sellers from other member states and tax representatives paying excise for the calendar month
Notes
Excise for the month is paid by the 23rd of the next month — eight days after the return. Unlike the return, the payment does move off a weekend or holiday to the next working day, so the January 2027 payment for December is due Monday 25 January. Midsummer pushes the May 2027 payment to Friday 25 June, or to Monday 28 June if 25 June is confirmed as a transferred rest day — not yet decided as of July 2026.
Source
Likums "Par akcīzes nodokli" — 23. pants, 4. daļa (also 5., 6.¹, 8., 8.¹, 11. un 27. daļa) Latvijas Vēstnesis (likumi.lv)
See the source text
“Apstiprināts noliktavas turētājs taksācijas periodā aprēķināto nodokli par akcīzes precēm, kuras taksācijas periodā izvestas no akcīzes preču noliktavas, samaksā valsts budžetā ne vēlāk kā līdz nākamā mēneša 23.”
Screenshot of Latvijas Vēstnesis (likumi.lv) showing the Akcīzes nodokļa samaksa — monthly excise payment deadline Open full size Captured from Latvijas Vēstnesis (likumi.lv) on 2026-10-13

Latvia files on the 20th and pays on the 23rd: the VAT return and the EU sales listing are due 20 days after the period ends, and the VAT itself 23 days after, into the single tax account. When the last day is a Saturday, Sunday or public holiday, both the filing and the payment move to the next working day. The One Stop Shop returns are the exception and are due on the last day of the month with no extension. Most businesses file quarterly; monthly filing applies above EUR 50,000 of taxable supplies, to anyone trading with other EU businesses, and for the first six months after registration. Registration itself is due by the 15th of the month after supplies pass EUR 55,000 in a calendar year.

“Ja nodokļa deklarācijas iesniegšanas termiņš ir brīvdiena vai svētku diena, deklarācijas iesniegšanas termiņa pēdējā diena ir nākamā darbdiena.”
Screenshot of the official source stating the rule that governs Latvia's deadlines
Pievienotās vērtības nodokļa likums — 118. pants, 7. daļa — Latvijas Vēstnesis (likumi.lv), captured 2026-10-13

What this calendar does not list

  • Not yet covered Periodic return — Two Latvian filings are not modelled. Persons who owe VAT without being registered (new means of transport, auctions, or a business over the threshold not yet registered), and persons with a special registration under s.139², file a payment notice (paziņojums par PVN samaksu) within 20 days after the month of the transaction and pay within 3 working days of filing (VAT Law ss.117(8), 118(10), 119(5)); whether the return shift reaches it was not researched. Electricity tax and natural-resources tax are levied under separate laws whose deadlines were not researched.

About this calendar

Which Latvia tax deadlines does this calendar cover?

17 recurring indirect-tax obligations — Pievienotās vērtības nodoklis (PVN / VAT), Strukturēti elektroniskie rēķini (e-invoicing) and Akcīzes nodoklis (excise duty) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-13). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.