European Commission objects to extending Latvia's timber reverse-charge derogation beyond 31 December 2026
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Latvia as they stand today, see the Latvia guide →
- Jurisdiction
- Latvia
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Plan ahead
- Announced
- 29 September 2026
- Effective
- 1 January 2027
- Authority
- Council of the European Union
- Systems
- ERP, Invoicing, Tax engine
- Verified
- Fetched from official source · high confidence
Latvian suppliers and buyers of timber and related services that currently apply the VAT reverse charge under the Article 395 derogation.
Latvian timber suppliers and buyers: plan for standard (non-reverse-charge) VAT invoicing from 1 January 2027 unless the Council authorises an extension.
ERPInvoicingTax engine
The European Commission communicated to the Council on 29 September 2026 (COM(2026) 511 final, Council doc. 13782/26) that it objects to Latvia's request of 28 May 2026 to extend beyond 31 December 2026 the Article 395 derogation from Article 193 of the VAT Directive allowing the reverse charge on supplies of timber and related services. The derogation has applied since Latvia's accession and currently runs to 31 December 2026 under Council Implementing Decision (EU) 2024/3207; no Council decision extending it has been adopted.
What changed in detail
This is a position of the European Commission, not a Council decision, and the outcome is still open. On 29 September 2026 the Commission communicated to the Council (COM(2026) 511 final, Council document 13782/26) that it objects to Latvia’s request of 28 May 2026 to extend beyond 31 December 2026 the Article 395 derogation from Article 193 of the VAT Directive.
The derogation allows the reverse charge on supplies of timber and related services. It has applied since Latvia’s accession and currently runs to 31 December 2026 under Council Implementing Decision (EU) 2024/3207. No Council decision extending it has been adopted.
What it means
A Commission objection does not by itself end the derogation, because the decision rests with the Council. But the current authorisation expires on 31 December 2026, so unless the Council authorises an extension, standard (non-reverse-charge) VAT invoicing would apply to these supplies from 1 January 2027.
Latvian timber suppliers and buyers should plan for both outcomes: keep reverse-charge invoicing until year-end, and prepare ERP and tax-engine settings for a switch to standard invoicing on 1 January 2027. Watch for a Council decision before the end of the year.
Proof
Based on the above-mentioned arguments, the Commission objects to the request made by Latvia.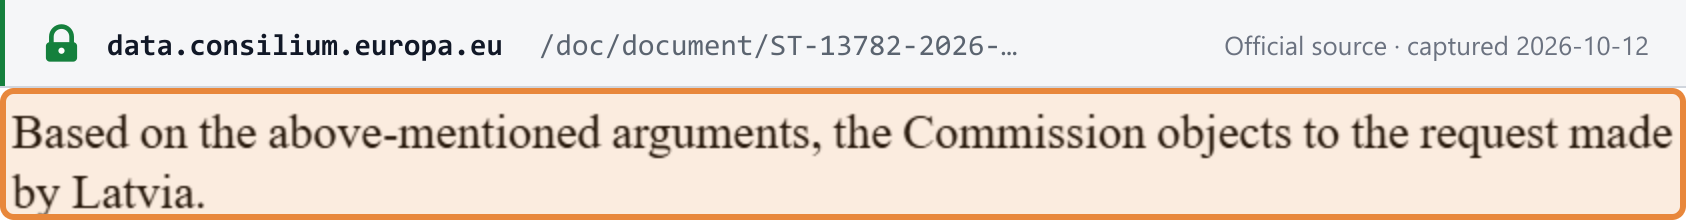 Source snapshot of the official page. Open full size ↗