Lithuania compliance calendar

14 recurring Pridėtinės vertės mokestis (PVM / VAT) and Akcizai (excise duties) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Lithuania rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
28
29
30
1
2
3
4
5
6
7
8
Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Lithuania applies one — 8 of 14 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

PVM deklaracija (FR0600) — monthly

Pridėtinės vertės mokestis (PVM / VAT) · Monthly · return filing

25th of the month after the month ends Verified 2026-10-08
Who files
VAT payers on the default calendar-month period — every legal person not authorised to file quarterly, and anyone who acquires goods from other EU member states or self-accounts for VAT on services bought from EU suppliers
Notes
File through VMI's EDS by the 25th of the next month, every month, including months with nothing to declare. The VAT itself is payable by the same deadline. Because 25 December is a holiday, the November return is due later than usual: Monday 28 December in 2026 and Monday 27 December in 2027. Remember that i.SAF invoice-register data for the same month is due earlier, on the 20th.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 85 straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“Jeigu mokestinis laikotarpis yra kalendorinis mėnuo, mokestinio laikotarpio PVM deklaracija turi būti pateikta ne vėliau kaip iki kito mėnesio 25 dienos.”
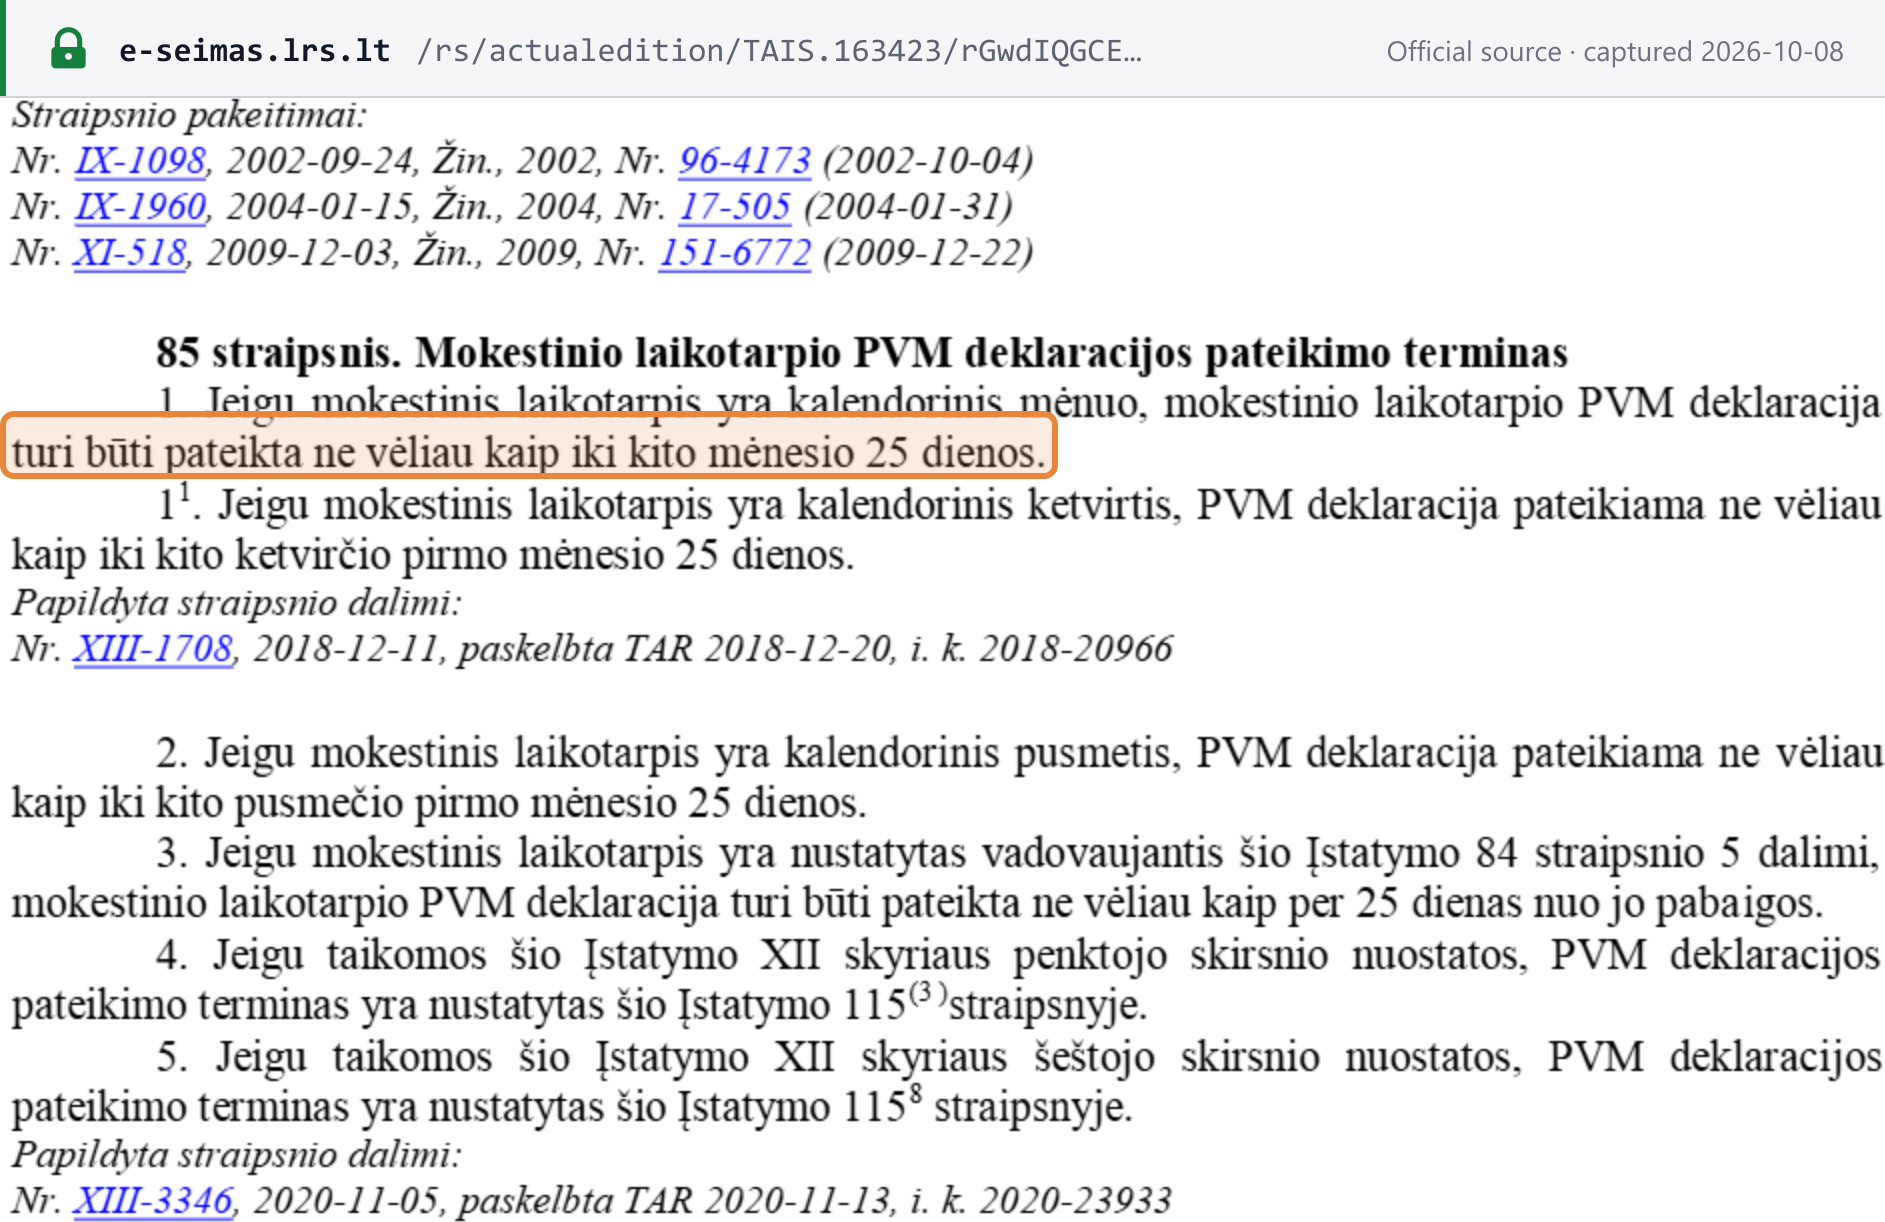
Screenshot of Lietuvos Respublikos Seimas showing the PVM deklaracija (FR0600) — monthly deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
PVM deklaracija (FR0600) — quarterly

Pridėtinės vertės mokestis (PVM / VAT) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-08
Who files
VAT payers other than natural persons whose income from economic activity last year did not exceed EUR 300,000 and that applied to VMI for quarterly periods; not available to businesses that acquire goods from other member states or self-account for VAT on services bought from EU suppliers
Notes
Smaller companies can ask to file once a quarter, by the 25th of the month after the quarter ends — Monday 26 October 2026 for the third quarter, since the 25th is a Sunday. The option is closed to businesses that buy goods from other EU countries, or buy services from EU suppliers and account for the VAT on them themselves. Quarterly filers still send i.SAF data every month.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 85 straipsnis, 1¹ dalis (su 84 str. 2 d.) Lietuvos Respublikos Seimas
See the source text
“Jeigu mokestinis laikotarpis yra kalendorinis ketvirtis, PVM deklaracija pateikiama ne vėliau kaip iki kito ketvirčio pirmo mėnesio 25 dienos.”
Screenshot of Lietuvos Respublikos Seimas showing the PVM deklaracija (FR0600) — quarterly deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
PVM deklaracija (FR0600) — half-yearly (natural persons)

Pridėtinės vertės mokestis (PVM / VAT) · Bi-annually · return filing

25th of the month after the half-year ends Verified 2026-10-08
Who files
Natural persons registered for VAT, unless they applied for monthly periods
Notes
Self-employed individuals registered for VAT file twice a year by default: January–June by 25 July and July–December by 25 January. In 2027 the July deadline moves to Monday the 26th because the 25th is a Sunday. The half-yearly period is not available to individuals who buy goods from other EU countries, or buy services from EU suppliers and account for the VAT on them themselves.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 85 straipsnis, 2 dalis (su 84 str. 4 d.) Lietuvos Respublikos Seimas
See the source text
“Jeigu mokestinis laikotarpis yra kalendorinis pusmetis, PVM deklaracija pateikiama ne vėliau kaip iki kito pusmečio pirmo mėnesio 25 dienos.”
Screenshot of Lietuvos Respublikos Seimas showing the PVM deklaracija (FR0600) — half-yearly (natural persons) deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
Metinė PVM deklaracija (FR0516) — annual return for deduction adjustments

Pridėtinės vertės mokestis (PVM / VAT) · Annually · return filing

1st October each year Verified 2026-10-08
Who files
Only VAT payers that must adjust their input-VAT deduction to the year's actual figures — mixed taxable and exempt activity, or capital assets not used wholly for taxable activity
Notes
This is not a summary of the year's returns. It is where a business that deducted input VAT provisionally — because it makes both taxable and exempt supplies, or uses an asset partly for exempt purposes — settles the deduction on the year's actual figures. It is due by 1 October of the following year, together with annex FR0516A where required, and any extra VAT is payable by the same day. In 2028 the date moves to Monday 2 October.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 87 straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
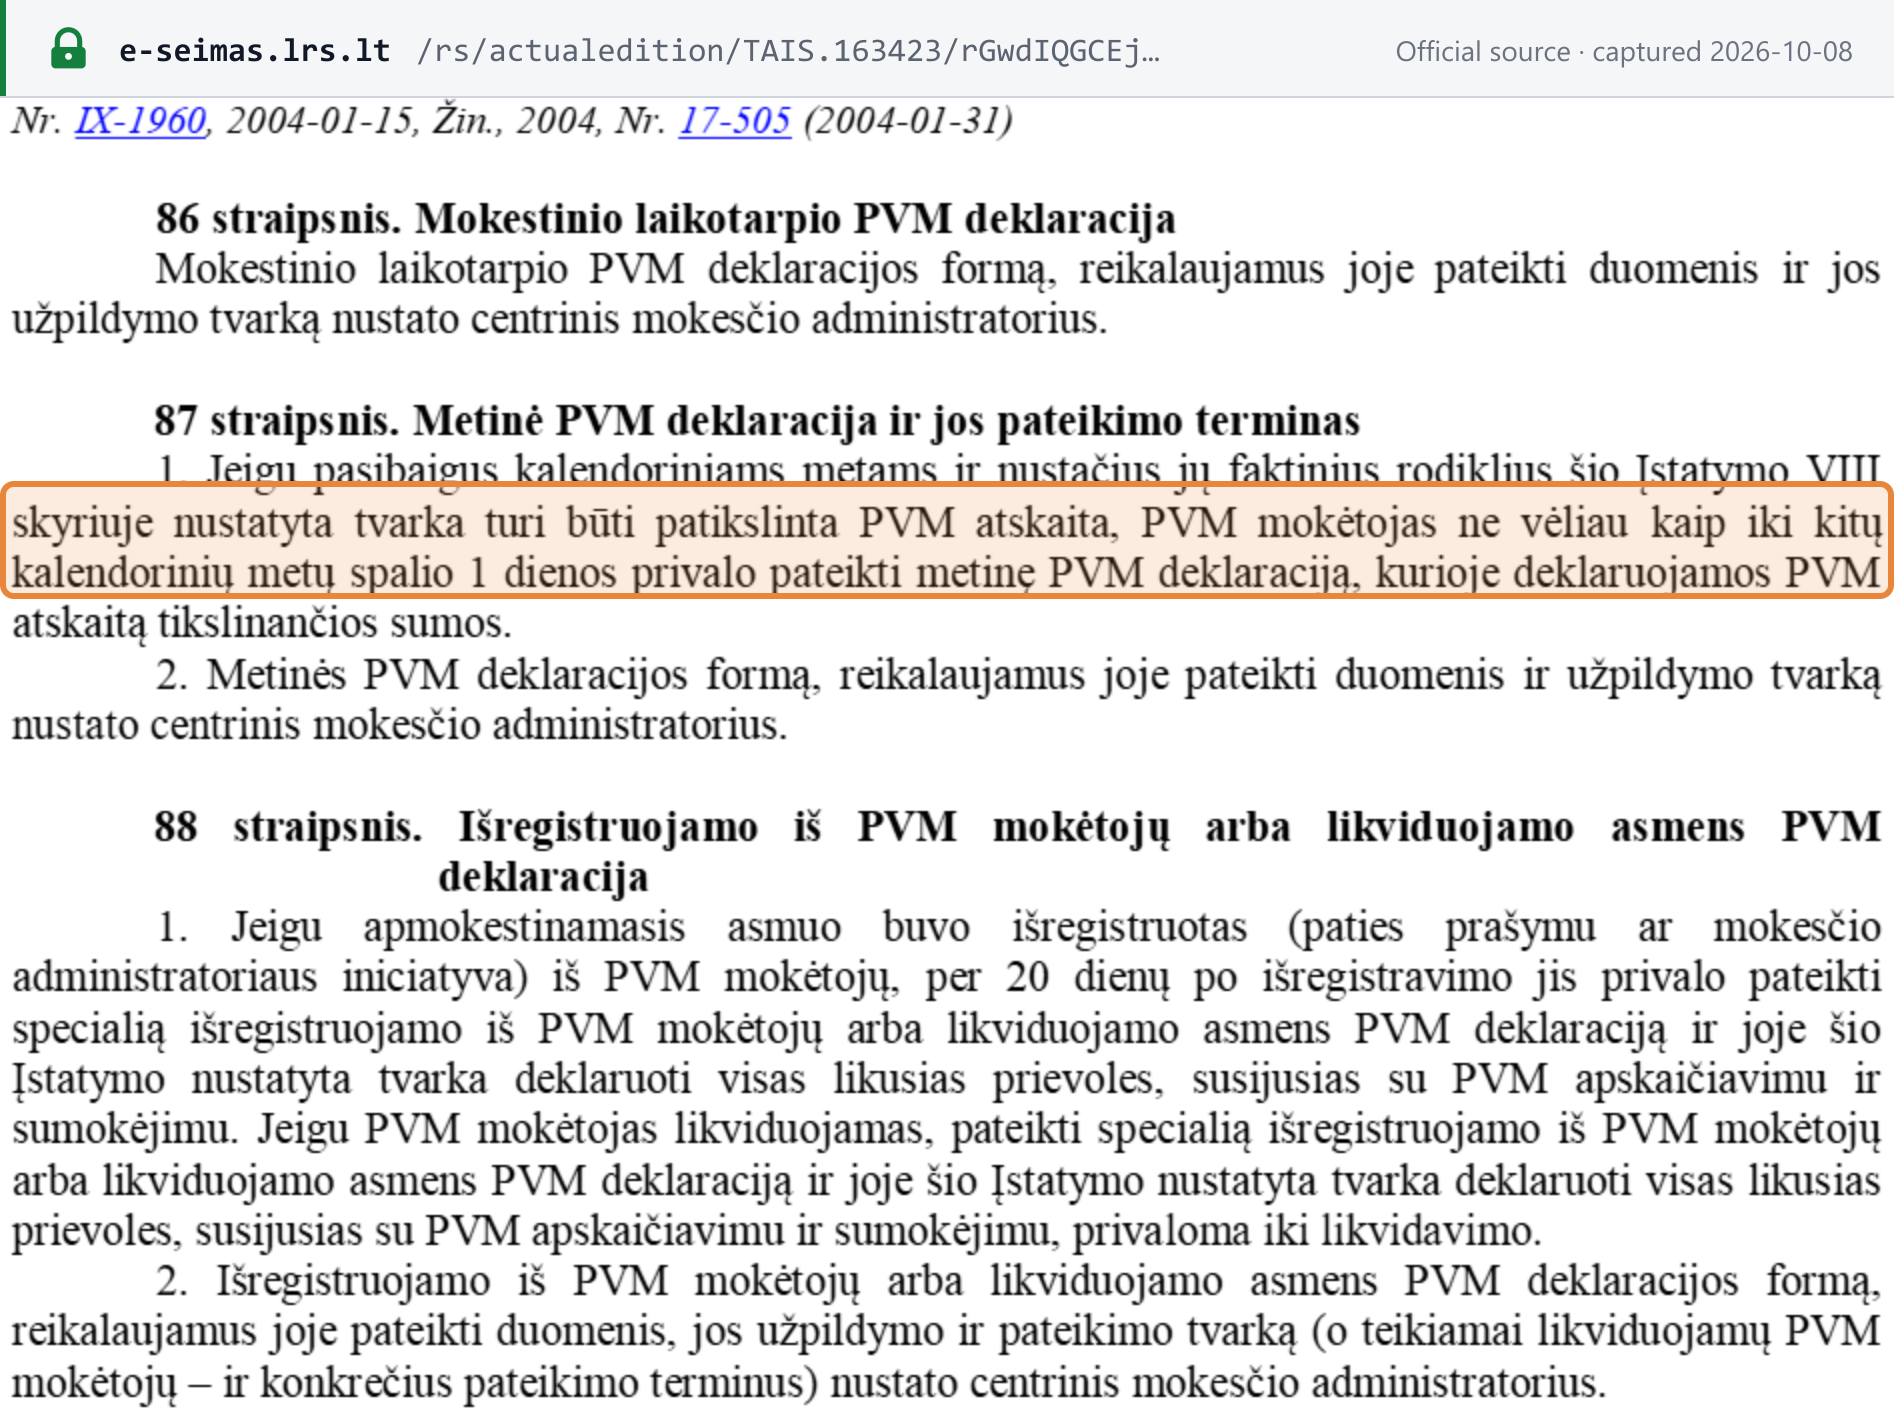
“PVM mokėtojas ne vėliau kaip iki kitų kalendorinių metų spalio 1 dienos privalo pateikti metinę PVM deklaraciją, kurioje deklaruojamos PVM atskaitą tikslinančios sumos.”
Screenshot of Lietuvos Respublikos Seimas showing the Metinė PVM deklaracija (FR0516) — annual return for deduction adjustments deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
Prekių tiekimo ir paslaugų teikimo į kitas ES valstybes nares ataskaita (FR0564)

Pridėtinės vertės mokestis (PVM / VAT) · Monthly · report / listing

25th of the month after the month ends Verified 2026-10-08
Who files
VAT payers supplying goods to other EU member states, making triangular or call-off-stock movements, or supplying reverse-charged B2B services in the month; small-business-scheme members only for those services
Notes
Lithuania's EC Sales List is monthly only — there is no quarterly option and no threshold — and it shares the VAT return's 25th. After deregistration, the last month's listing is due within 20 days.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 88¹ straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
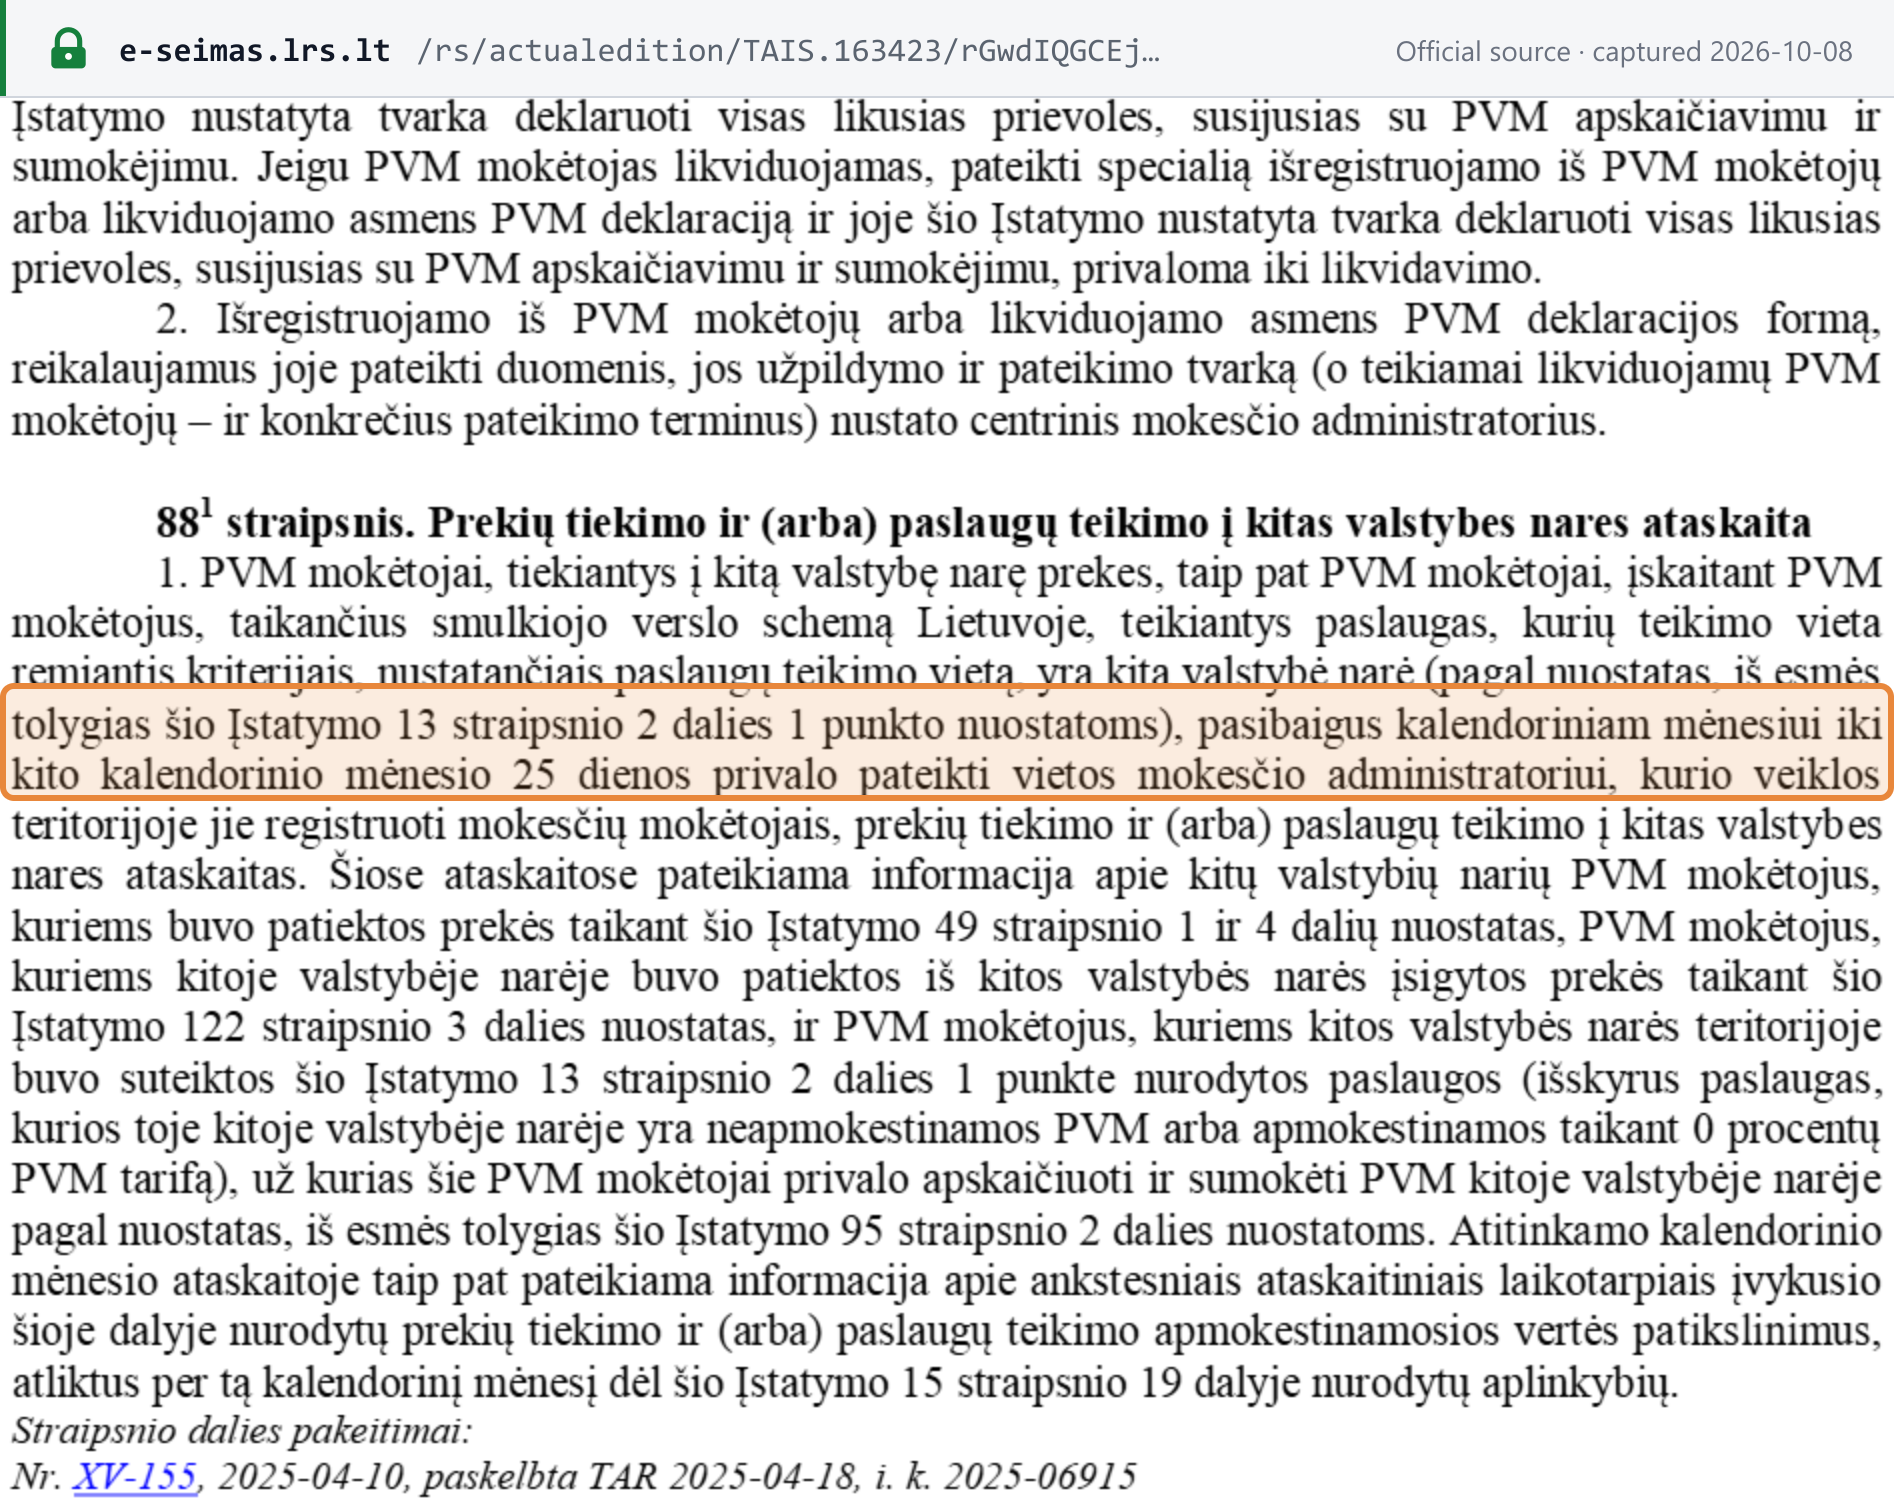
“pasibaigus kalendoriniam mėnesiui iki kito kalendorinio mėnesio 25 dienos privalo pateikti vietos mokesčio administratoriui”
Screenshot of Lietuvos Respublikos Seimas showing the Prekių tiekimo ir paslaugų teikimo į kitas ES valstybes nares ataskaita (FR0564) deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
i.SAF — VAT invoice-register data, natural persons on half-yearly returns

Pridėtinės vertės mokestis (PVM / VAT) — i.SAF · Bi-annually · report / listing

20th of the month after the half-year ends Verified 2026-10-08
Who files
Natural persons registered for VAT who file half-yearly returns (natural persons filing monthly follow the monthly 20th)
Notes
Individuals follow their VAT return cycle for i.SAF: a half-yearly filer sends each half-year's invoice-register data by 20 July and 20 January. As for companies, VMI has not said whether a weekend 20th moves, so submit by the preceding working day.
Source
VMI — i.SAF: duomenų teikimas, tikslinimas (VMI answer KM1886) Valstybinė mokesčių inspekcija
See the source text
“Jeigu teikia kalendorinio pusmečio PVM deklaraciją – iki kito pusmečio pirmo mėnesio 20 dienos;”
Screenshot of Valstybinė mokesčių inspekcija showing the i.SAF — VAT invoice-register data, natural persons on half-yearly returns deadline Open full size Captured from Valstybinė mokesčių inspekcija on 2026-09-23

PVM mokėtoju neįregistruoto asmens PVM apyskaita (FR0608) — statement for persons not registered for VAT

Pridėtinės vertės mokestis (PVM / VAT) · Monthly · return filing

25th of the month after the month ends Verified 2026-10-08
Who files
Persons liable for Lithuanian VAT who are not registered as VAT payers — including those who should have registered and non-registered customers self-accounting under art. 95 — only for months with a liability
Notes
If you owe Lithuanian VAT without being registered — because you should have registered and did not, or because you are an unregistered customer accounting for VAT on a purchase yourself — you report and pay it on this statement by the 25th of the following month, for each month in which you owed any.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 92 straipsnis, 3 dalis Lietuvos Respublikos Seimas
See the source text
“iki kito mėnesio 25 dienos pateikdami centrinio mokesčio administratoriaus nustatytos formos PVM mokėtoju neįregistruoto asmens PVM apyskaitą”
Captured from Lietuvos Respublikos Seimas on 2026-10-08
PVM deklaracija — ne ES schema (non-Union OSS)

Pridėtinės vertės mokestis (PVM / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Non-EU businesses registered in Lithuania for the non-Union OSS scheme (B2C services to EU consumers)
Notes
A quarterly return is due by the last day of the month after each quarter, even when nothing was supplied, and the VAT is paid by the same day. The deadline does not move when it falls on a weekend or holiday — the third quarter of 2026 is due Saturday 31 October — so file on the last working day before it.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 115³ straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“pasirinkęs taikyti Europos Sąjungoje neįsikūrusių asmenų schemą, kiekvienam kalendoriniam ketvirčiui pasibaigus iki kito ketvirčio pirmo mėnesio paskutinės dienos privalo pateikti PVM deklaraciją.”
Screenshot of Lietuvos Respublikos Seimas showing the PVM deklaracija — ne ES schema (non-Union OSS) deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
PVM deklaracija — ES schema (Union OSS)

Pridėtinės vertės mokestis (PVM / VAT) — One Stop Shop · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Businesses registered in Lithuania for the Union OSS scheme (intra-EU distance sales of goods and B2C services taxed in other member states)
Notes
Businesses using Lithuania as their member state of identification for the Union scheme file every quarter, nil returns included, by the end of the following month, paying on the same day. Unlike the domestic return, a Saturday or Sunday deadline is not pushed to Monday: the last quarter of 2026 is due Sunday 31 January 2027.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 115⁸ straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“pasirinkęs taikyti Europos Sąjungoje įsikūrusių asmenų schemą, kiekvienam kalendoriniam ketvirčiui pasibaigus iki kito ketvirčio pirmo mėnesio paskutinės dienos privalo pateikti PVM deklaraciją.”
Screenshot of Lietuvos Respublikos Seimas showing the PVM deklaracija — ES schema (Union OSS) deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
PVM deklaracija — importo schema (IOSS)

Pridėtinės vertės mokestis (PVM / VAT) — Import One Stop Shop · Monthly · return filing

last day of the month after the month ends Verified 2026-10-08
Who files
Sellers and import intermediaries registered in Lithuania for IOSS (distance sales of imported goods in consignments up to EUR 150)
Notes
Monthly, and owed even for a month with no sales: the return and the VAT are due by the last calendar day of the next month, with no extension when that day is a weekend — January 2027's return is due Sunday 28 February.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 115¹³ straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“kiekvienam kalendoriniam mėnesiui pasibaigus iki kito mėnesio, einančio po pasibaigusio mokestinio laikotarpio, už kurį teikiama deklaracija, paskutinės dienos privalo pateikti PVM deklaraciją.”
Screenshot of Lietuvos Respublikos Seimas showing the PVM deklaracija — importo schema (IOSS) deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
ES smulkiojo verslo schemos ketvirtinė ataskaita — EU cross-border SME scheme report

Pridėtinės vertės mokestis (PVM / VAT) — EU SME scheme · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-08
Who files
Lithuanian small businesses registered to use other member states' VAT exemption under the EU cross-border SME scheme (EX-suffixed number)
Notes
Small businesses using the EU-wide exemption report their turnover every quarter by the last day of the following month, whether or not they traded. When the month ends on a weekend or holiday the date moves to the next working day — Tuesday 3 November 2026, after the All Saints' and All Souls' holidays. Crossing the EUR 100,000 EU turnover ceiling triggers an extra report within 15 working days.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 88³ straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“iki kito ketvirčio pirmo mėnesio paskutinės dienos mokesčio administratoriui privalo pateikti ataskaitą (neatsižvelgdamas į tai, ar faktiškai vykdyta ekonominė veikla)”
Screenshot of Lietuvos Respublikos Seimas showing the ES smulkiojo verslo schemos ketvirtinė ataskaita — EU cross-border SME scheme report deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08
Akcizų deklaracija — monthly excise return and payment

Akcizai (excise duties) · Monthly · return filing

15th of the month after the month ends Verified 2026-10-08
Who files
Excise warehouse keepers, registered consignees and consignors and certified consignees; the same 15th applies separately to electricity, coal and coke, natural gas, heated tobacco, e-cigarette liquid, raw tobacco and sweetened drinks
Notes
Excise runs on calendar months, with one return per warehouse due by the 15th of the next month and the duty payable by the same day. Larger payers — over EUR 15,000 a month on average for a warehouse across the last three periods — also pay an advance of a third of that average by the 15th of the current month. Sweetened drinks joined the excise list on 1 January 2026.
Source
Akcizų įstatymas (Nr. IX-569), suvestinė redakcija nuo 2026-06-16 — 10 straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“Jam pasibaigus, iki kito mėnesio 15 dienos akcizais apmokestinamų prekių sandėlio savininkas”
Screenshot of Lietuvos Respublikos Seimas showing the Akcizų deklaracija — monthly excise return and payment deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08

Speciali išregistruojamo iš PVM mokėtojų asmens PVM deklaracija — deregistration return

Pridėtinės vertės mokestis (PVM / VAT) · One-off · registration

within 20 days of deregistration as a VAT payer Verified 2026-10-08
Who files
Every person deregistered as a VAT payer, on request or by VMI (a person being liquidated files before liquidation)
Notes
Leaving the VAT register triggers one last return, due within 20 days, declaring everything still owed; any VAT on it is payable when it is filed. The final EU sales listing and i.SAF data have the same 20 days.
Source
Pridėtinės vertės mokesčio įstatymas (Nr. IX-751), suvestinė redakcija nuo 2026-07-01 — 88 straipsnis, 1 dalis Lietuvos Respublikos Seimas
See the source text
“per 20 dienų po išregistravimo jis privalo pateikti specialią išregistruojamo iš PVM mokėtojų arba likviduojamo asmens PVM deklaraciją”
Screenshot of Lietuvos Respublikos Seimas showing the Speciali išregistruojamo iš PVM mokėtojų asmens PVM deklaracija — deregistration return deadline Open full size Captured from Lietuvos Respublikos Seimas on 2026-10-08

Lithuania's VAT calendar runs on the 25th: returns, payment and the EU sales listing all fall due then, while invoice-register data for i.SAF is due five days earlier, on the 20th. Most deadlines move to the next working day when the 25th is a weekend or public holiday — the November 2026 return is due Monday 28 December because 25 and 26 December are holidays. A business that crosses the EUR 45,000 registration threshold must register and charges VAT from the month the threshold was exceeded. Persons who owe VAT but are not registered file a monthly FR0608 statement instead of the VAT return.

“Tais atvejais, kai paskutinė termino diena tenka ne darbo ar oficialios šventės dienai, termino pabaigos diena laikoma po jos einanti darbo diena.”
Screenshot of the official source stating the rule that governs Lithuania's deadlines
Mokesčių administravimo įstatymas (Nr. IX-2112), suvestinė redakcija nuo 2026-07-01 — 162 straipsnis, 6 dalis — Lietuvos Respublikos Seimas, captured 2026-10-08

What this calendar does not list

  • Not yet covered Periodic return — Purchasers of agricultural produce from farmers under the flat-rate compensation scheme report those purchases on FR0617K, which VMI states is due by the 25th of the following month, with VAT payers submitting i.SAF data exempt. The deadline is set in VMI order VA-29, which could not be fetched (vmi.lt and e-tar.lt Cloudflare-walled on 2026-10-08), so no row is rendered. Event-driven excise returns (art. 10(5)–(8)) are also not modelled.

New Lithuania rules taking effect

Confirmed changes from the weekly scan — each links to its full record with the official source.

About this calendar

Which Lithuania tax deadlines does this calendar cover?

14 recurring indirect-tax obligations — Pridėtinės vertės mokestis (PVM / VAT) and Akcizai (excise duties) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-08). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.