VAT return (article 10) — quarterly
Value Added Tax (VAT) · Quarterly · return filing
15th of the 2nd month after the quarter ends Verified 2026-10-08- Who files
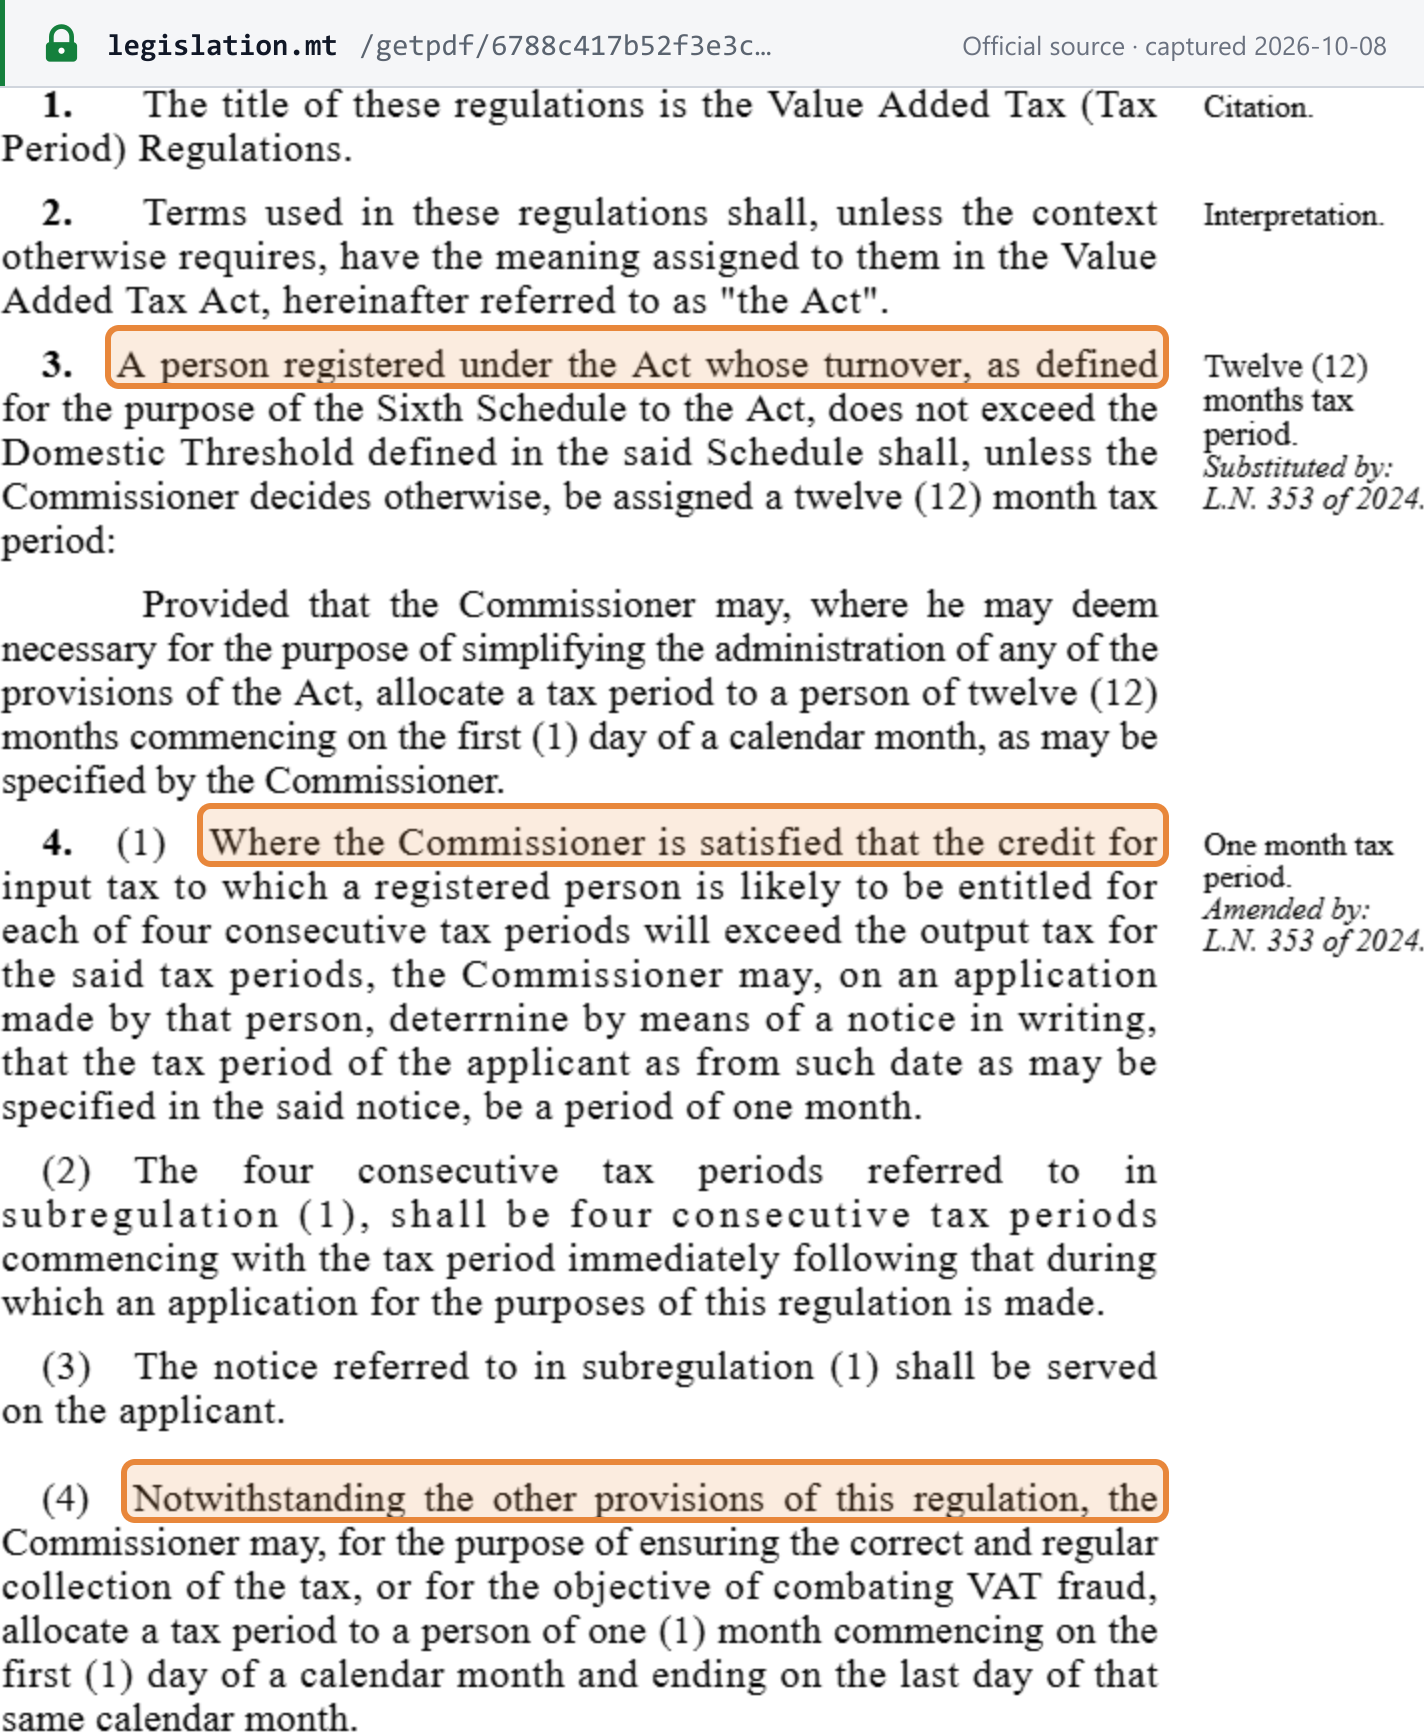
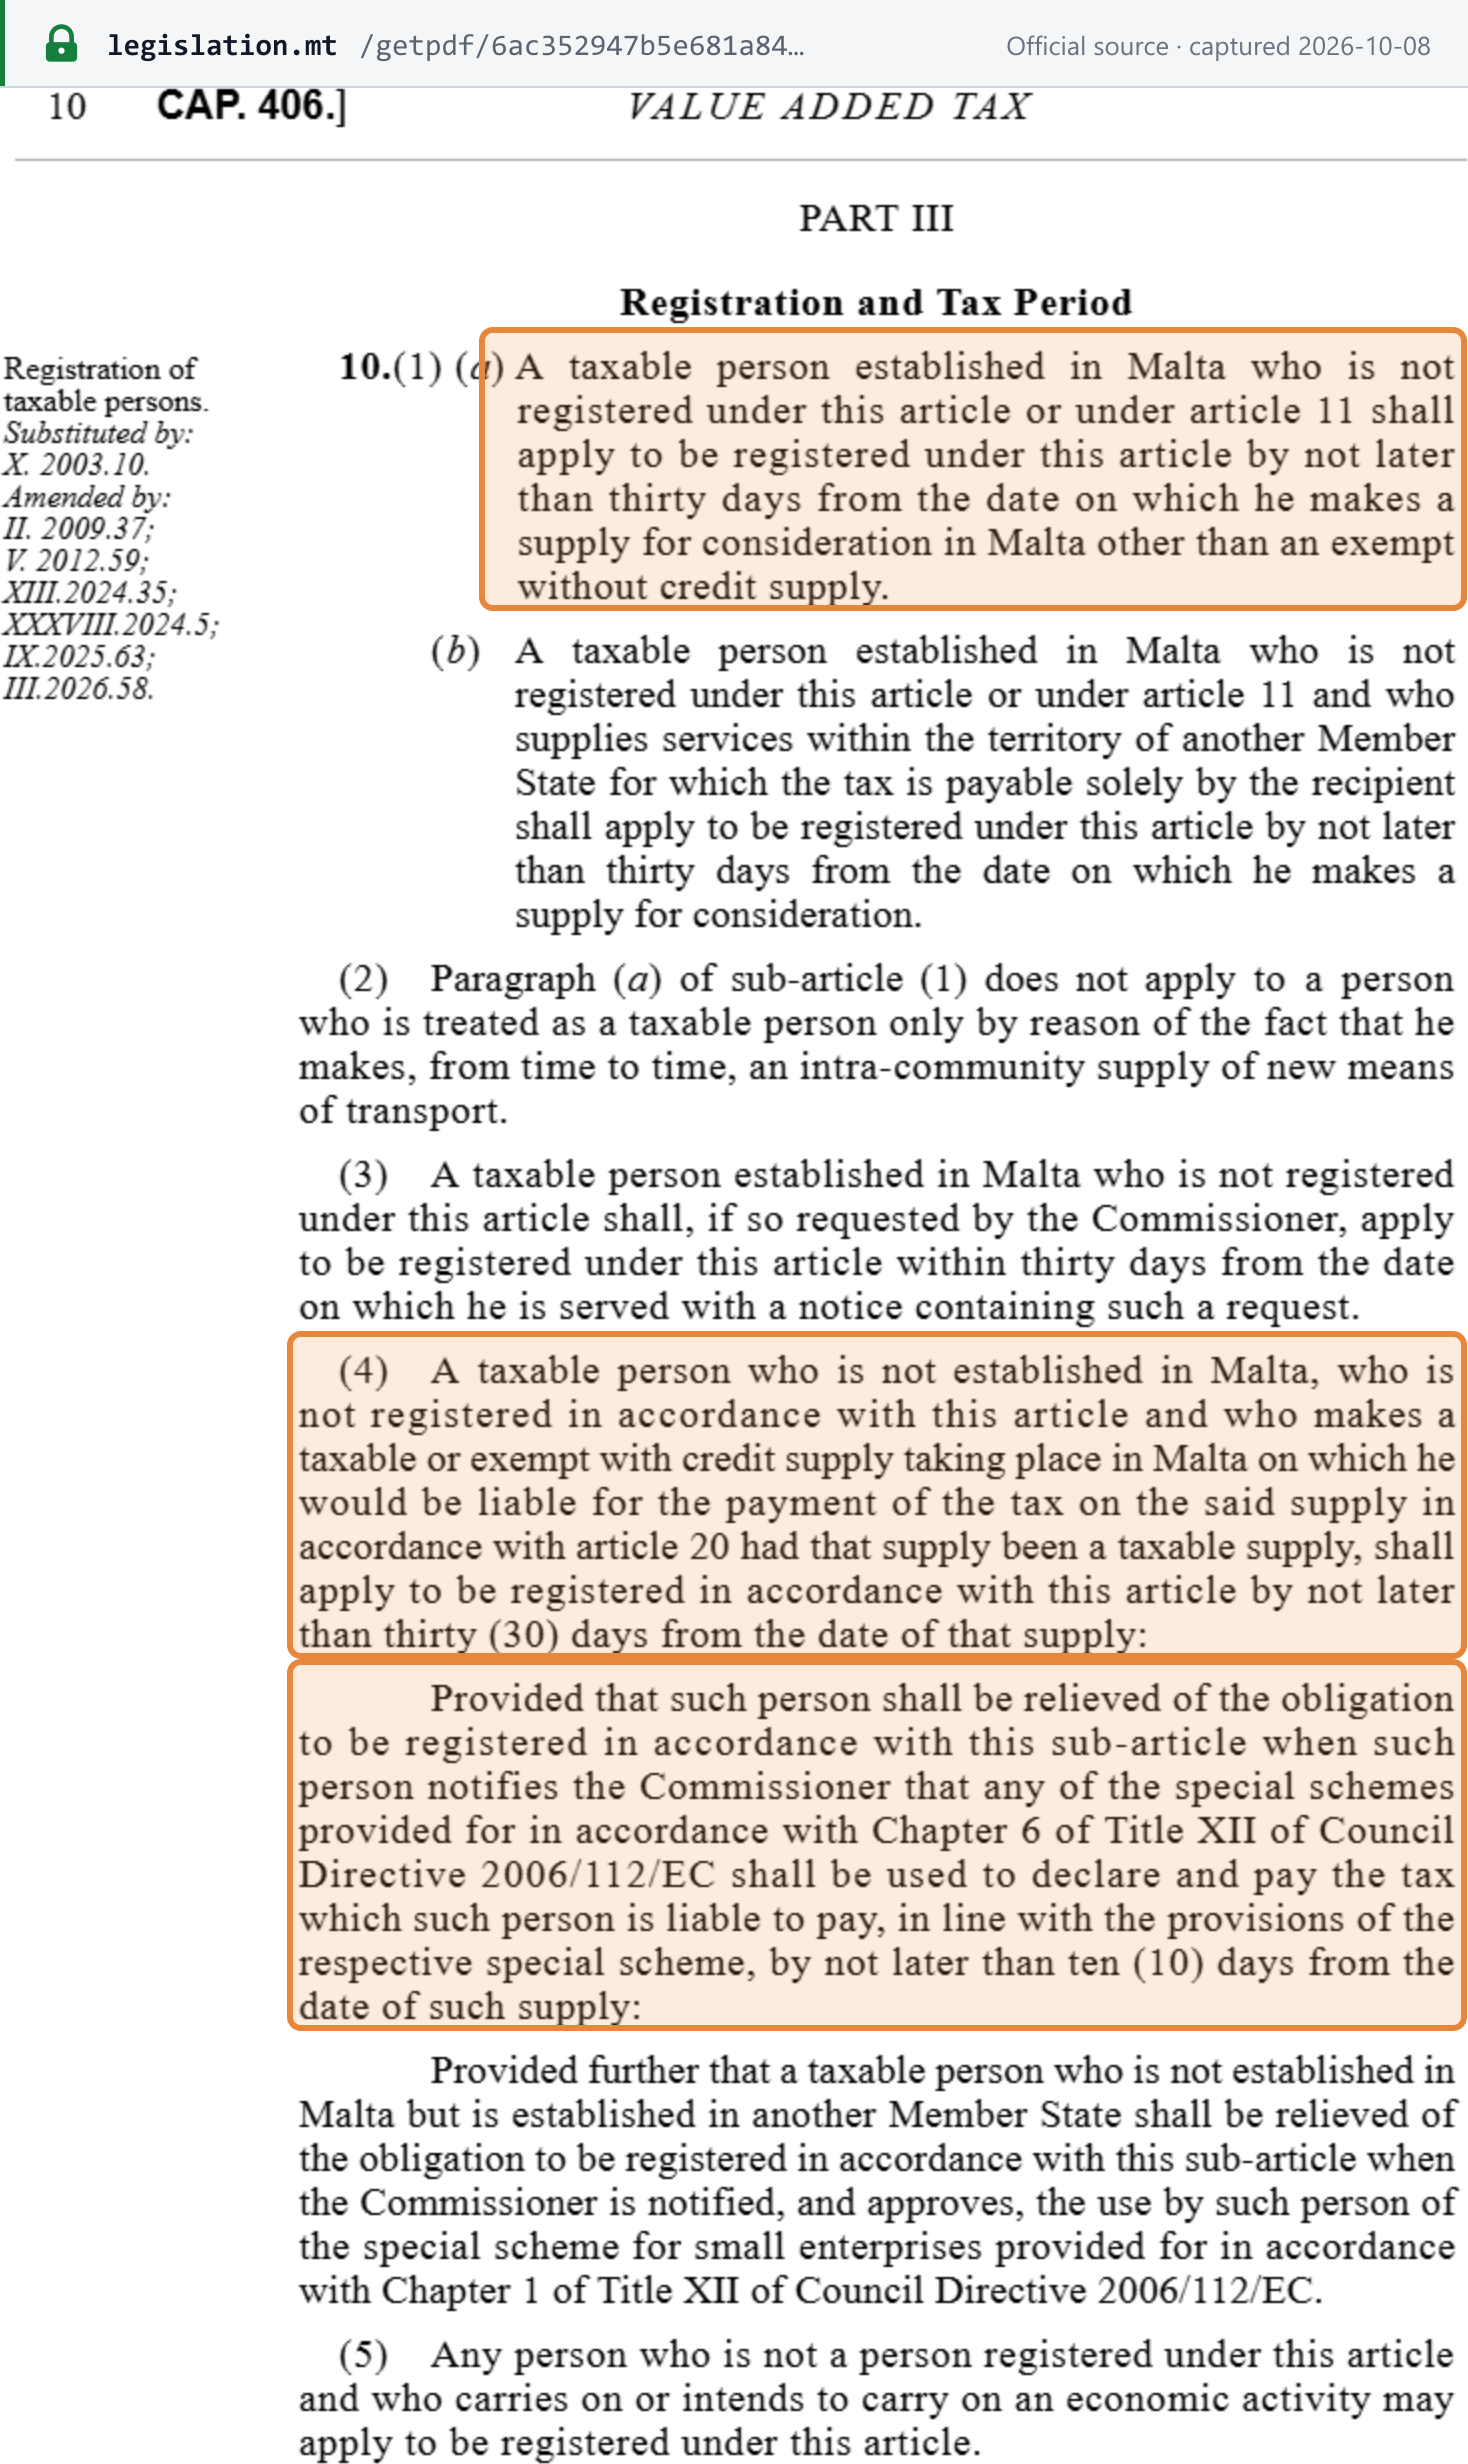
- Businesses registered under article 10 of the VAT Act — the standard registration, which carries the right to deduct input VAT — on the default three-month tax period
- Notes
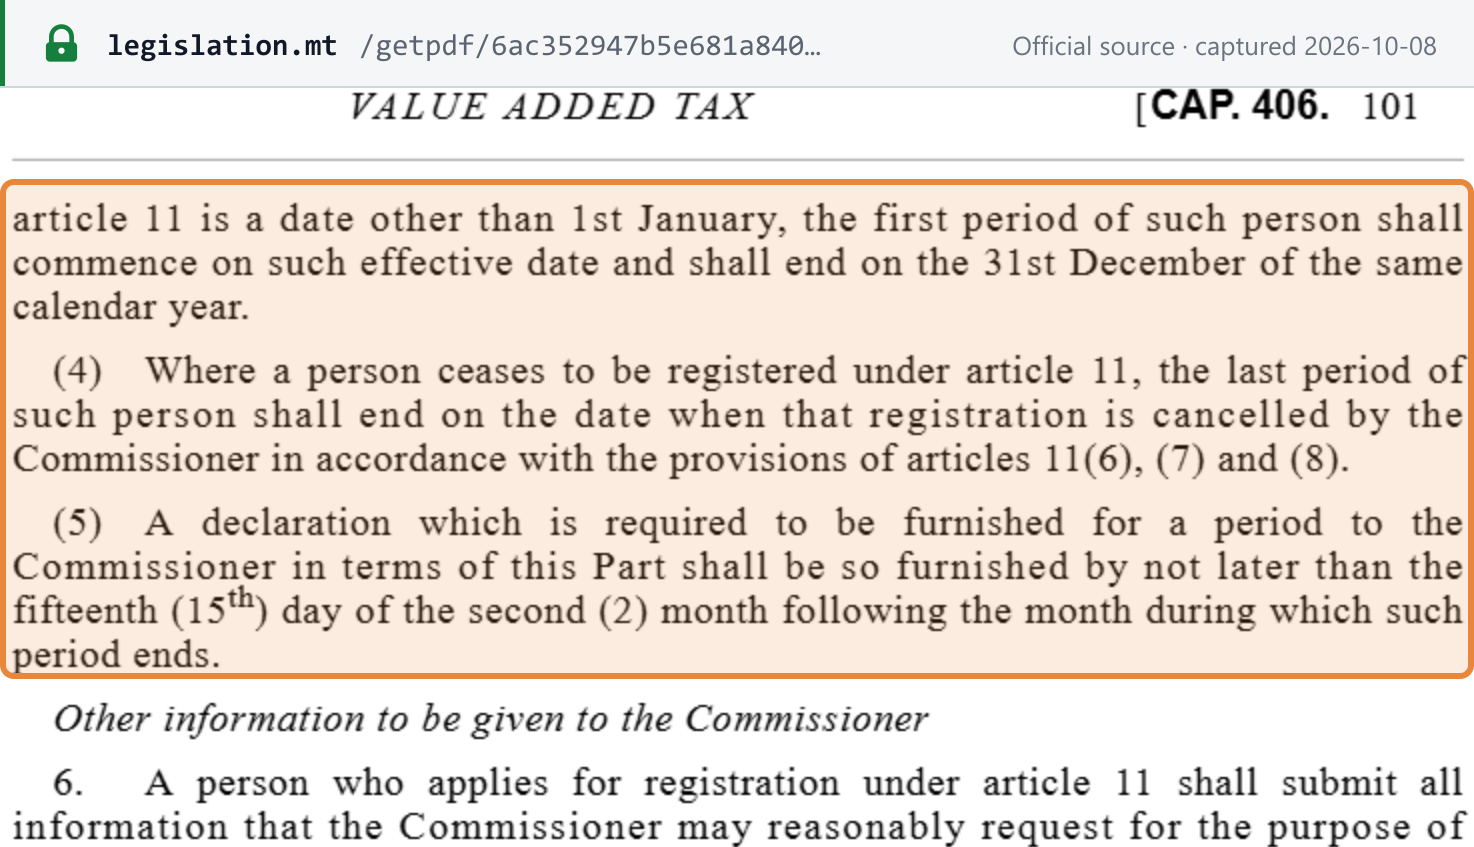
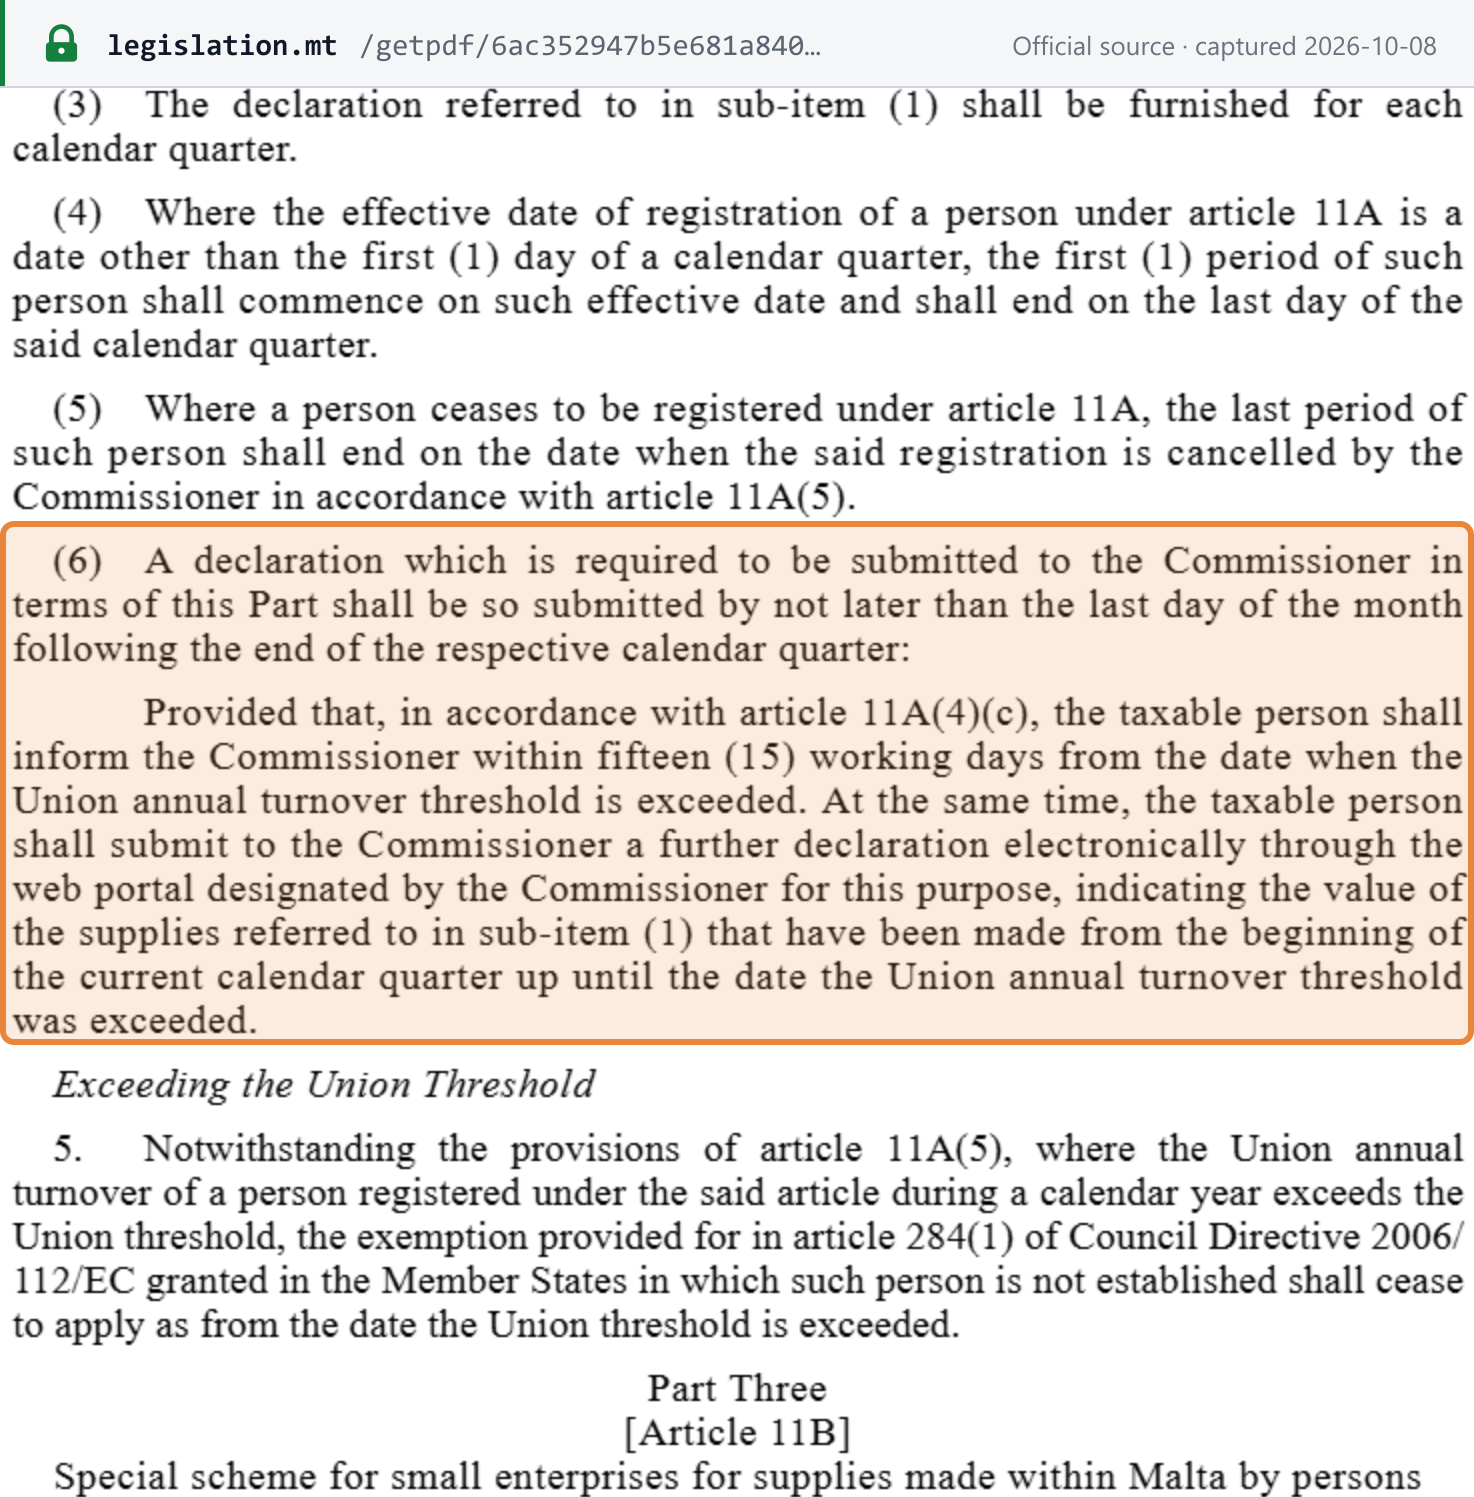
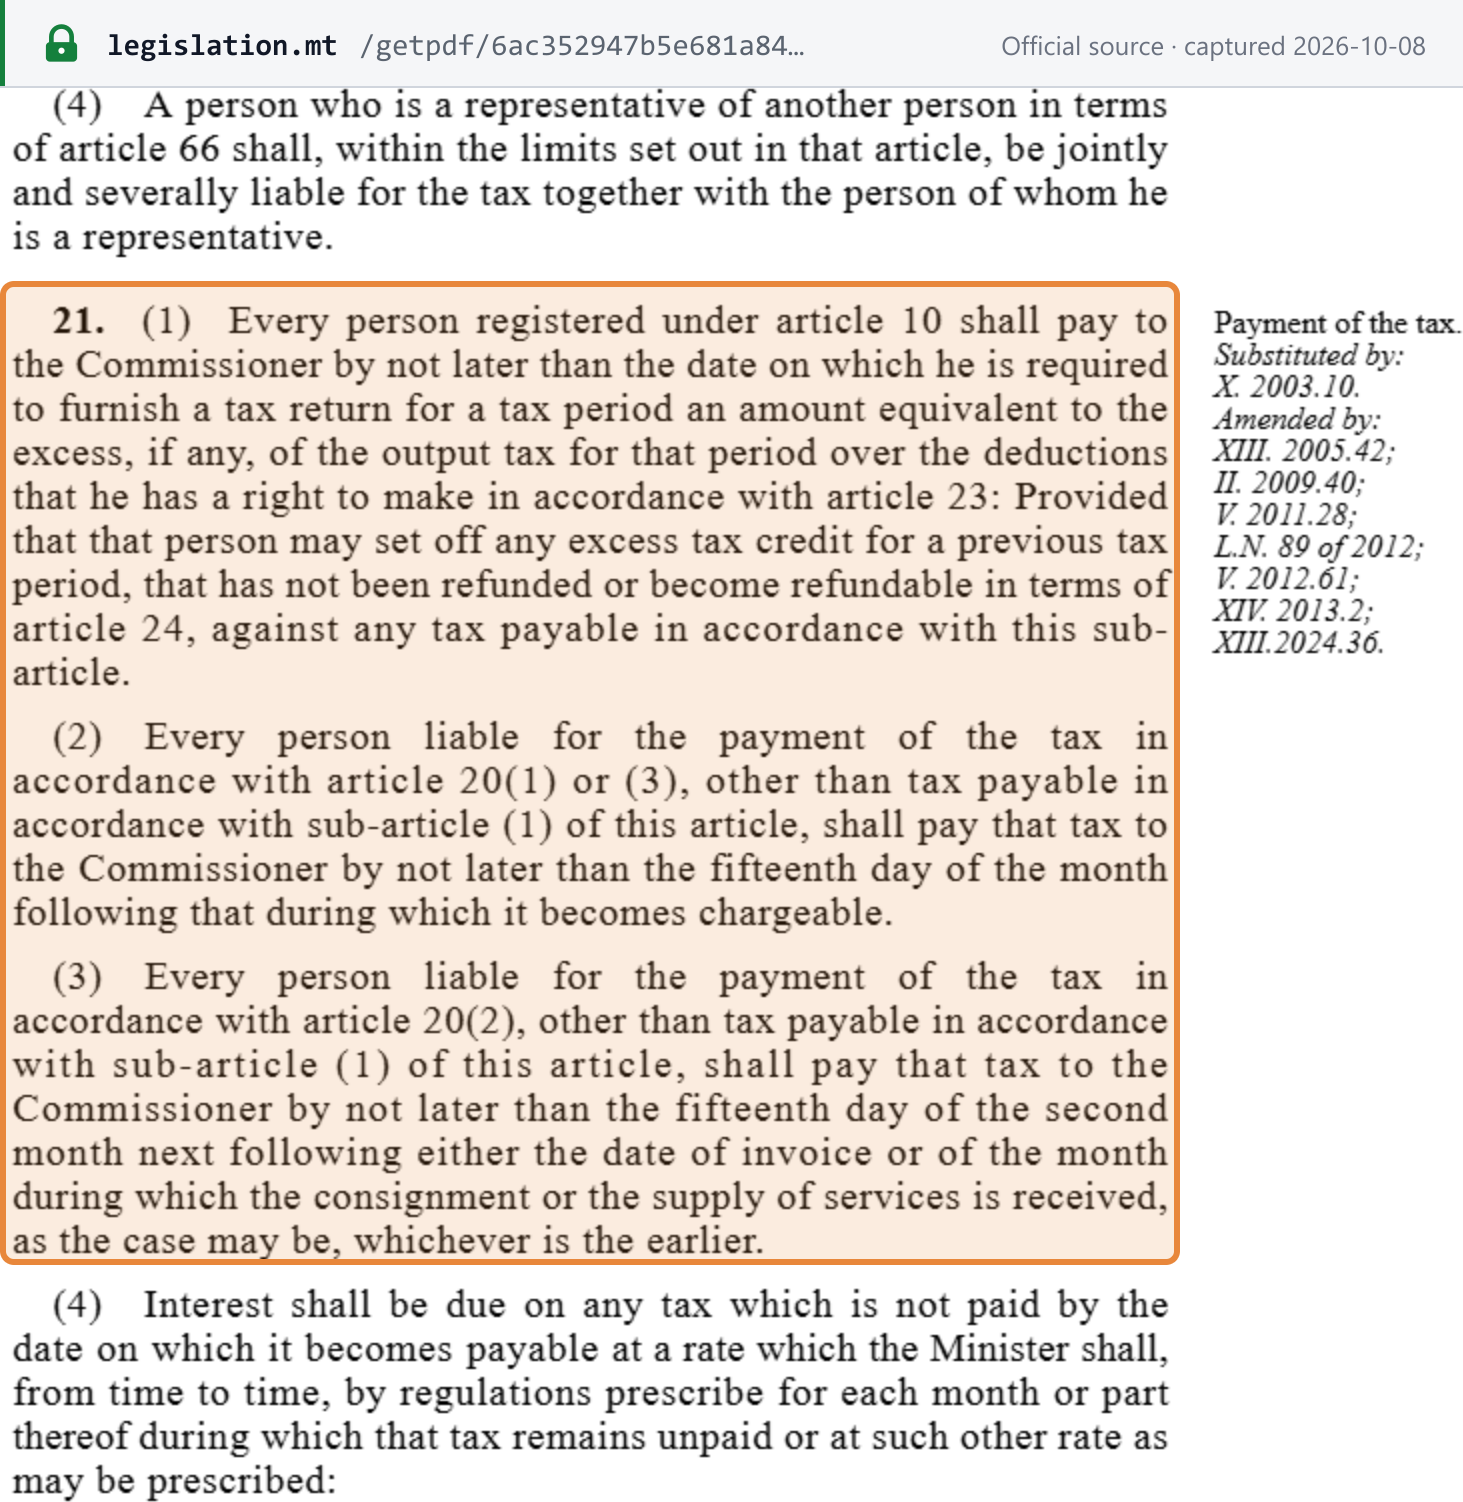
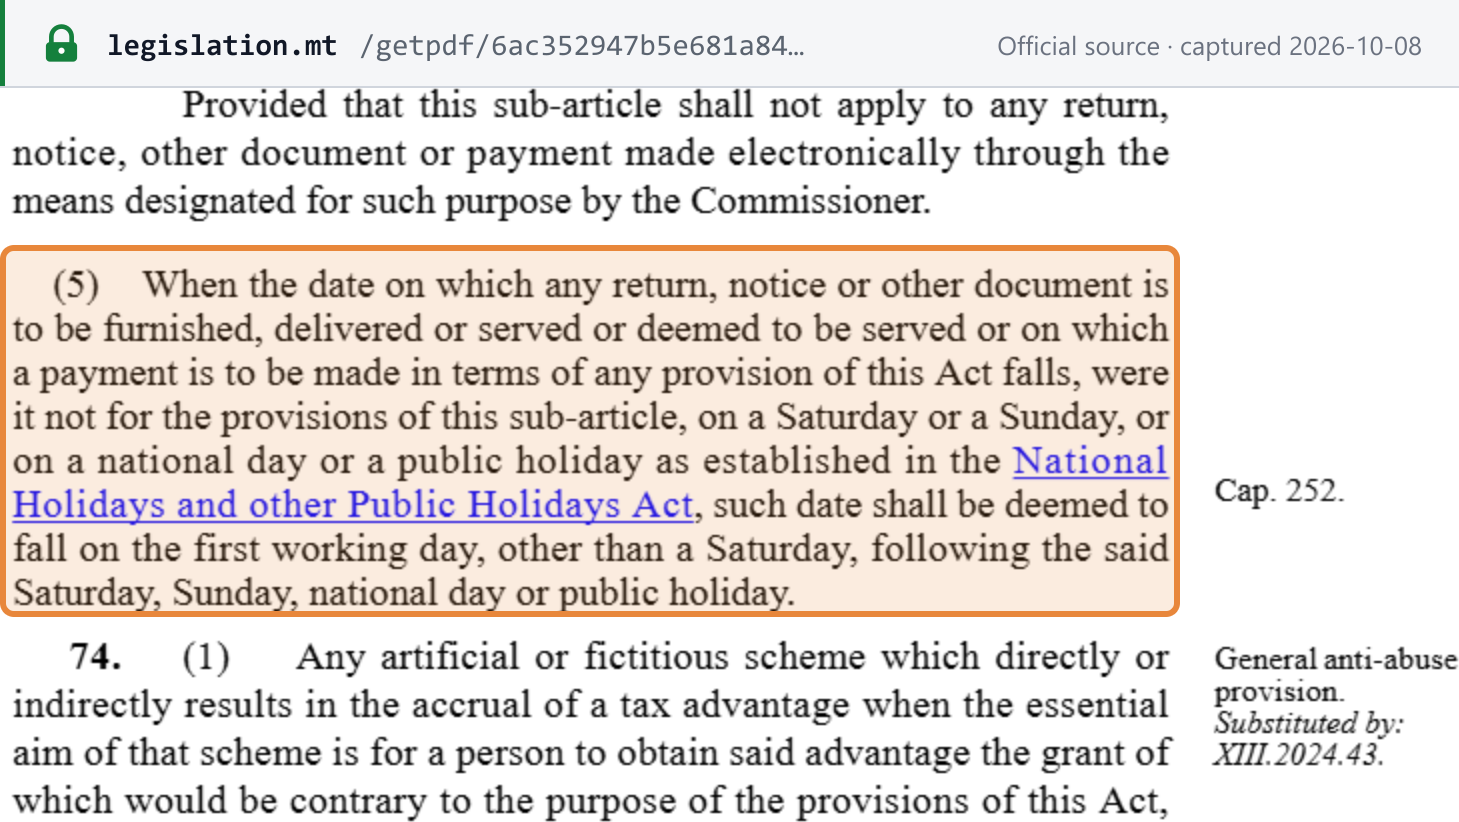
- Most VAT-registered businesses in Malta file every three months, by the 15th of the second month after the quarter ends, and pay any VAT due by the same day. The third quarter of 2026 is due Monday 16 November because the 15th is a Sunday; the second quarter of 2028 is due Wednesday 16 August because the 15th is a public holiday. Your quarters are the ones shown on your VAT registration certificate, which need not be calendar quarters — the due date is always the 15th of the second month after your quarter ends. Filing the return online within seven days of the deadline (MTCA quotes the 22nd) avoids the late-filing penalty; to avoid interest as well, the VAT must be paid with that online return within the same seven days.
- Source
- Value Added Tax Act (Cap. 406), consolidated to Act III of 2026 — article 27(1); payment article 21(1); shift article 73(5) Legislation Malta
See the source text
“by not later than the fifteenth day of the second month following the month during which that tax period ends.”
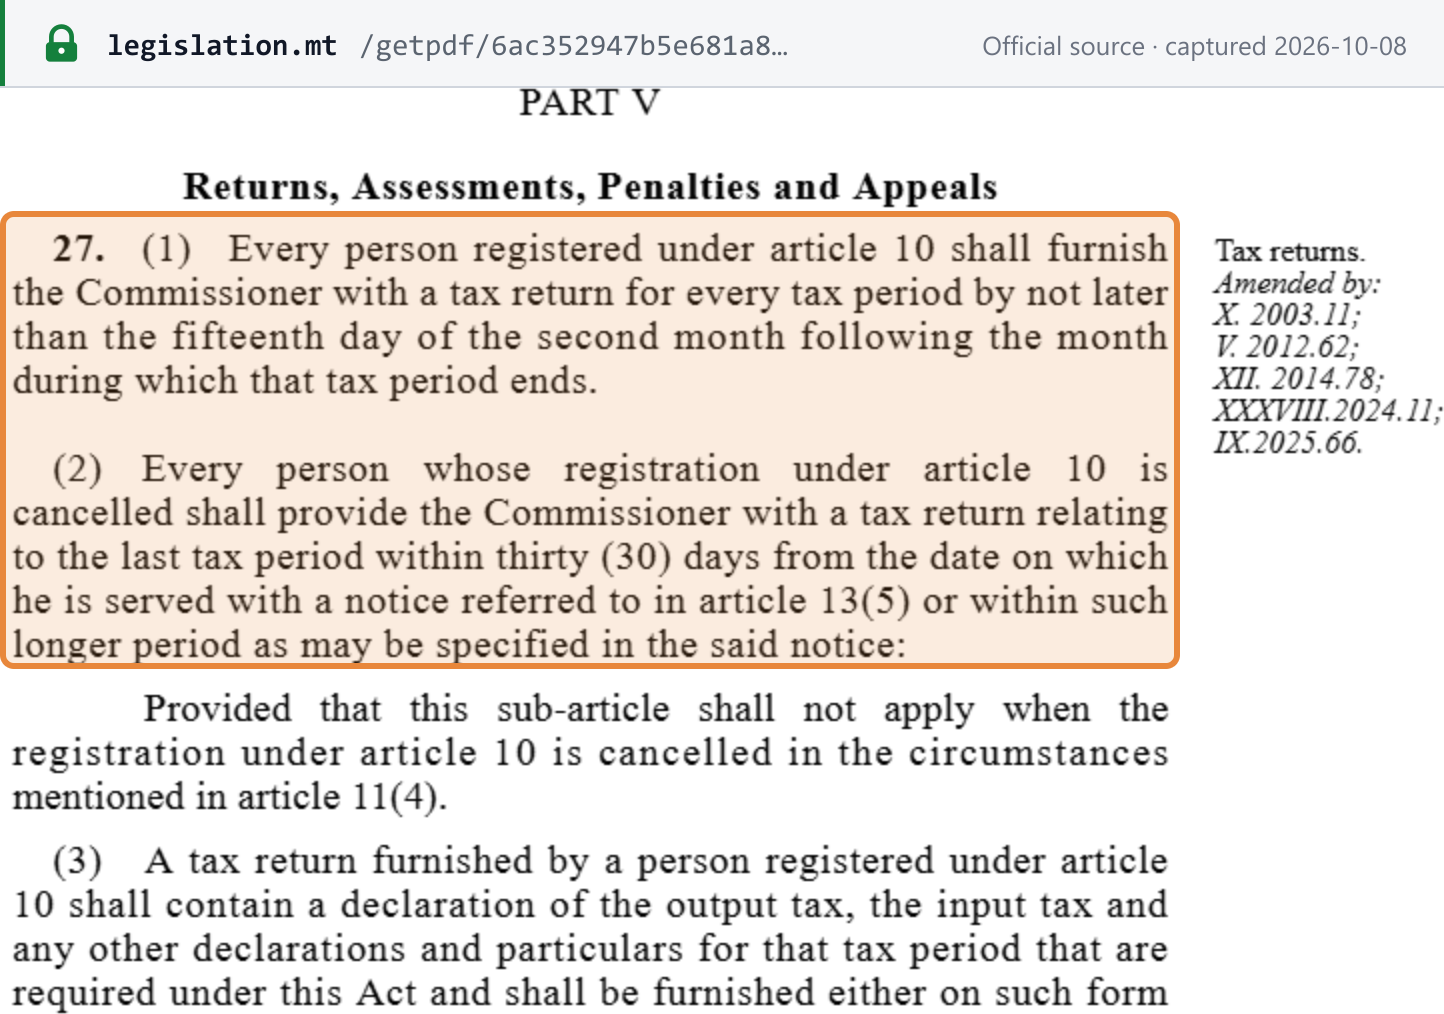 Open full size Captured from Legislation Malta on 2026-10-08