Mauritius compliance calendar

11 recurring VAT, Insurance premium tax and Tourist fee obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Mauritius rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
31
1
2
3
4
5
6
7
8
9
10
11
Return filing Law change takes effect

Dates already include the weekend and public-holiday shift where Mauritius applies one — 8 of 11 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

VAT return and payment — monthly periods, 20-day date

VAT · Monthly · return filing

20th of the month after the month ends Verified 2026-09-23
Who files
Monthly filers (annual turnover of taxable supplies above MUR 10 million, or a smaller business that has elected monthly periods) who do not both file and pay electronically under the e-filing scheme
Notes
Due on the 20th of the month after the period, with the tax paid at the same time. Above MUR 10 million you must e-file unless MRA has authorised otherwise, so most monthly filers use the end-of-month date instead; this one is for a monthly filer who files or pays some other way. The return must be accompanied by a list of your taxable supplies other than retail sales, showing each invoice number and value. If you made and received no supplies at all, you still file a nil return.
Source
Value Added Tax Regulations 1998, regulation 9(1) (consolidated to April 2026) Mauritius Revenue Authority
See the source text
“For the purposes of section 22(1) of the Act, the prescribed time shall be 20 days.”
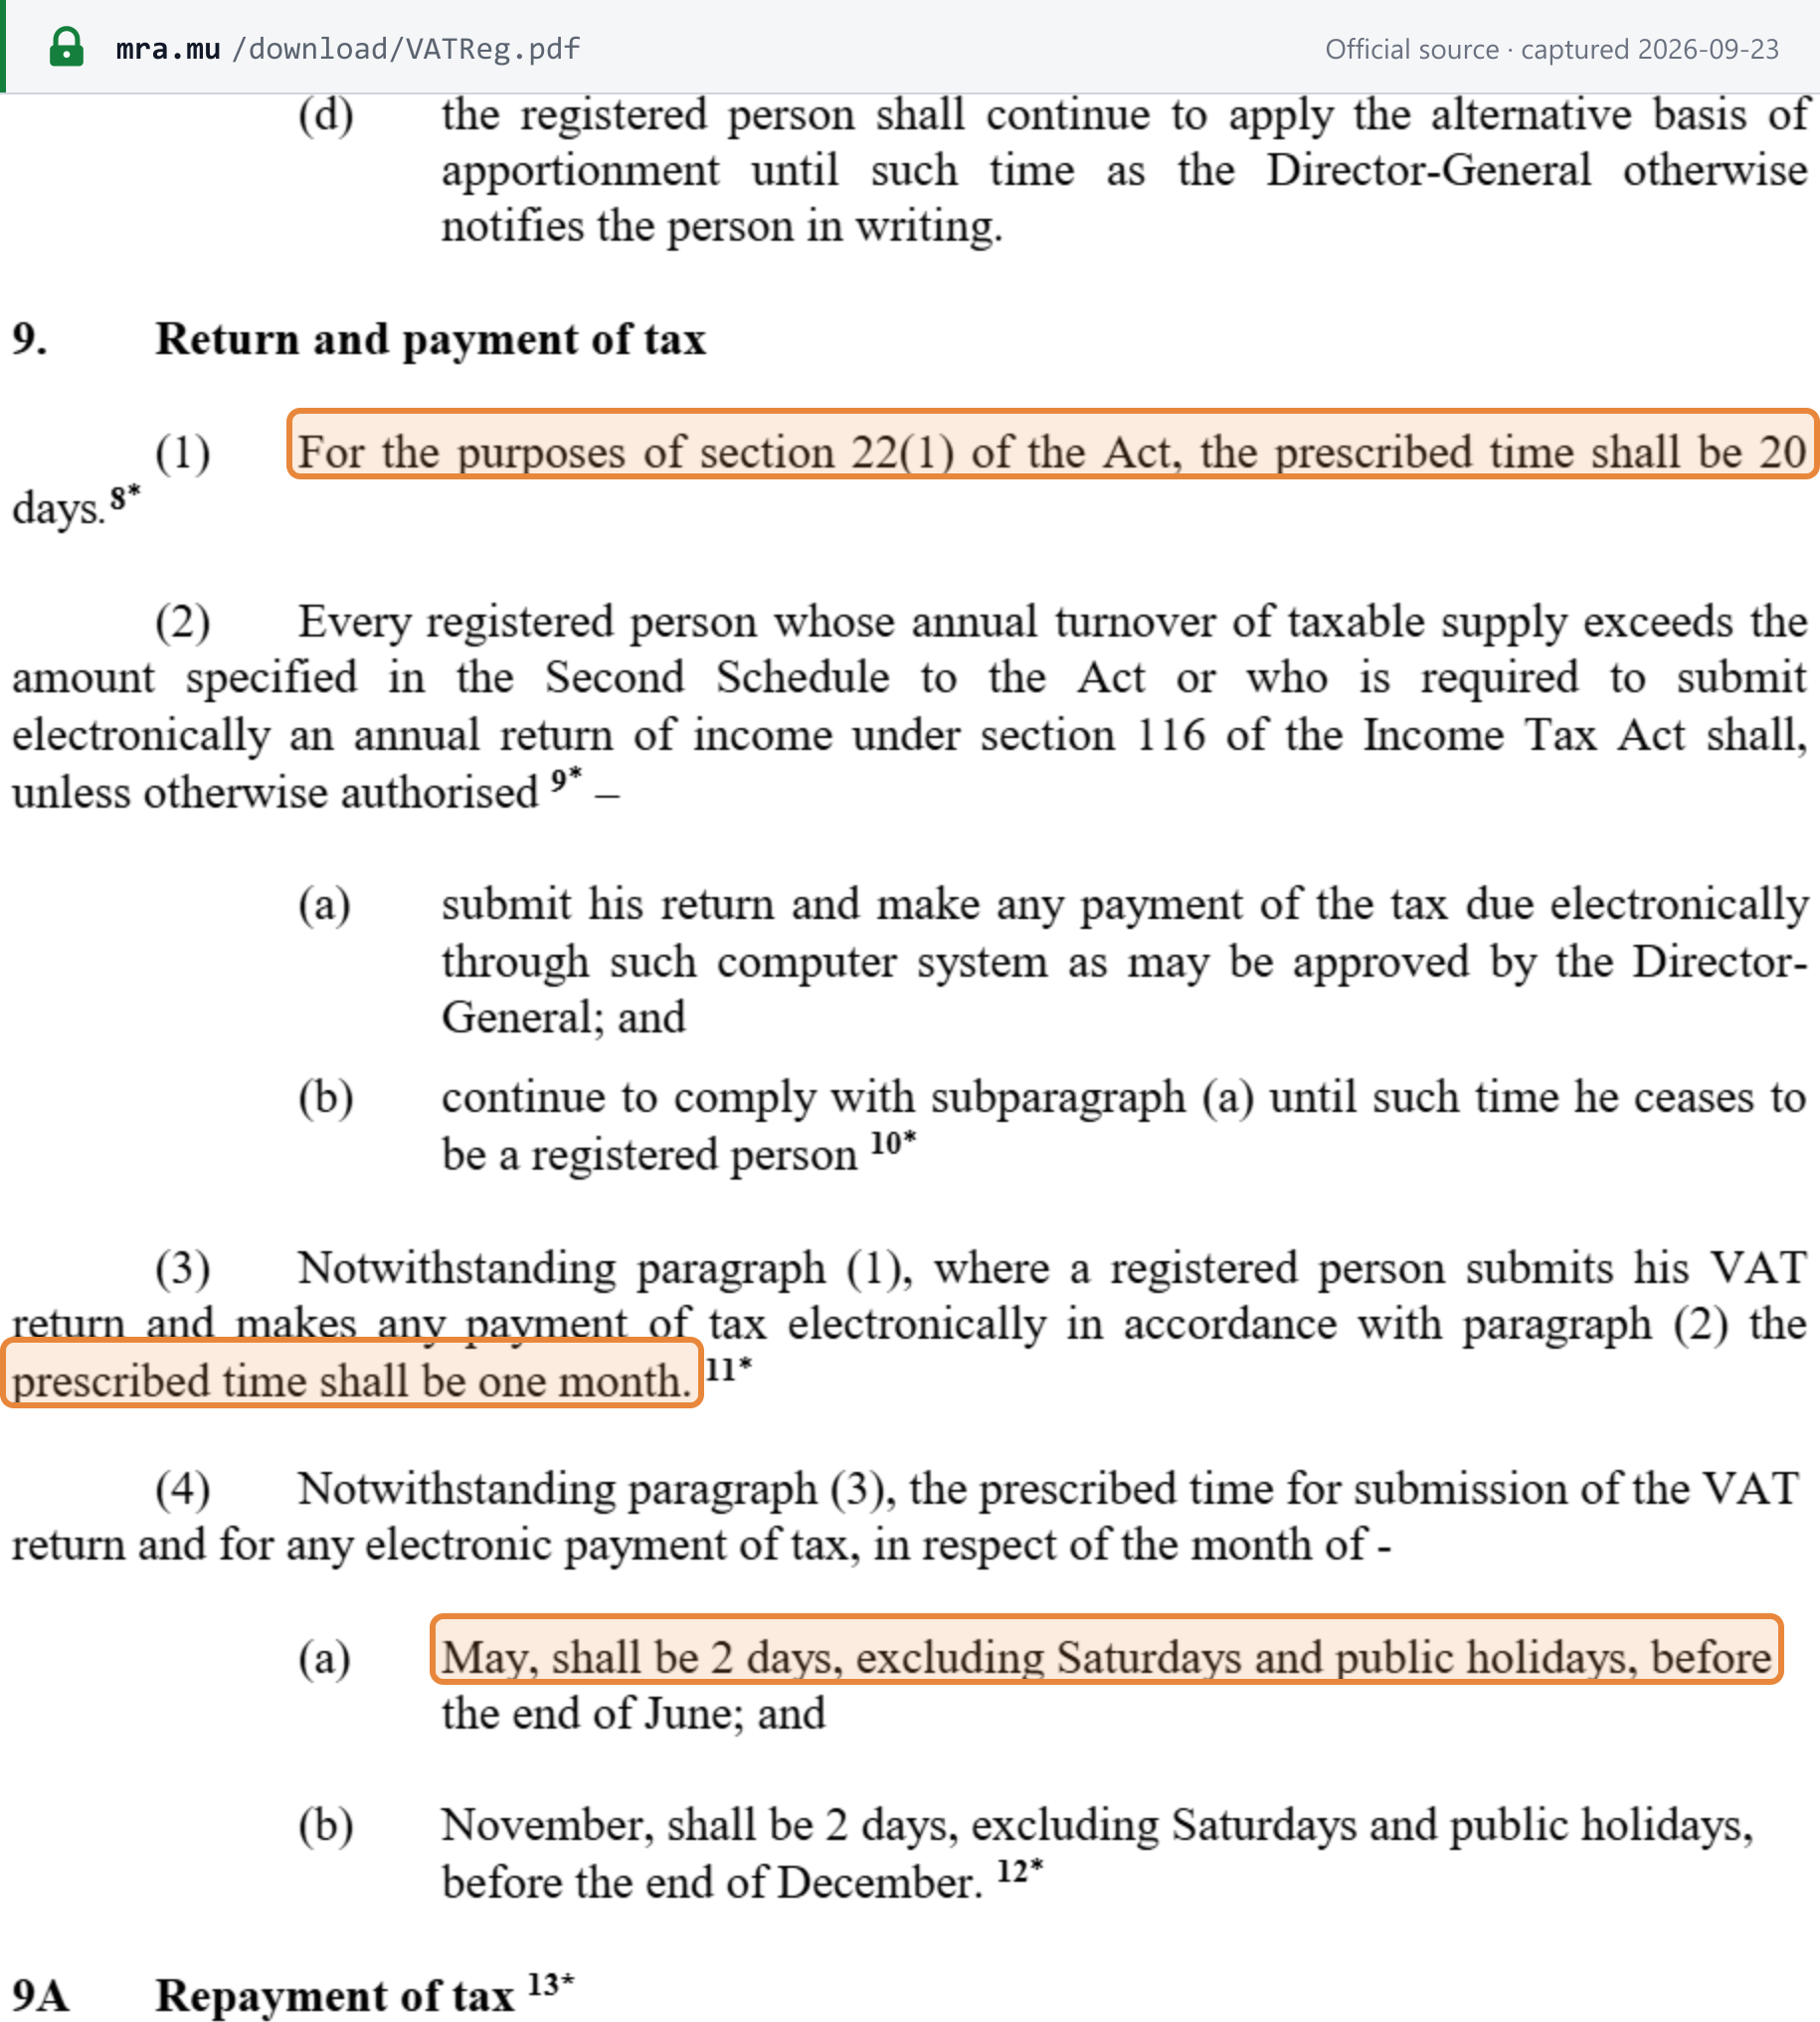
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — monthly periods, 20-day date deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23
VAT return and payment — quarterly periods, 20-day date

VAT · Quarterly · return filing

20th of the month after the quarter ends Verified 2026-09-23
Who files
Registered persons with annual turnover of taxable supplies of MUR 10 million or less who have not elected monthly periods and do not both file and pay electronically under the e-filing scheme
Notes
Quarters end in March, June, September and December, so the quarter to 30 September 2026 is due 20 October. Pay what the return shows when you file it. Quarterly filers do not send a supplies list. If your turnover for the year goes above MUR 10 million, you must tell MRA within 15 days of closing your accounts and switch to monthly returns.
Source
Value Added Tax Regulations 1998, regulation 9(1) (consolidated to April 2026) Mauritius Revenue Authority
See the source text
“For the purposes of section 22(1) of the Act, the prescribed time shall be 20 days.”
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — quarterly periods, 20-day date deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23
VAT return and payment — monthly periods, e-filers (end of following month)

VAT · Monthly · return filing

last day of the month after the month ends Verified 2026-09-23
Who files
Monthly filers who both file the return and pay electronically under the e-filing scheme, which is compulsory above MUR 10 million annual turnover and for anyone required to file their annual income tax return electronically. The May and November periods are due earlier, two working days before the end of June and December
Notes
Due on the last day of the month after the period, provided you both file and pay online. File online but pay another way and you are back on the 20th. The supplies list goes in with the return. When the month end is a weekend or holiday the date moves on: the September 2026 return is due 3 November, because 31 October is a Saturday, 1 November a Sunday and 2 November a public holiday.
Source
Value Added Tax Regulations 1998, regulation 9(2)–(3) (consolidated to April 2026) Mauritius Revenue Authority
See the source text
“Notwithstanding paragraph (1), where a registered person submits his VAT return and makes any payment of tax electronically in accordance with paragraph (2) the prescribed time shall be one month.”
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — monthly periods, e-filers (end of following month) deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23
VAT return and payment — May and November periods, e-filers

VAT · Monthly · return filing

3 published dates, 29 Dec 2025 to 29 Dec 2026 Verified 2026-09-23
Who files
Monthly filers who both file and pay electronically under the e-filing scheme, for the May and November periods only
Notes
For these two months only, the e-filing deadline comes early: two working days before the end of June for the May return, and two working days before the end of December for the November return, counting back and skipping weekends and public holidays. That makes the November 2026 return due Tuesday 29 December, not 31 December. The dates shown are copied from MRA's published tax calendar rather than worked out, and they stop where that calendar stops; MRA usually publishes the next half-year around January and July.
Source
MRA Tax Calendar, July–December 2026 (PDF edition) Mauritius Revenue Authority
See the source text
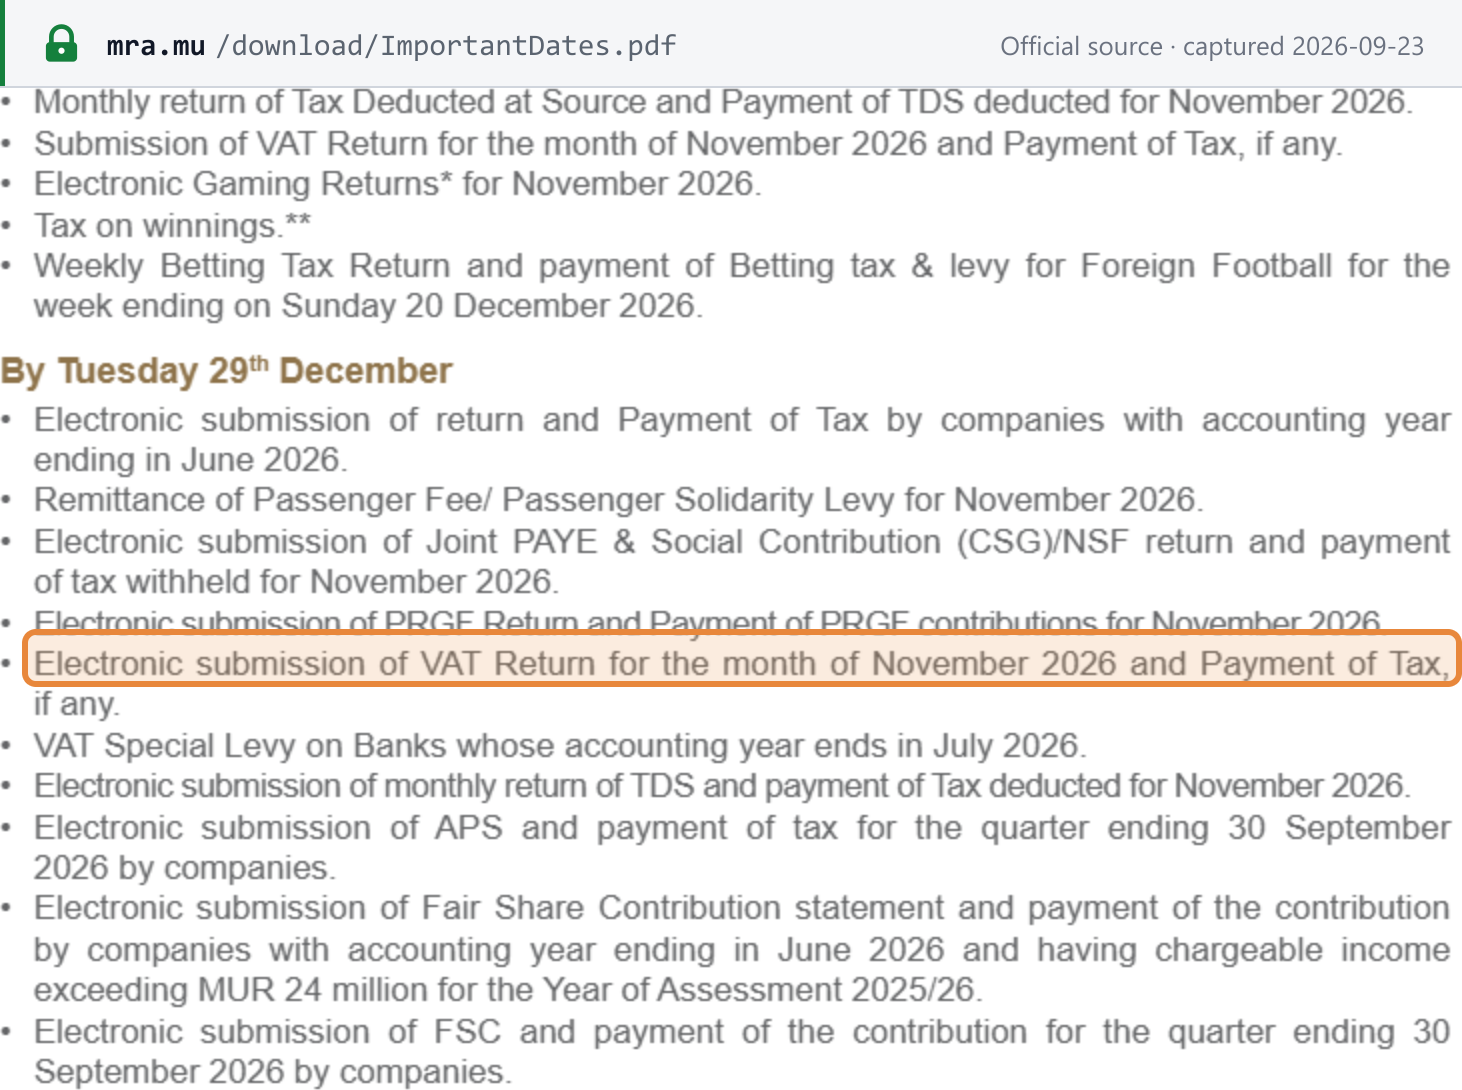
“Electronic submission of VAT Return for the month of November 2026 and Payment of Tax, if any.”
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — May and November periods, e-filers deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23
VAT return and payment — quarterly periods, e-filers (end of following month)

VAT · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-09-23
Who files
Quarterly filers (annual turnover of MUR 10 million or less) who both file and pay electronically under the e-filing scheme, which is compulsory for anyone required to file their annual income tax return electronically
Notes
Due at the end of the month after the quarter: 31 January, 30 April, 31 July and 31 October, moved on to the next working day when that date is not one. The early June and December deadline for May and November does not reach quarterly filers, because their quarters end in June and December.
Source
Value Added Tax Regulations 1998, regulation 9(2)–(3) (consolidated to April 2026) Mauritius Revenue Authority
See the source text
“Notwithstanding paragraph (1), where a registered person submits his VAT return and makes any payment of tax electronically in accordance with paragraph (2) the prescribed time shall be one month.”
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — quarterly periods, e-filers (end of following month) deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23
VAT return and payment — foreign suppliers of digital or electronic services, monthly

VAT · Monthly · return filing

20th of the month after the month ends Verified 2026-09-23
Who files
Foreign suppliers of digital or electronic services registered under section 15(2)(a)(iii) of the VAT Act whose annual turnover of taxable supplies exceeds MUR 10 million
Notes
The Act gives foreign digital-service suppliers 20 days after each period to file and pay, and a list of taxable supplies made to customers in Mauritius goes in with each return. MRA's guide for foreign suppliers also mentions the end of the following month in places; the 20th is the date the Act states and the earlier of the two, so it is the safe one to work to.
Source
Value Added Tax Act, section 22(4) (consolidated to May 2026) Mauritius Revenue Authority
See the source text
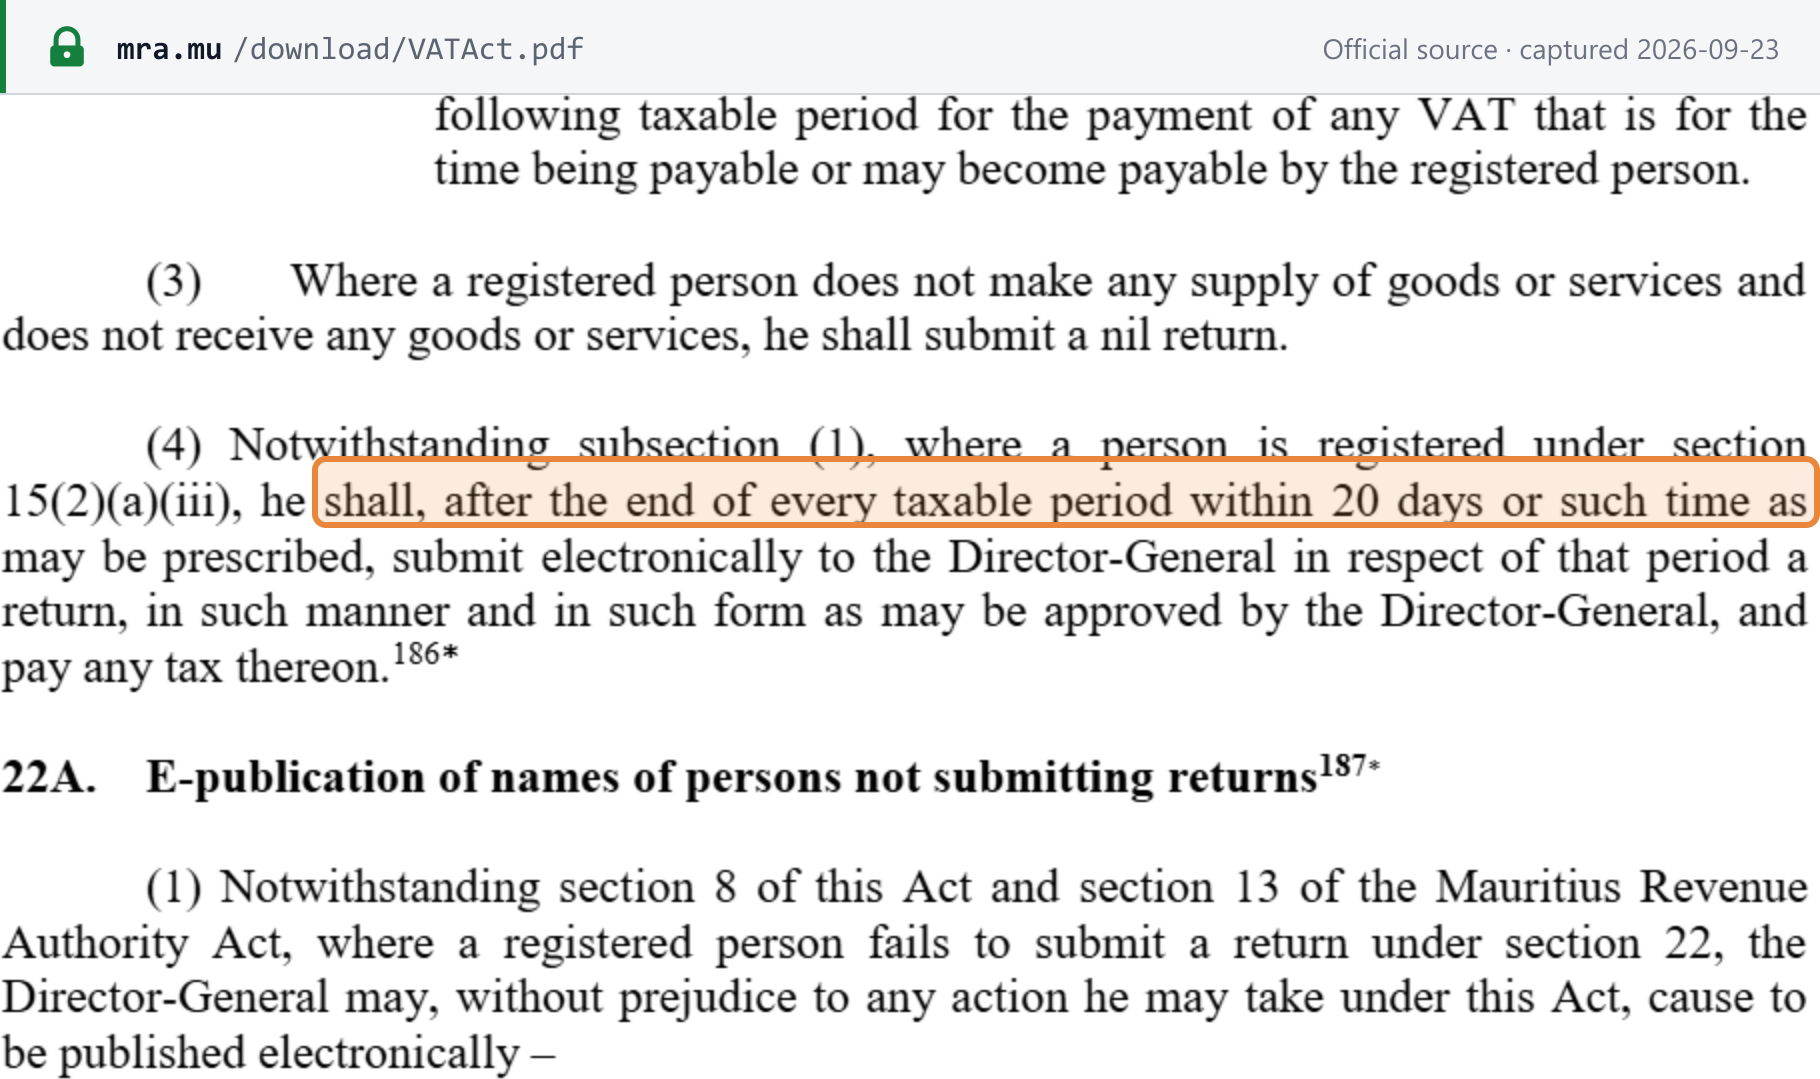
“Notwithstanding subsection (1), where a person is registered under section 15(2)(a)(iii), he shall, after the end of every taxable period within 20 days or such time as may be prescribed, submit electronically to the Director-General in respect of that period a return, in such manner and in such form as may be approved by the Director-General, and pay any tax thereon.”
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — foreign suppliers of digital or electronic services, monthly deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23
VAT return and payment — foreign suppliers of digital or electronic services, quarterly

VAT · Quarterly · return filing

20th of the month after the quarter ends Verified 2026-09-23
Who files
Foreign suppliers of digital or electronic services registered under section 15(2)(a)(iii) of the VAT Act whose annual turnover of taxable supplies is MUR 10 million or less
Notes
Quarterly is the default for a smaller foreign supplier, not an option to apply for. File and pay by the 20th of January, April, July and October, with your list of supplies to Mauritian customers attached.
Source
Value Added Tax Act, section 22(4) (consolidated to May 2026) Mauritius Revenue Authority
See the source text
“Notwithstanding subsection (1), where a person is registered under section 15(2)(a)(iii), he shall, after the end of every taxable period within 20 days or such time as may be prescribed, submit electronically to the Director-General in respect of that period a return, in such manner and in such form as may be approved by the Director-General, and pay any tax thereon.”
Screenshot of Mauritius Revenue Authority showing the VAT return and payment — foreign suppliers of digital or electronic services, quarterly deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23

Insurance Premium Tax return and payment

Insurance premium tax · Monthly · return filing

last day of the month after the month ends Verified 2026-09-23
Who files
General insurers, on premiums under general insurance policies entered into or renewed on or after 1 January 2027 (reinsurance and non-Mauritian policies excluded)
Notes
A new tax introduced by the Finance Act 2026: from 1 January 2027 general insurers charge 5% Insurance Premium Tax on premiums and file and pay it monthly by the end of the following month. The first return, for January 2027, is due 1 March 2027 because 28 February is a Sunday. The May and November returns are due earlier, two working days before the end of June and December; those dates are not shown here until MRA publishes them.
Source
Finance Act 2026 (Act No. 14 of 2026), section 25(p), inserting Value Added Tax Act section 53U Mauritius Revenue Authority
See the source text
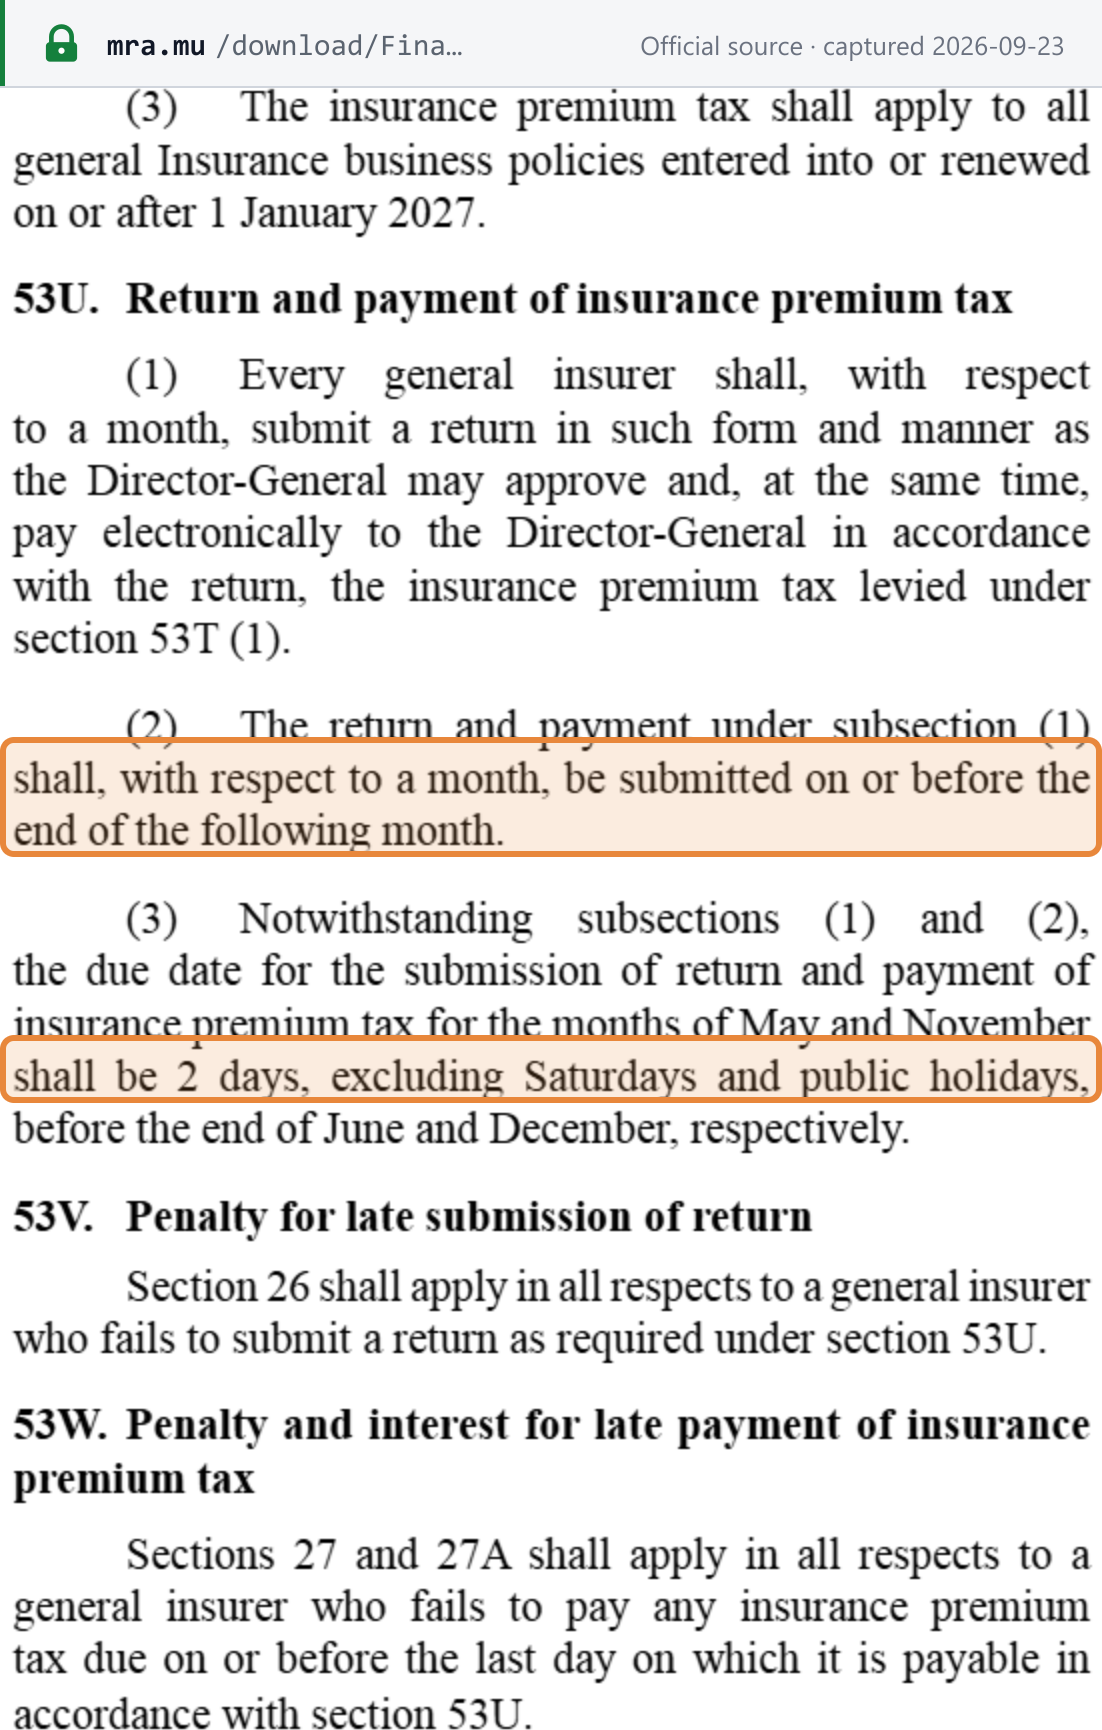
“The return and payment under subsection (1) shall, with respect to a month, be submitted on or before the end of the following month.”
Screenshot of Mauritius Revenue Authority showing the Insurance Premium Tax return and payment deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23

Tourist Fee return and payment

Tourist fee · Monthly · return filing

last day of the month after the month ends Verified 2026-09-23
Who files
Managers of tourist accommodation (hotels, guesthouses, tourist residences and "Domaine" properties) registered or required to be registered under the Tourism Authority Act
Notes
Since 1 October 2025 tourist accommodation charges a Tourist Fee of 3 euros per tourist aged 12 or over for each night, collected by MRA under the Tourism Authority Act. The manager files a monthly return online, night by night, and pays by the end of the following month. Residents, Mauritian passport holders, and holders of a Premium Visa or residence permit are not charged. MRA's tax calendar does not yet list a date for the November 2026 return, so none is shown here; check MRA's calendar before the end of December.
Source
Registration of Tourist Accommodation and Payment of Tourist Fee Mauritius Revenue Authority
See the source text
“Upon registration, managers are required to submit a monthly return electronically to the Director-General and pay tourist fee on or before the end of the following month, giving the following details for each night of the month:”
Captured from Mauritius Revenue Authority on 2026-09-23

Statement and payment for periods before a late registration

VAT · One-off · return filing

within 30 days of the date of registration, where you should have been registered earlier Verified 2026-09-23
Who files
Anyone registered for VAT later than the date from which they were required to be registered, whether the duty arose from turnover above (or likely to exceed) MUR 3 million or from one of the categories the Act requires to register regardless of turnover, such as the professions and businesses in its Tenth Schedule and foreign suppliers of digital or electronic services
Notes
The Act sets no fixed number of days to apply for registration; you are expected to apply as soon as you become required to, and a penalty runs from the period you became liable. If you register late, you then have 30 days from registration to file a statement covering the periods you should have been registered for, up to four years back, and to pay the tax due for them.
Source
Value Added Tax Act, section 23(1) (consolidated to May 2026) Mauritius Revenue Authority
See the source text
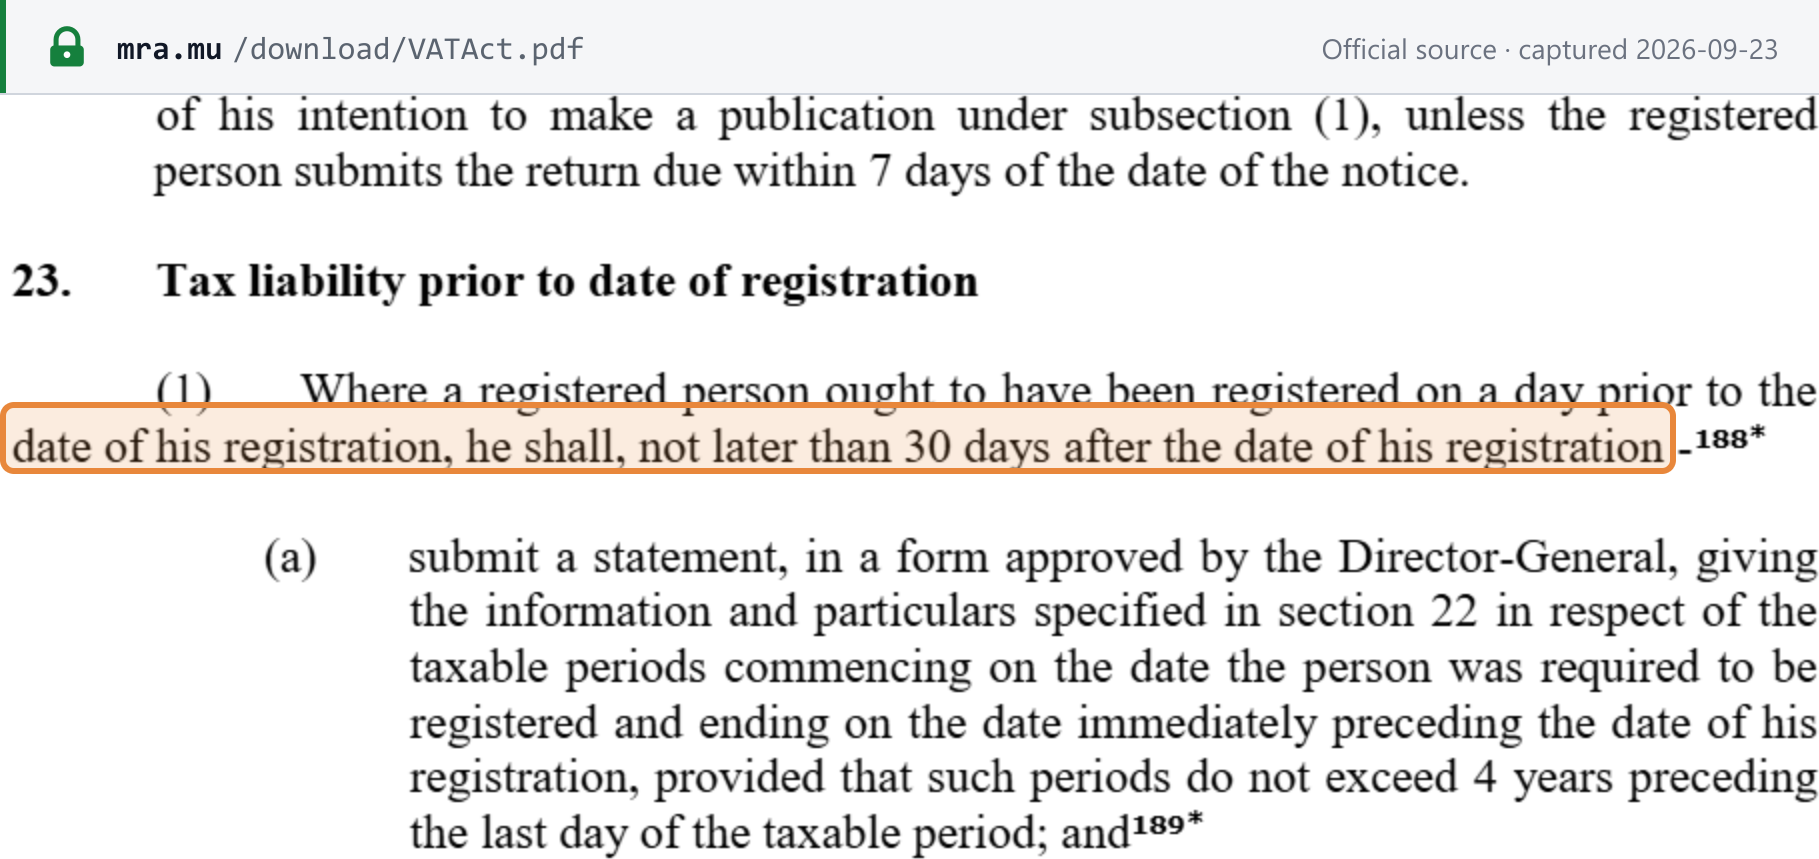
“Where a registered person ought to have been registered on a day prior to the date of his registration, he shall, not later than 30 days after the date of his registration”
Screenshot of Mauritius Revenue Authority showing the Statement and payment for periods before a late registration deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23

Notice of moving from quarterly to monthly returns

VAT · One-off · other

within 15 days of the closing of your annual accounts Verified 2026-09-23
Who files
Quarterly filers whose annual turnover of taxable supplies exceeds MUR 10 million
Notes
Tell MRA in writing within 15 days of closing your annual accounts, then file monthly from the month after the quarter. Crossing MUR 10 million also brings in compulsory e-filing and the monthly supplies list. A monthly filer whose turnover falls back to MUR 10 million or less may move to quarterly on the same 15-day notice, but does not have to.
Source
Value Added Tax Act, section 25(1) (consolidated to May 2026) Mauritius Revenue Authority
See the source text
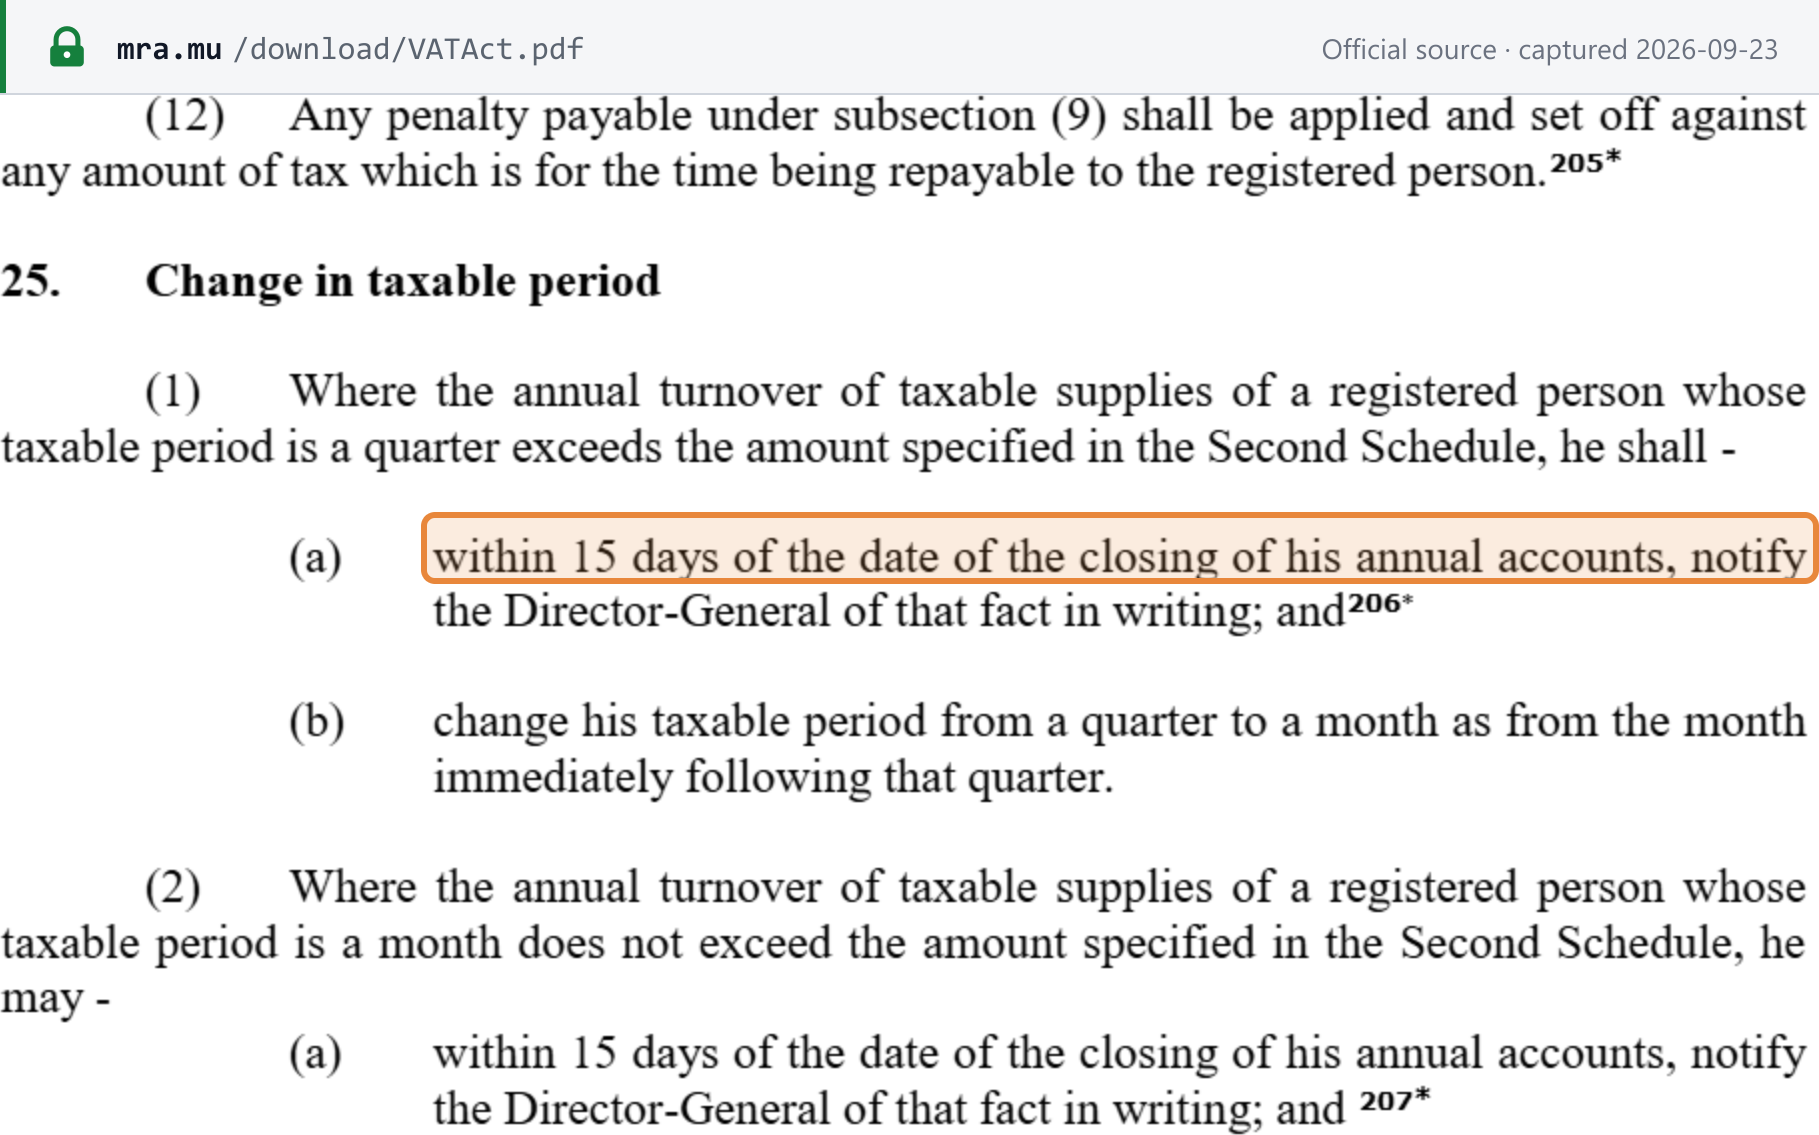
“Where the annual turnover of taxable supplies of a registered person whose taxable period is a quarter exceeds the amount specified in the Second Schedule, he shall - (a) within 15 days of the date of the closing of his annual accounts, notify the Director-General of that fact in writing;”
Screenshot of Mauritius Revenue Authority showing the Notice of moving from quarterly to monthly returns deadline Open full size Captured from Mauritius Revenue Authority on 2026-09-23

VAT returns are monthly above MUR 10 million annual turnover of taxable supplies and quarterly otherwise. Tax is paid with the return, and monthly filers attach a list of their taxable supplies. The return is due 20 days after the period ends, or at the end of the following month if you both file and pay online under the e-filing scheme; e-filers' May and November returns are due two working days before the end of June and December. If unsure which date applies, use the 20th. A deadline on a weekend or public holiday moves to the next working day. Not covered here: passenger fees, the environment protection fee, betting and gaming taxes, excise, the fair share contribution and the special levy on banks.

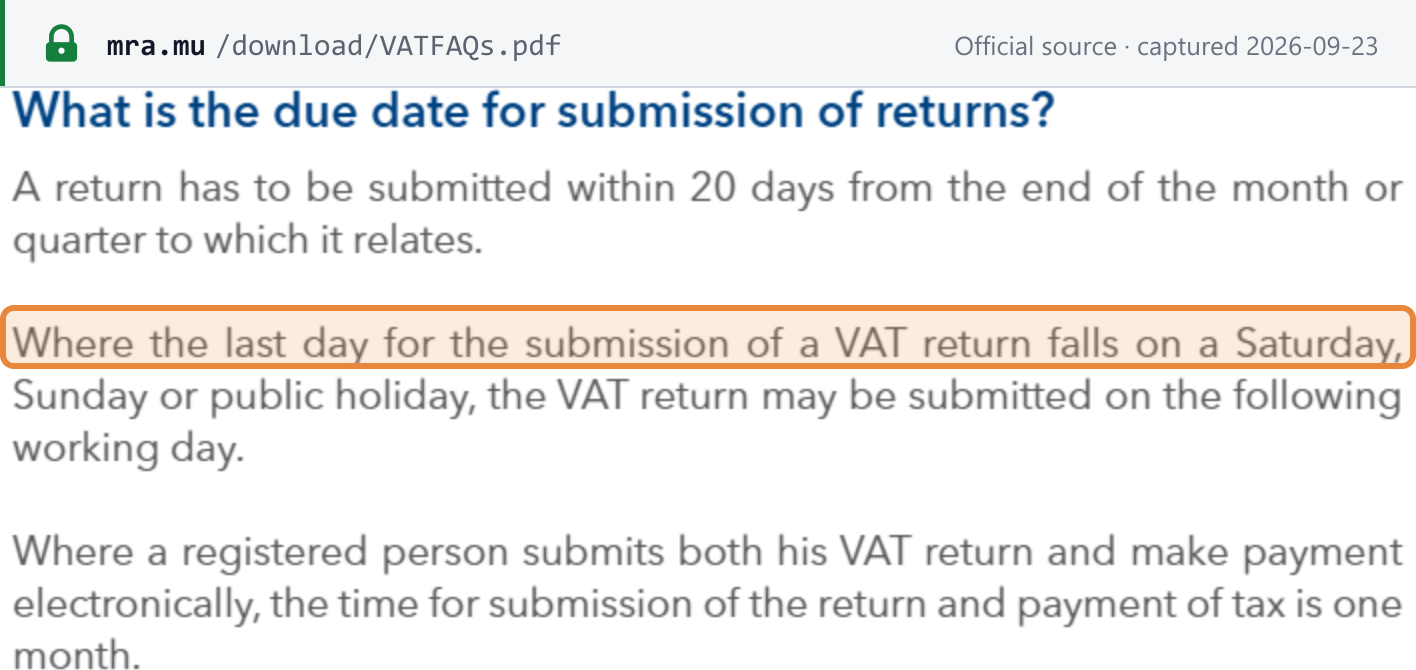
“Where the last day for the submission of a VAT return falls on a Saturday, Sunday or public holiday, the VAT return may be submitted on the following working day.”
Screenshot of the official source stating the rule that governs Mauritius's deadlines
VAT Frequently Asked Questions — What is the due date for submission of returns? — Mauritius Revenue Authority, captured 2026-09-23

What this calendar does not list

  • Not applicable E-invoicing / e-reporting cycle — MRA's e-invoicing system requires each invoice or receipt to be fiscalised with MRA in real time before it is issued (VAT (E-invoicing) Regulations 2023; MRA e-invoicing page, checked 2026-09-23). There is no periodic submission or reporting deadline; the rollout phases only set the date from which each group of businesses must start issuing fiscal invoices.
  • Not yet covered Annual or reconciliation return — The VAT Act (s. 27E) creates an annual VAT accounting system for small enterprises with turnover up to MUR 10 million. Under it a simplified VAT statement is due after each of the first three calendar quarters of the accounting year (s. 27E(3)(b)) and an annual return after the year ends (s. 27E(8)), both 'within such time as may be prescribed'. No regulation prescribing either time was found in the VAT Regulations 1998 (consolidated to April 2026), and MRA's tax calendars for July 2025 to December 2026 carry no entry for them, as of 2026-09-23. The return exists in law, so this is a gap rather than not-applicable. Ordinary filers have no annual or reconciliation VAT return.

About this calendar

Which Mauritius tax deadlines does this calendar cover?

11 recurring indirect-tax obligations — VAT, Insurance premium tax and Tourist fee returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-09-23). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.