Slovakia compliance calendar

18 recurring Daň z pridanej hodnoty (VAT), Spotrebné dane (excise duties), Daň z poistenia (insurance premium tax) and 2 more obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Slovakia rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
31
1
2
3
4
5
6
7
8
9
10
11
Return filing Report / listing Payment Law change takes effect

Dates already include the weekend and public-holiday shift where Slovakia applies one — 11 of 18 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Daňové priznanie k DPH — monthly

Daň z pridanej hodnoty (VAT) · Monthly · return filing

25th of the month after the month ends Verified 2026-09-07
Who files
Every VAT payer on the default monthly tax period — anyone who has not elected, or does not qualify for, the calendar quarter
Notes
The month is the default tax period and both the return and the money are due within 25 days of it ending. Where that 25th falls on a Saturday, a Sunday or a public day of rest the deadline moves to the next working day, which is why the December period lands on 28 December in 2026 rather than on Christmas Day. Import VAT charged by the customs authority is the exception to the shared date: it is payable on the customs timetable, not with this return.
Source
Zákon č. 222/2004 Z. z. o DPH — § 78 ods. 2 písm. a) (daňové priznanie a zaplatenie dane) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“má sídlo, miesto podnikania alebo prevádzkareň v tuzemsku, a ak nemá takéto miesto, ale má bydlisko v tuzemsku alebo sa v tuzemsku obvykle zdržiava, je povinný podať daňové priznanie do 25 dní po skončení každého zdaňovacieho obdobia a v tej istej lehote je povinný zaplatiť vlastnú daňovú povinnosť”
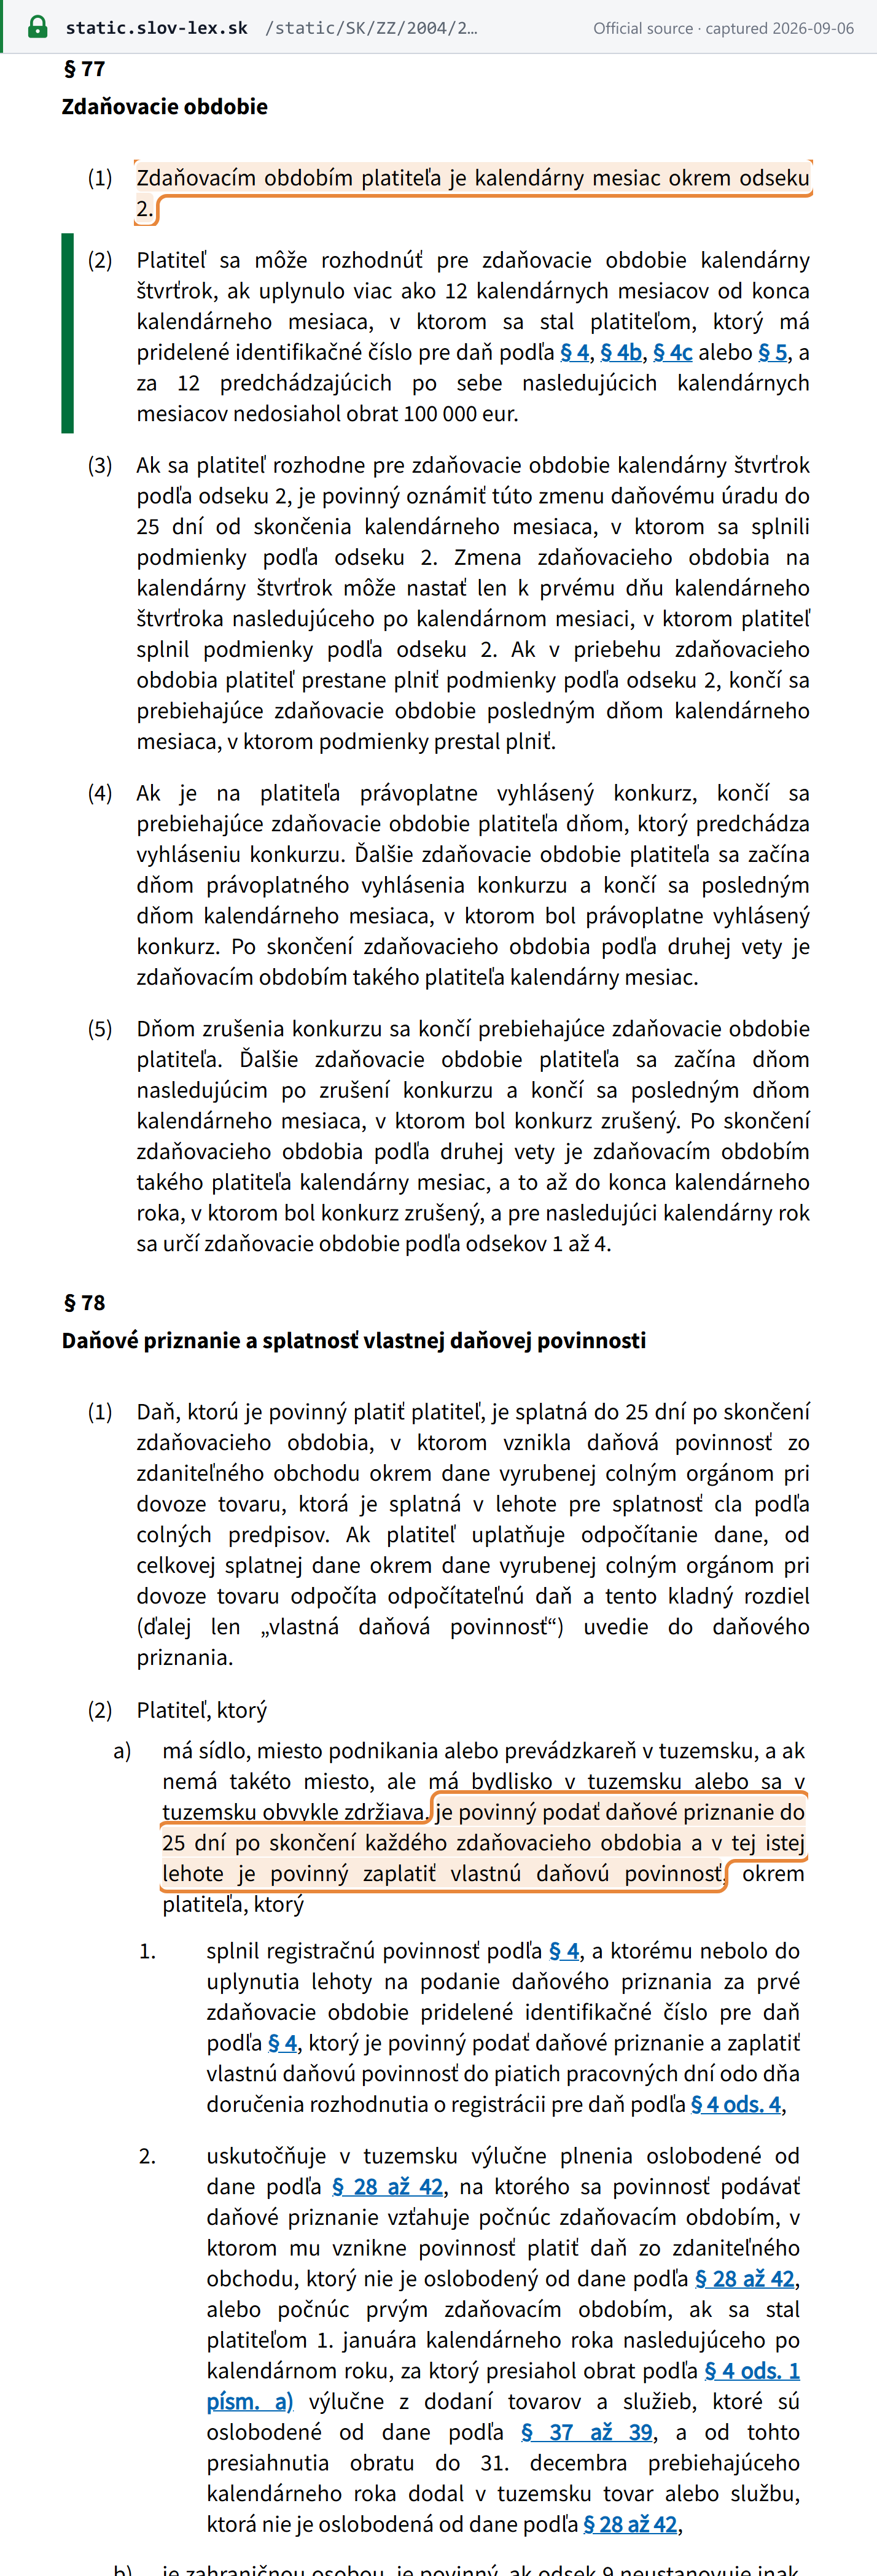
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Daňové priznanie k DPH — monthly deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07
Daňové priznanie k DPH — quarterly

Daň z pridanej hodnoty (VAT) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-09-07
Who files
VAT payers who have elected the calendar quarter — available once more than 12 calendar months have passed since becoming a payer with an allocated VAT ID, and turnover over the preceding 12 consecutive months stayed below EUR 100,000
Notes
Quarterly filing is a choice, not a default, and it opens only after you have been a registered payer for more than twelve calendar months with turnover under EUR 100,000 over the preceding twelve. Two things to watch. You must notify the tax office of the change within 25 days of the month in which you met the conditions, and the switch can only take effect from the first day of the next quarter. And it works in reverse: fall out of the conditions and the running tax period ends on the last day of that month.
Source
Zákon č. 222/2004 Z. z. o DPH — § 77 ods. 2 (kalendárny štvrťrok ako zdaňovacie obdobie) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
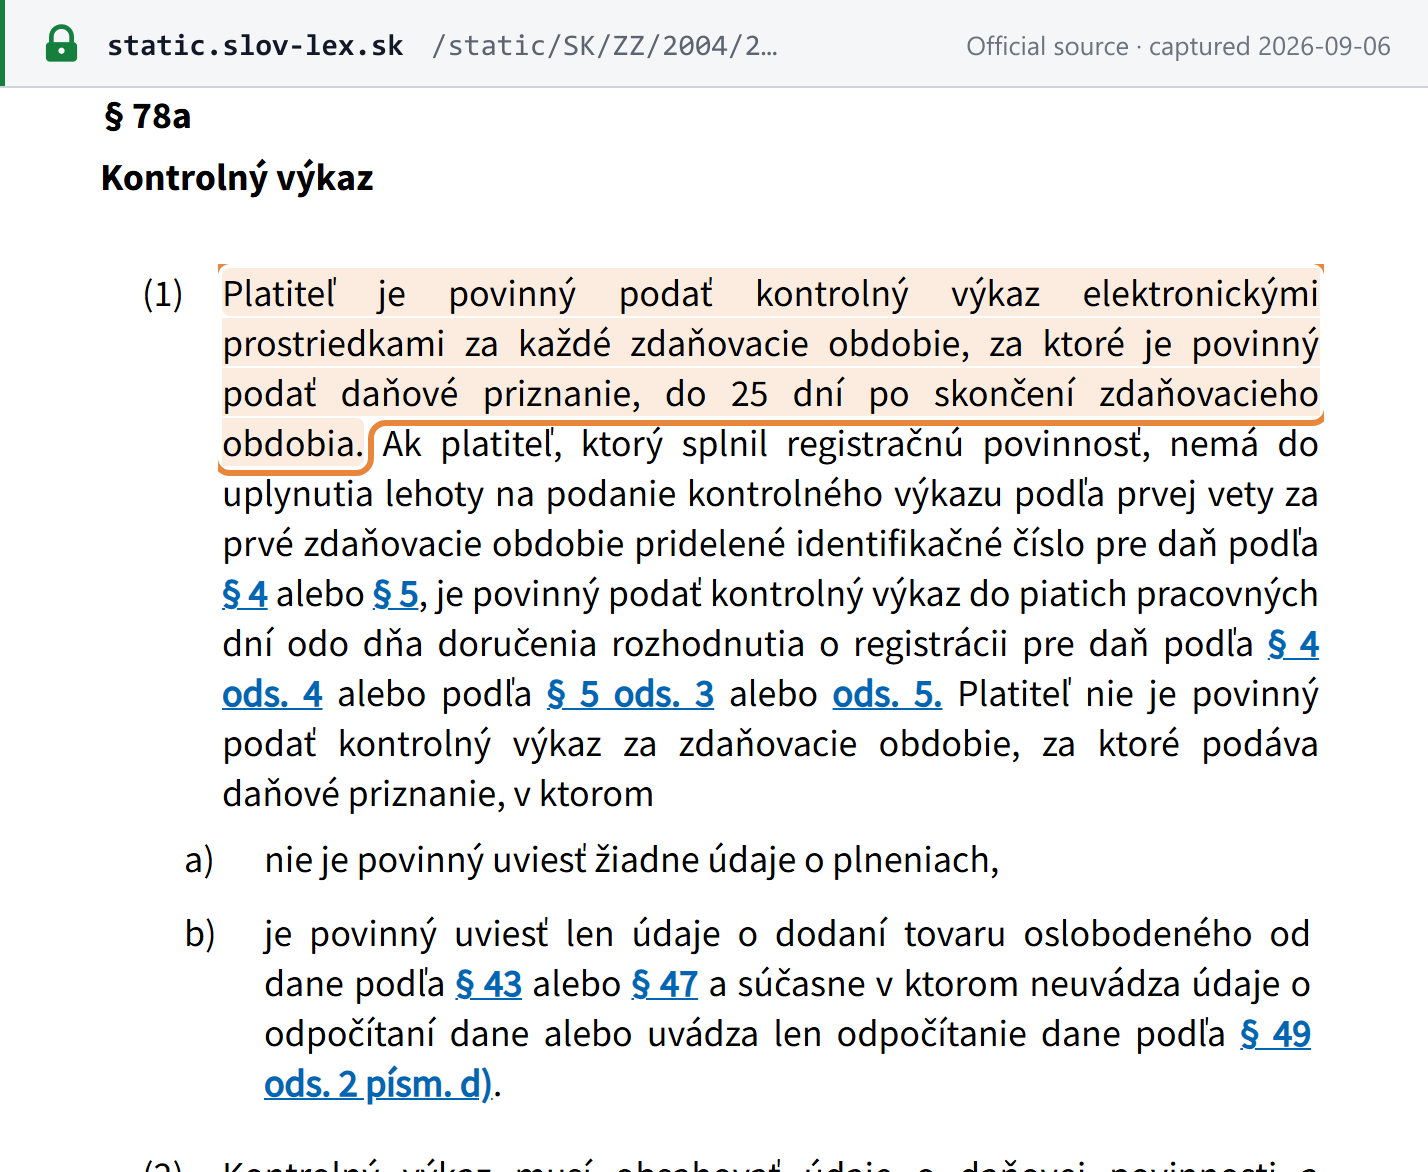
“Platiteľ sa môže rozhodnúť pre zdaňovacie obdobie kalendárny štvrťrok, ak uplynulo viac ako 12 kalendárnych mesiacov od konca kalendárneho mesiaca, v ktorom sa stal platiteľom, ktorý má pridelené identifikačné číslo pre daň podľa § 4, § 4b, § 4c alebo § 5, a za 12 predchádzajúcich po sebe nasledujúcich kalendárnych mesiacov nedosiahol obrat 100 000 eur.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Daňové priznanie k DPH — quarterly deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07
Kontrolný výkaz (VAT control statement) — monthly

Daň z pridanej hodnoty (VAT) — kontrolný výkaz · Monthly · report / listing

25th of the month after the month ends Verified 2026-09-07
Who files
VAT payers whose tax period is the calendar month
Notes
Slovakia's transaction-level listing, filed electronically in XML within the same 25 days as the return — anything in another format is disregarded. Two traps cost real money here. A nil return does not always mean no control statement: the authority gives a list of examples — among them the annual pro-rata settlement, capital-goods adjustments and the deregistration charge — where a statement with no transaction data is still due, and it does not present that list as closed. And the 25-day deadline stands even if you never filed the return itself or filed it late.
Source
Zákon č. 222/2004 Z. z. o DPH — § 78a ods. 1 (kontrolný výkaz) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
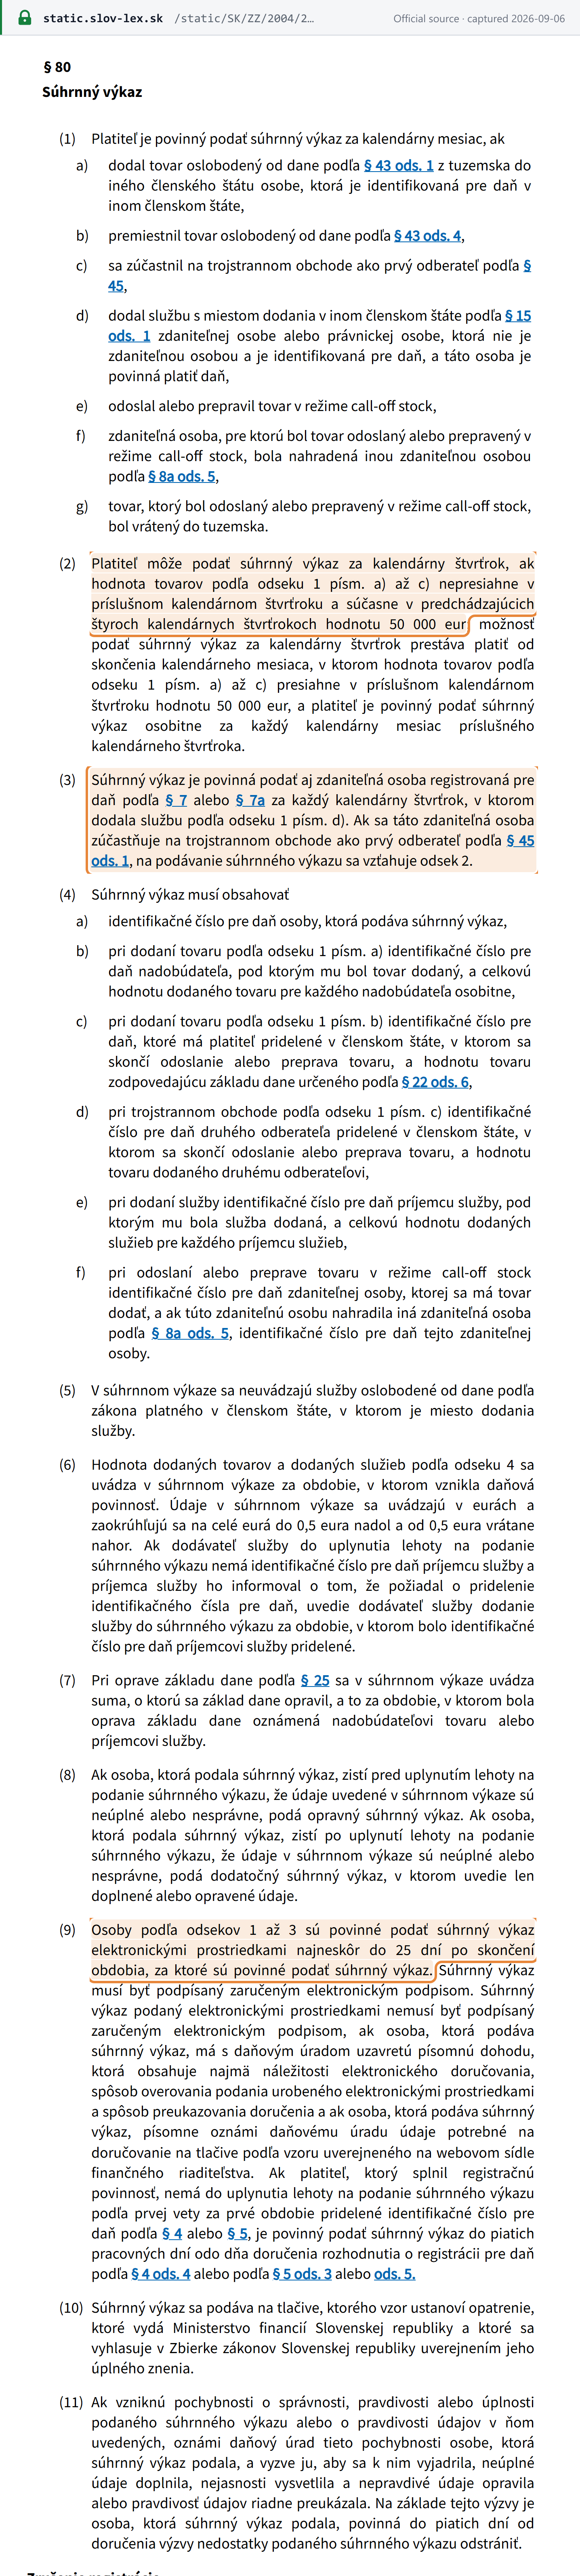
“Platiteľ je povinný podať kontrolný výkaz elektronickými prostriedkami za každé zdaňovacie obdobie, za ktoré je povinný podať daňové priznanie, do 25 dní po skončení zdaňovacieho obdobia.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Kontrolný výkaz (VAT control statement) — monthly deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07
Kontrolný výkaz (VAT control statement) — quarterly

Daň z pridanej hodnoty (VAT) — kontrolný výkaz · Quarterly · report / listing

25th of the month after the quarter ends Verified 2026-09-07
Who files
VAT payers whose tax period is the calendar quarter
Notes
Quarterly payers file the control statement on the same quarterly rhythm as their return, giving four dates a year instead of twelve. You do not choose this cadence separately — the statement follows whichever tax period the return is on. The exemption for a period with nothing to report is narrower than it sounds, so check the authority's list before deciding a quarter needs nothing.
Source
Zákon č. 222/2004 Z. z. o DPH — § 78a ods. 1 čítané s § 77 ods. 2 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Platiteľ je povinný podať kontrolný výkaz elektronickými prostriedkami za každé zdaňovacie obdobie, za ktoré je povinný podať daňové priznanie, do 25 dní po skončení zdaňovacieho obdobia.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Kontrolný výkaz (VAT control statement) — quarterly deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07
Súhrnný výkaz (EC Sales List) — monthly

Daň z pridanej hodnoty (VAT) — súhrnný výkaz · Monthly · report / listing

25th of the month after the month ends Verified 2026-09-07
Who files
VAT payers making exempt intra-EU supplies of goods, transfers of own goods, triangulation as first customer, call-off stock movements, or services on which a customer in another member state is liable — and tax representatives, who file one combined monthly statement for all the foreign persons they represent
Notes
The monthly EC Sales List is filed electronically within 25 days of the month ending. Unlike the control statement there is normally nothing to file for a month with no qualifying supplies — but two exceptions bite: a call-off stock substitution or return still has to be reported, and so does a period whose only entry is a correction to a tax base.
Source
Zákon č. 222/2004 Z. z. o DPH — § 80 ods. 9 (lehota) a § 80 ods. 1 (mesačné obdobie) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Osoby podľa odsekov 1 až 3 sú povinné podať súhrnný výkaz elektronickými prostriedkami najneskôr do 25 dní po skončení obdobia, za ktoré sú povinné podať súhrnný výkaz.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Súhrnný výkaz (EC Sales List) — monthly deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07
Súhrnný výkaz (EC Sales List) — quarterly, elective

Daň z pridanej hodnoty (VAT) — súhrnný výkaz · Quarterly · report / listing

25th of the month after the quarter ends Verified 2026-09-07
Who files
VAT payers whose intra-EU supplies of GOODS stayed at or below EUR 50,000 in the quarter and in each of the four preceding quarters — the value of services supplied is disregarded for this test
Notes
The quarterly option turns on goods alone: services are left out of the EUR 50,000 test entirely, so a business supplying EUR 120,000 of cross-border services and EUR 45,000 of goods can still file quarterly. Breaching the limit mid-quarter is harsh — you must then file a separate statement for every month of that quarter, so a May breach means April and May are both due on 25 June and June follows on 25 July.
Source
Zákon č. 222/2004 Z. z. o DPH — § 80 ods. 2 (štvrťročný súhrnný výkaz) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Platiteľ môže podať súhrnný výkaz za kalendárny štvrťrok, ak hodnota tovarov podľa odseku 1 písm. a) až c) nepresiahne v príslušnom kalendárnom štvrťroku a súčasne v predchádzajúcich štyroch kalendárnych štvrťrokoch hodnotu 50 000 eur; možnosť podať súhrnný výkaz za kalendárny štvrťrok prestáva platiť od skončenia kalendárneho mesiaca, v ktorom hodnota tovarov podľa odseku 1 písm. a) až c) presiahne v príslušnom kalendárnom štvrťroku hodnotu 50 000 eur, a platiteľ je povinný podať súhrnný výkaz osobitne za každý kalendárny mesiac príslušného kalendárneho štvrťroka.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Súhrnný výkaz (EC Sales List) — quarterly, elective deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07
Súhrnný výkaz — § 7 or § 7a registrant

Daň z pridanej hodnoty (VAT) — súhrnný výkaz · Quarterly · report / listing

25th of the month after the quarter ends Verified 2026-09-07
Who files
Taxable persons registered under § 7 or § 7a who are NOT VAT payers — typically sole traders below the registration threshold who buy or sell cross-border services
Notes
If you are registered under § 7 or § 7a you are not a VAT payer: you file no VAT return and no control statement, and this is very likely the only recurring VAT filing you owe. It is due for every calendar quarter in which you supplied a service to a customer liable for the tax in another member state, within 25 days of the quarter ending. The cadence is fixed rather than chosen — there is no monthly version and no threshold. Taking part in triangulation as first customer puts you on the goods test instead.
Source
Zákon č. 222/2004 Z. z. o DPH — § 80 ods. 3 (povinný štvrťročný súhrnný výkaz) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Súhrnný výkaz je povinná podať aj zdaniteľná osoba registrovaná pre daň podľa § 7 alebo § 7a za každý kalendárny štvrťrok, v ktorom dodala službu podľa odseku 1 písm. d).”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Súhrnný výkaz — § 7 or § 7a registrant deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

OSS return — Union scheme

Daň z pridanej hodnoty (VAT) — OSS · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-09-07
Who files
Businesses using the Union One-Stop-Shop with Slovakia as member state of identification, for intra-EU distance sales, certain domestic supplies and B2C services
Notes
Quarterly, with the return and the money both due by the end of the following month. Two differences from the domestic return matter. A nil return is compulsory — you file even for a quarter in which you supplied nothing under the scheme. And the deadline does NOT move for a weekend or a public holiday: the statute says the last day is that day, so a 31 October falling on a Saturday stays on the Saturday.
Source
Zákon č. 222/2004 Z. z. o DPH — § 68b ods. 12 a ods. 18 (podanie a zaplatenie) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
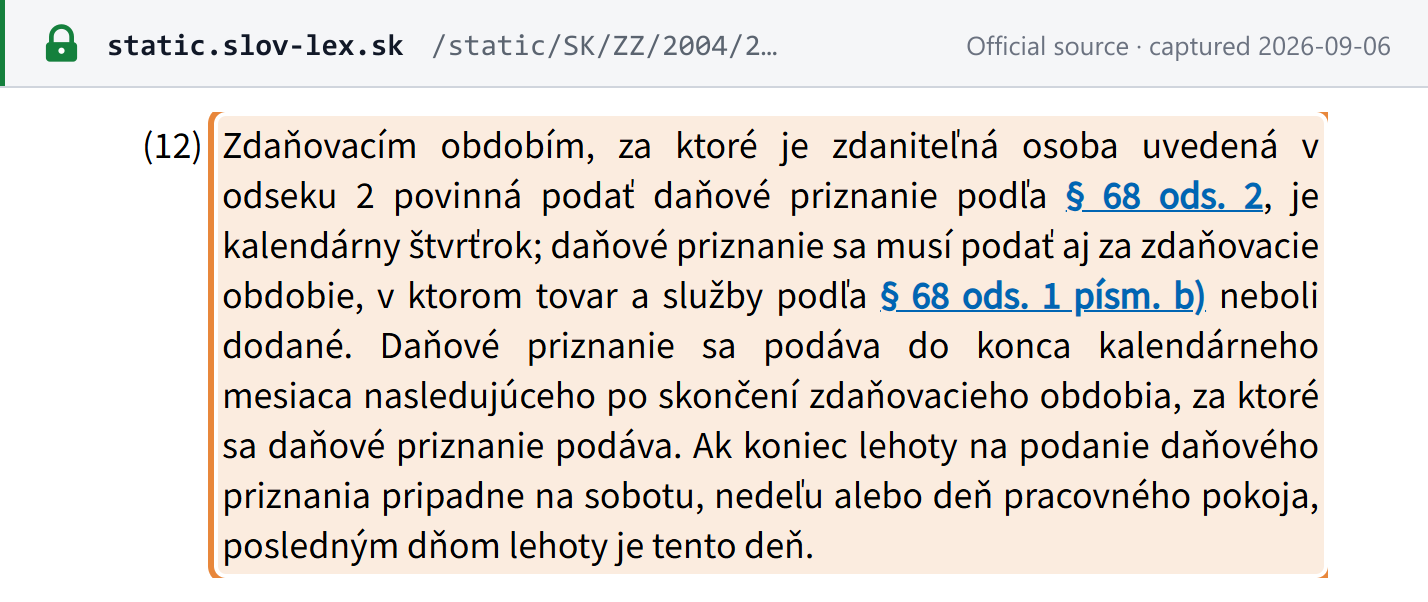
“Daňové priznanie sa podáva do konca kalendárneho mesiaca nasledujúceho po skončení zdaňovacieho obdobia, za ktoré sa daňové priznanie podáva. Ak koniec lehoty na podanie daňového priznania pripadne na sobotu, nedeľu alebo deň pracovného pokoja, posledným dňom lehoty je tento deň.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the OSS return — Union scheme deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

OSS return — non-Union scheme

Daň z pridanej hodnoty (VAT) — OSS · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-09-07
Who files
Taxable persons not established in the EU supplying services to EU consumers, with Slovakia as member state of identification
Notes
The non-EU scheme runs on the same quarterly cycle and the same end-of-following-month date as the Union one, and carries the same rule that the date does not move off a weekend or holiday. If you are established outside the EU and identified in Slovakia, this is your row rather than the Union one.
Source
Zákon č. 222/2004 Z. z. o DPH — § 68a ods. 9 a ods. 12 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Daň sa platí v eurách na príslušný účet daňového úradu najneskôr do konca lehoty na podanie daňového priznania s uvedením odkazu na príslušné daňové priznanie. Ak koniec lehoty na zaplatenie dane pripadne na sobotu, nedeľu alebo deň pracovného pokoja, posledným dňom lehoty je tento deň.”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

IOSS return — import scheme

Daň z pridanej hodnoty (VAT) — IOSS · Monthly · return filing

last day of the month after the month ends Verified 2026-09-07
Who files
Businesses or their intermediaries using the import One-Stop-Shop with Slovakia as member state of identification, for distance sales of imported goods
Notes
The import scheme runs monthly where both other One-Stop-Shop schemes run quarterly, which is the mistake to avoid if you are registered for more than one. The return and the payment are due by the end of the following month, a nil return is compulsory, and the date stands on a weekend — the authority publishes 28 February and 31 May 2026 as live deadlines even though both are non-working days.
Source
Zákon č. 222/2004 Z. z. o DPH — § 68c ods. 20 a ods. 23 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Daňové priznanie sa podáva do konca kalendárneho mesiaca nasledujúceho po skončení zdaňovacieho obdobia, za ktoré sa daňové priznanie podáva. Ak koniec lehoty na podanie daňového priznania pripadne na sobotu, nedeľu alebo deň pracovného pokoja, posledným dňom lehoty je tento deň.”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Výkaz for a Slovak small enterprise using the EU SME exemption

Daň z pridanej hodnoty (VAT) — malý podnik · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-09-07
Who files
Slovak-established small enterprises applying the cross-border SME exemption in other member states, under the EUR 100,000 EU-wide annual turnover threshold
Notes
Using the cross-border small-business exemption means a quarterly report on the form the Financial Directorate publishes, due by the end of the month after each quarter in which you applied the scheme. Report zero values as "0" rather than leaving them blank. Like the One-Stop-Shop returns and unlike the domestic ones, this deadline does not move off a weekend.
Source
Zákon č. 222/2004 Z. z. o DPH — § 68g ods. 8 (štvrťročný výkaz malého podniku) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Malý podnik tuzemskej osoby je povinný do konca kalendárneho mesiaca nasledujúceho po skončení kalendárneho štvrťroka, v ktorom uplatňoval osobitnú úpravu, podať výkaz na tlačive, ktorého vzor určí a uverejní finančné riaditeľstvo na webovom sídle finančného riaditeľstva; ak koniec lehoty na podanie výkazu pripadne na sobotu, nedeľu alebo deň pracovného pokoja, posledným dňom lehoty je tento deň.”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

SME exemption — report on breaching the EU-wide threshold

Daň z pridanej hodnoty (VAT) — malý podnik · One-off · report / listing

within 15 business days of the supply that takes EU-wide annual turnover past EUR 100,000 in the current calendar year (§ 68g ods. 14) Verified 2026-09-07
Who files
Slovak small enterprises whose EU-wide annual turnover passes EUR 100,000 during a calendar year
Notes
Cross EUR 100,000 of EU-wide turnover and the exemption stops applying from that very supply — not from the next quarter, and not from the next year. You then have 15 working days to file a report covering the stub period from the start of the quarter up to the supply that took you over. Working days, so the real window is about three weeks.
Source
Zákon č. 222/2004 Z. z. o DPH — § 68g ods. 14 (prekročenie obratu 100 000 eur) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Ak hodnota bez dane dodaných tovarov a služieb, ktoré sa zahŕňajú do ročného obratu v Únii, zdaniteľnou osobou presiahne v prebiehajúcom kalendárnom roku 100 000 eur, je zdaniteľná osoba povinná prestať uplatňovať osobitnú úpravu počnúc dodaním, ktorým bol tento obrat presiahnutý; zdaniteľná osoba je súčasne povinná do 15 pracovných dní od tohto dňa podať výkaz podľa odseku 8 za obdobie od začiatku príslušného kalendárneho štvrťroka do dňa, v ktorom hodnota bez dane dodaných tovarov a služieb, ktoré sa zahŕňajú do ročného obratu v Únii, presiahla 100 000 eur.”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

VAT registration application (§ 4)

Daň z pridanej hodnoty (VAT) · One-off · registration

within 5 business days of the day the EUR 50,000 or EUR 62,500 turnover threshold was passed (§ 4 ods. 1) Verified 2026-09-07
Who files
Taxable persons whose turnover passes EUR 50,000 in a calendar year, or EUR 62,500 during the current calendar year — turnover excludes supplies exempt under §§ 28 to 36 and §§ 40 to 42
Notes
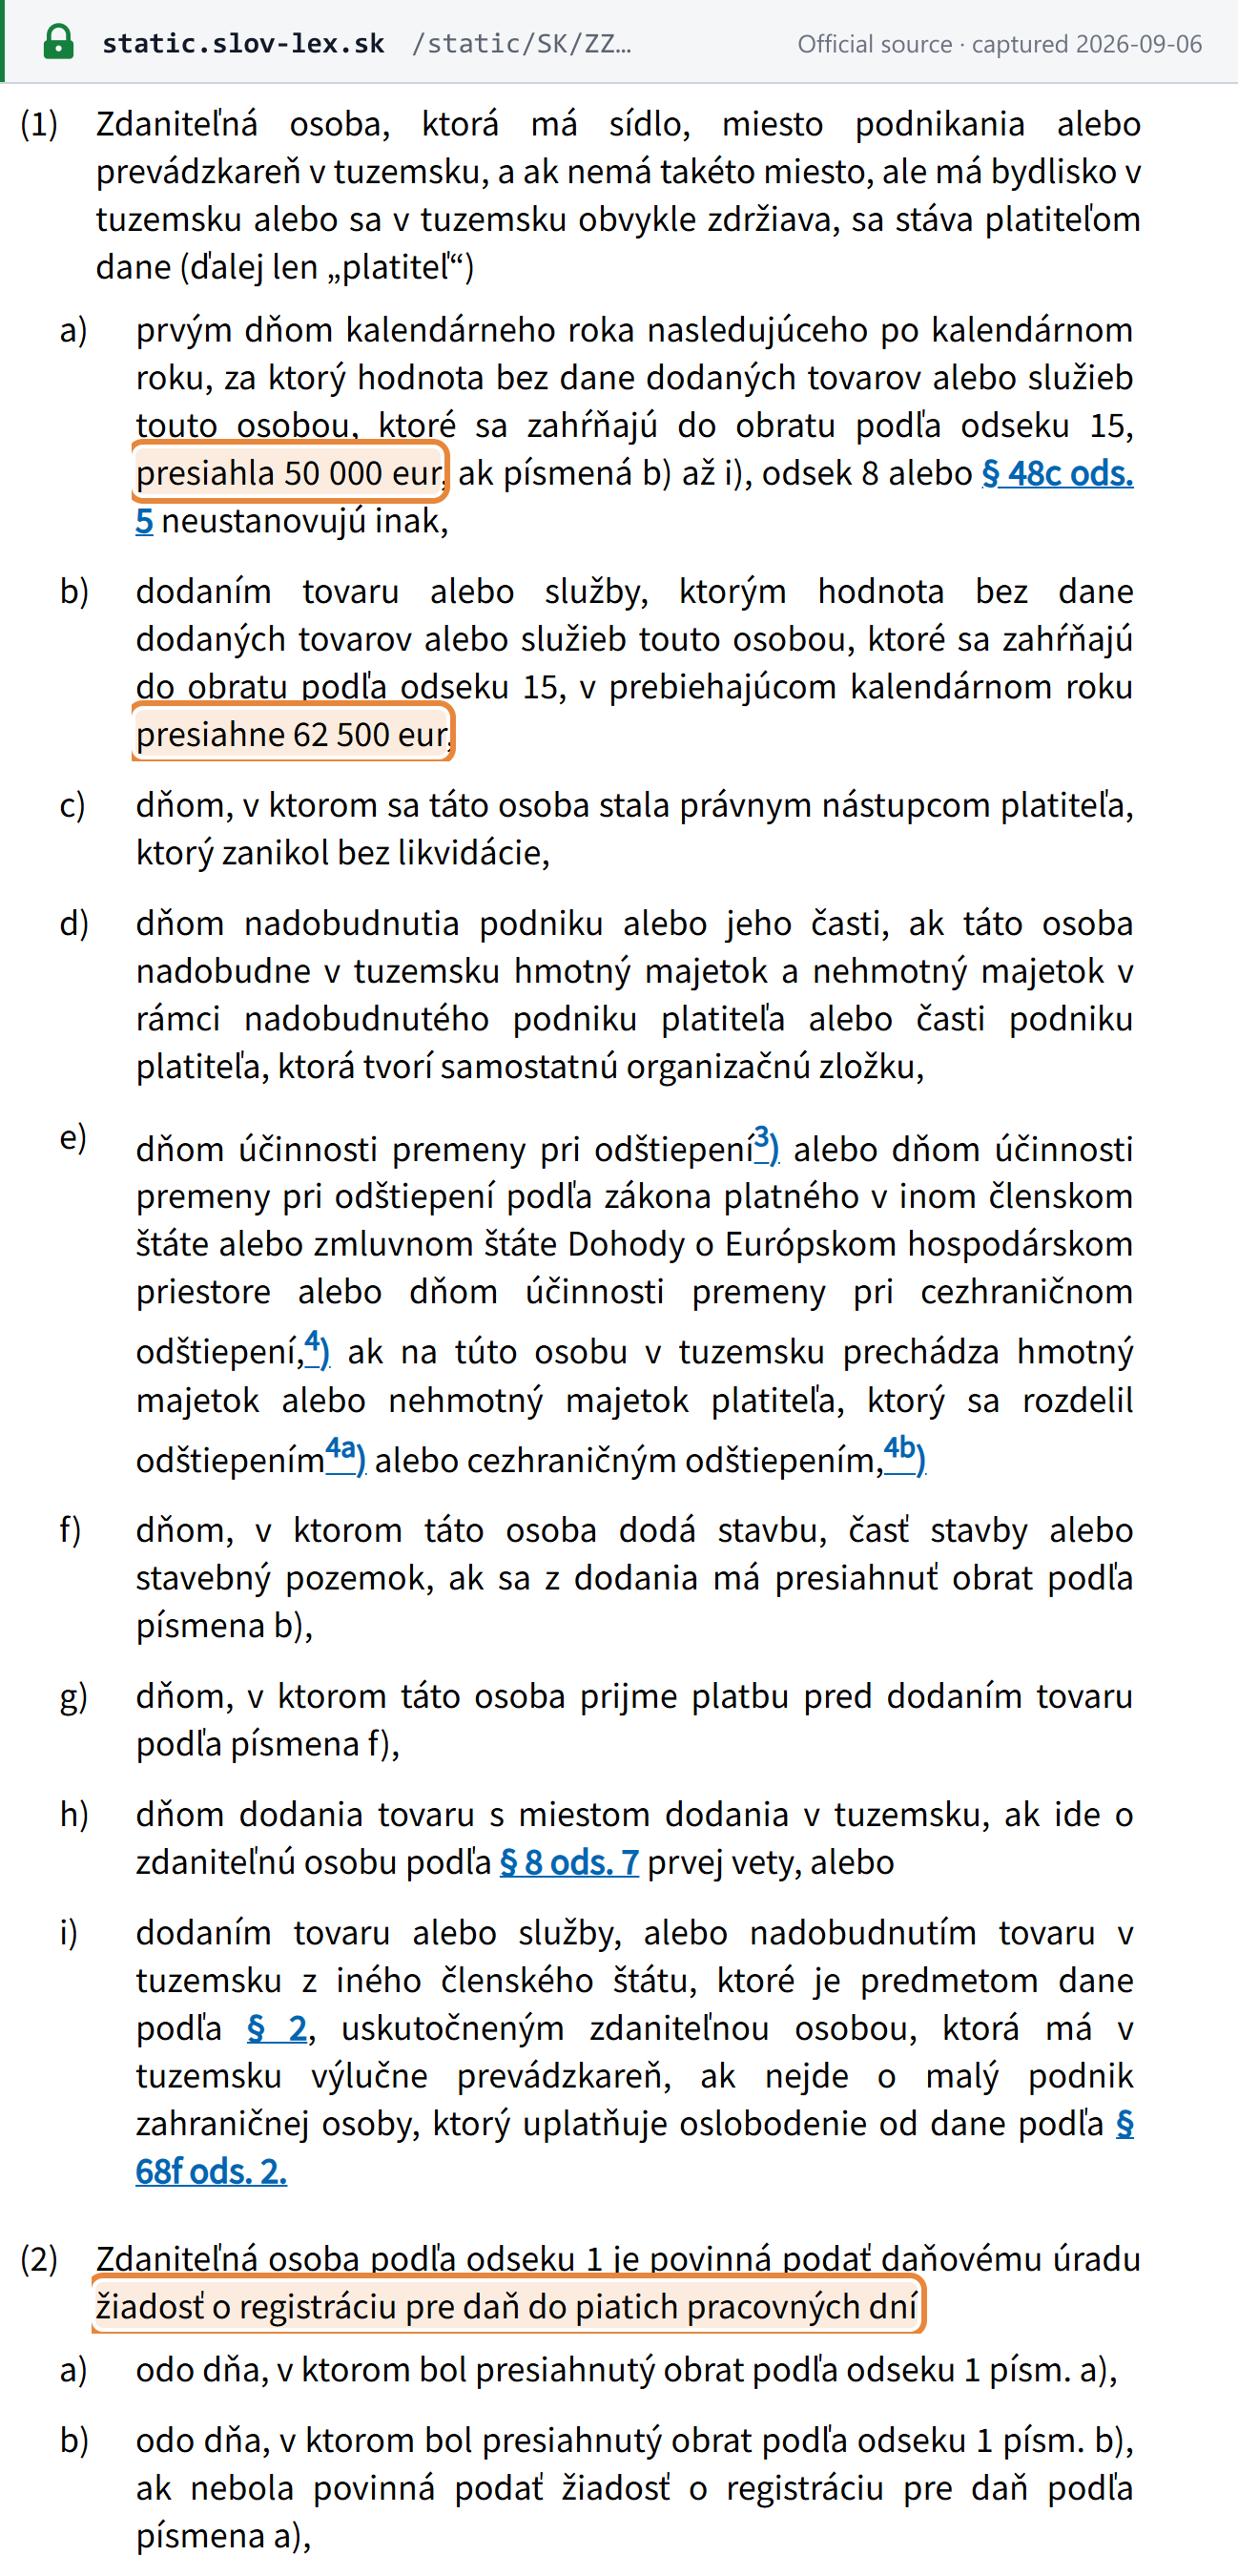
Five working days, and this is the change people miss: before 2025 you had until the 20th of the following month, so the window went from as much as fifty days to five. There are two thresholds and they behave differently — passing EUR 50,000 in a calendar year makes you a payer from 1 January following, while passing EUR 62,500 during the current year makes you one on the very supply that breaches it. If a VAT number has not been assigned by the time your first return is due, you get five working days from delivery of the registration decision to file the return, pay, and file the control and EC sales statements.
Source
Zákon č. 222/2004 Z. z. o DPH — § 4 ods. 1 a ods. 2 (registračná povinnosť) Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Zdaniteľná osoba podľa odseku 1 je povinná podať daňovému úradu žiadosť o registráciu pre daň do piatich pracovných dní”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the VAT registration application (§ 4) deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Spotrebná daň — monthly return and payment

Spotrebné dane (excise duties) · Monthly · return filing

25th of the month after the month ends Verified 2026-09-07
Who files
Tax-warehouse keepers and registered consignees who repeatedly receive excise goods under duty suspension, across all four excise Acts: Mineral oil (zákon č. 98/2004 Z. z. § 14), spirits, wine, beer and intermediate products (zákon č. 530/2011 Z. z. § 12), tobacco products and smokeless tobacco (zákon č. 106/2004 Z. z. § 13 and § 19aa), and electricity, coal and natural gas (zákon č. 609/2007 Z. z. §§ 12, 24 and 36)
Notes
Warehouse keepers and repeat registered consignees file with the customs office and pay by the 25th of the month after the liability arose — and so does every payer of the electricity, coal and natural gas duties, whose Act gives them no other cadence. The return is due even for a month in which no liability arose at all, and if you are a warehouse keeper or a repeat consignee there is no small-amount escape from that: the EUR 5 waiver in the mineral oil, alcohol and tobacco Acts expressly does not reach you. It does reach electricity, coal and gas payers. Smaller cadences sit alongside this one on the same 25th, including small independent breweries and fruit-grower distilling.
Source
Zákon č. 98/2004 Z. z. o spotrebnej dani z minerálneho oleja — § 14 ods. 2 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
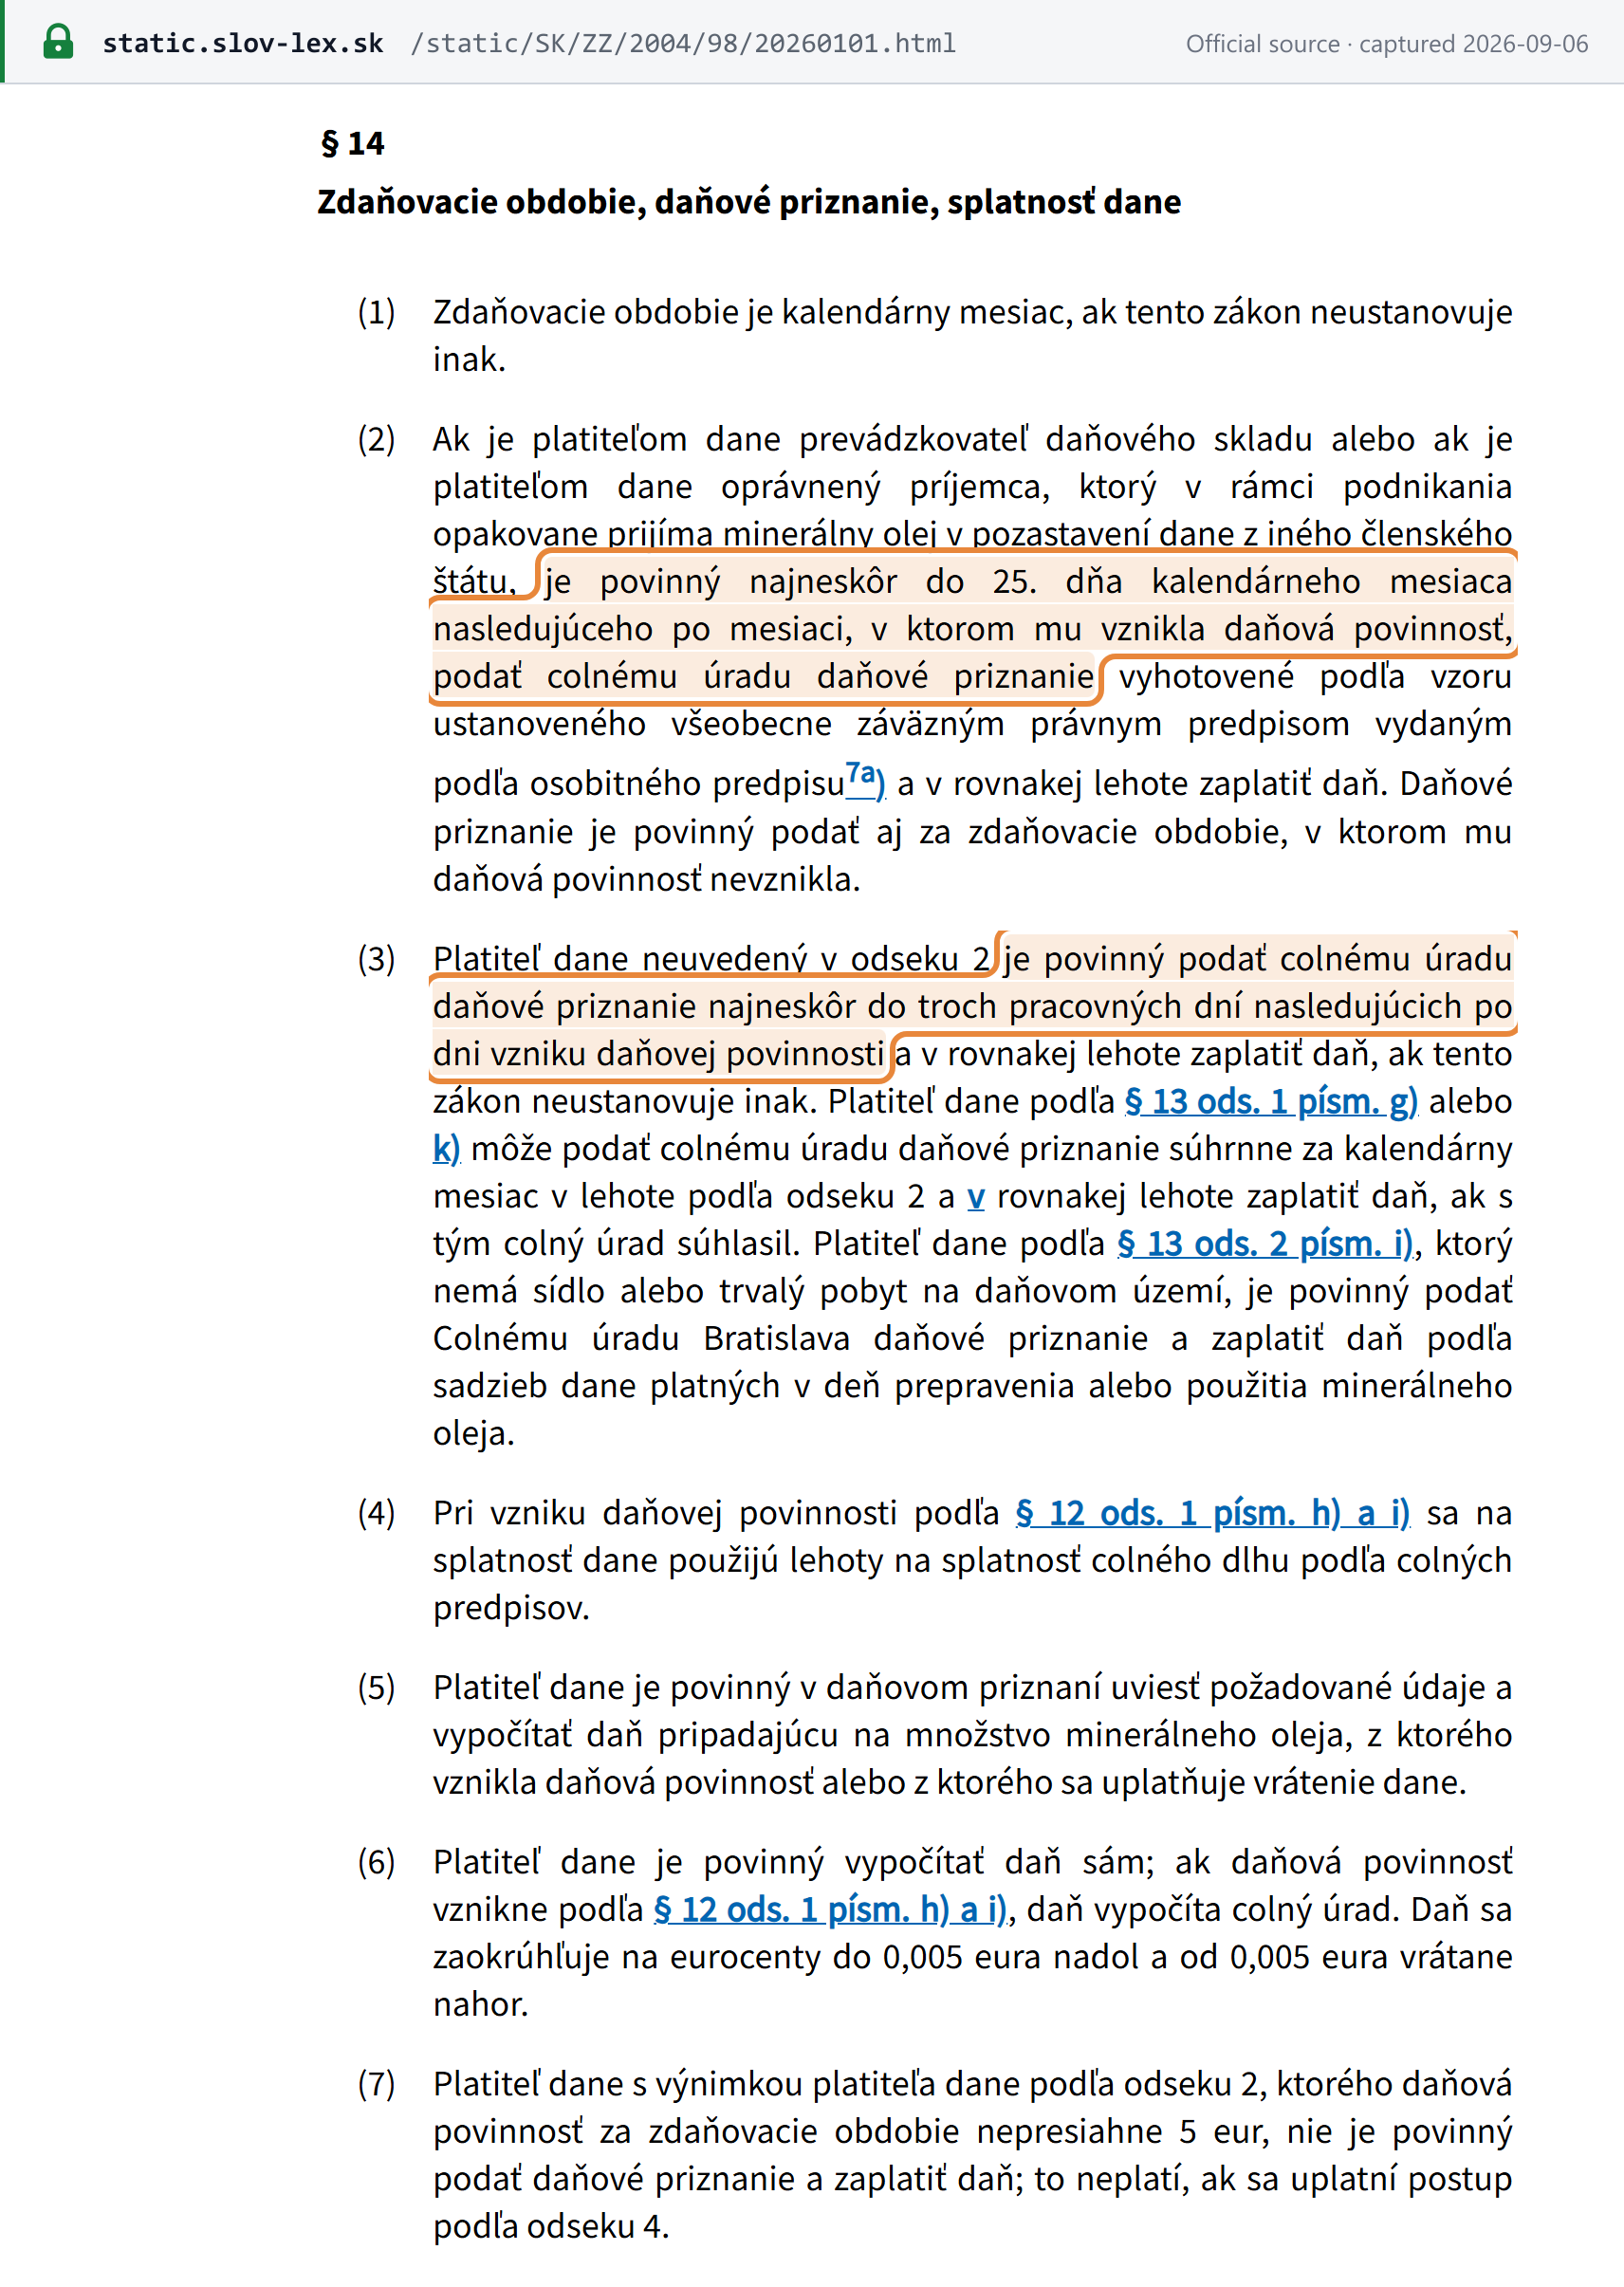
“Ak je platiteľom dane prevádzkovateľ daňového skladu alebo ak je platiteľom dane oprávnený príjemca, ktorý v rámci podnikania opakovane prijíma minerálny olej v pozastavení dane z iného členského štátu, je povinný najneskôr do 25. dňa kalendárneho mesiaca nasledujúceho po mesiaci, v ktorom mu vznikla daňová povinnosť, podať colnému úradu daňové priznanie”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Spotrebná daň — monthly return and payment deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Spotrebná daň — return and payment within three working days

Spotrebné dane (excise duties) · One-off · return filing

within 3 business days of the day the excise liability arose Verified 2026-09-07
Who files
Every other excise taxpayer under the mineral oil, alcohol and tobacco Acts — anyone who is not a tax-warehouse keeper or a repeat registered consignee. It does NOT reach electricity, coal or natural gas, whose Act has no three-day arm: every payer of those three is on the 25th
Notes
If you are not a warehouse keeper or a repeat registered consignee, you do not get to the 25th: the return and the payment are both due within three working days of the day the liability arose. It is the shortest recurring deadline in Slovak indirect tax and it runs from each individual event rather than from a period end. A private distiller of spirits is on this arm; a fruit-grower distilling under the concession is not. This arm exists only for mineral oil, alcohol and tobacco — there is no equivalent for electricity, coal or gas. Where your liability for a period is EUR 5 or less you need neither file nor pay.
Source
Zákon č. 98/2004 Z. z. o spotrebnej dani z minerálneho oleja — § 14 ods. 3 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Platiteľ dane neuvedený v odseku 2 je povinný podať colnému úradu daňové priznanie najneskôr do troch pracovných dní nasledujúcich po dni vzniku daňovej povinnosti a v rovnakej lehote zaplatiť daň, ak tento zákon neustanovuje inak.”
Screenshot of Slov-Lex — Zbierka zákonov Slovenskej republiky showing the Spotrebná daň — return and payment within three working days deadline Open full size Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Daň z poistenia (insurance premium tax) — quarterly

Daň z poistenia (insurance premium tax) · Quarterly · return filing

last day of the month after the quarter ends Verified 2026-09-07
Who files
Insurers, policyholders and legal persons charged with insurance costs who are liable to account for Slovak insurance premium tax
Notes
The period is the calendar quarter and both the return and the tax are due by the end of the following month. Unlike the VAT control statement, a quarter in which no tax became payable needs no return at all. If you owe a return but have no Slovak tax identification number, you must apply for registration within five days of the quarter ending — calendar days here, not the working days the VAT registration rule counts.
Source
Zákon č. 213/2018 Z. z. o dani z poistenia — § 10 ods. 1, 2 a 7 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Platiteľ je povinný podať daňové priznanie do konca kalendárneho mesiaca nasledujúceho po skončení zdaňovacieho obdobia. Platiteľ nie je povinný podať daňové priznanie, ak mu v zdaňovacom období nevznikla povinnosť platiť splatnú daň alebo mu nevznikla povinnosť podľa § 7 ods. 1 a 2.”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Daň zo sladených nealkoholických nápojov (sugary-drinks levy)

Daň zo sladených nealkoholických nápojov · Monthly · return filing

25th of the month after the month ends Verified 2026-09-07
Who files
Persons liable for the levy on the first supply of sweetened non-alcoholic drinks in Slovakia, in force since 1 January 2025
Notes
The sugary-drinks levy runs on exactly the same monthly rhythm as VAT — 25 days after the month in which the liability arose, filed electronically, with the tax payable in the same period. An exporter reclaiming the levy files on its own 25-day cycle counted from the month the entitlement arose. First liability also triggers a five-day notification or registration duty, in calendar days.
Source
Zákon č. 251/2024 Z. z. o dani zo sladených nealkoholických nápojov — § 10 ods. 1 a ods. 2 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Platiteľ dane je povinný podať daňové priznanie do 25 dní po skončení zdaňovacieho obdobia, v ktorom mu vznikla daňová povinnosť podľa § 6 alebo v ktorom opravil základ dane podľa § 7 ods. 4”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Daň z finančných transakcií — monthly

Daň z finančných transakcií (financial transactions tax) · Monthly · payment

last day of the month after the month ends Verified 2026-09-07
Who files
Payment service providers and self-assessing taxpayers accounting for the levy on debits from business accounts, in force since 1 April 2025
Notes
The bank calculates the levy, collects it from the account holder and remits it by the end of the month following the period, filing a statement of the amount within the same window — the Act treats that statement as a tax return. The period is the calendar month, except for the levy on payment-card usage, which is charged for the calendar year in which the card was used. A business that is itself a payment service provider accounts for its own transactions on the same timetable.
Source
Zákon č. 279/2024 Z. z. o dani z finančných transakcií — § 9 a § 10 ods. 1 Slov-Lex — Zbierka zákonov Slovenskej republiky
See the source text
“Platiteľ dane je povinný vypočítať daň, vybrať ju od daňovníka a odviesť takto vybraté dane za príslušné zdaňovacie obdobie správcovi dane najneskôr do konca kalendárneho mesiaca bezprostredne nasledujúceho po zdaňovacom období. V rovnakej lehote je platiteľ dane povinný predložiť správcovi dane oznámenie o výške dane.”
Captured from Slov-Lex — Zbierka zákonov Slovenskej republiky on 2026-09-07

Slovak deadlines move FORWARD when they land on a Saturday, a Sunday or a public day of rest — except on the One-Stop-Shop, import-scheme and small-enterprise rows, where four provisions of the VAT Act switch that off by name and the deadline stands on the non-working day itself. The tax authority publishes both behaviours in one calendar, shifting the domestic return to 26 October and 28 December 2026 while leaving 31 January, 28 February, 31 May and 31 October as live weekend deadlines. The list of non-working days here is the days-of-rest list and not the state-holiday list: 1 September, 28 October and 17 November are state holidays but ordinary working days for deadlines, and 8 May and 15 September are suspended as days of rest for 2026 only. There is no annual VAT return — the year-end input-tax adjustment is settled inside the last periodic return of the year. Excise is covered for all eight commodity families across the four excise Acts, in two rows rather than eight, because every one of them shares the same deadline. Not covered, and named rather than left silent: the report a foreign small enterprise owes when it misses the equivalent duty in its own member state, which runs from the expiry of a foreign deadline and has no domestic trigger; the mid-quarter escalation that splits an open quarter into three monthly EC sales statements; and the several registration duties Slovak law states as falling "before" an event with no notice period at all. Income tax, payroll withholding, motor-vehicle tax, the Pillar Two top-up tax and the levies on financial institutions and regulated industries are out of scope for this calendar.

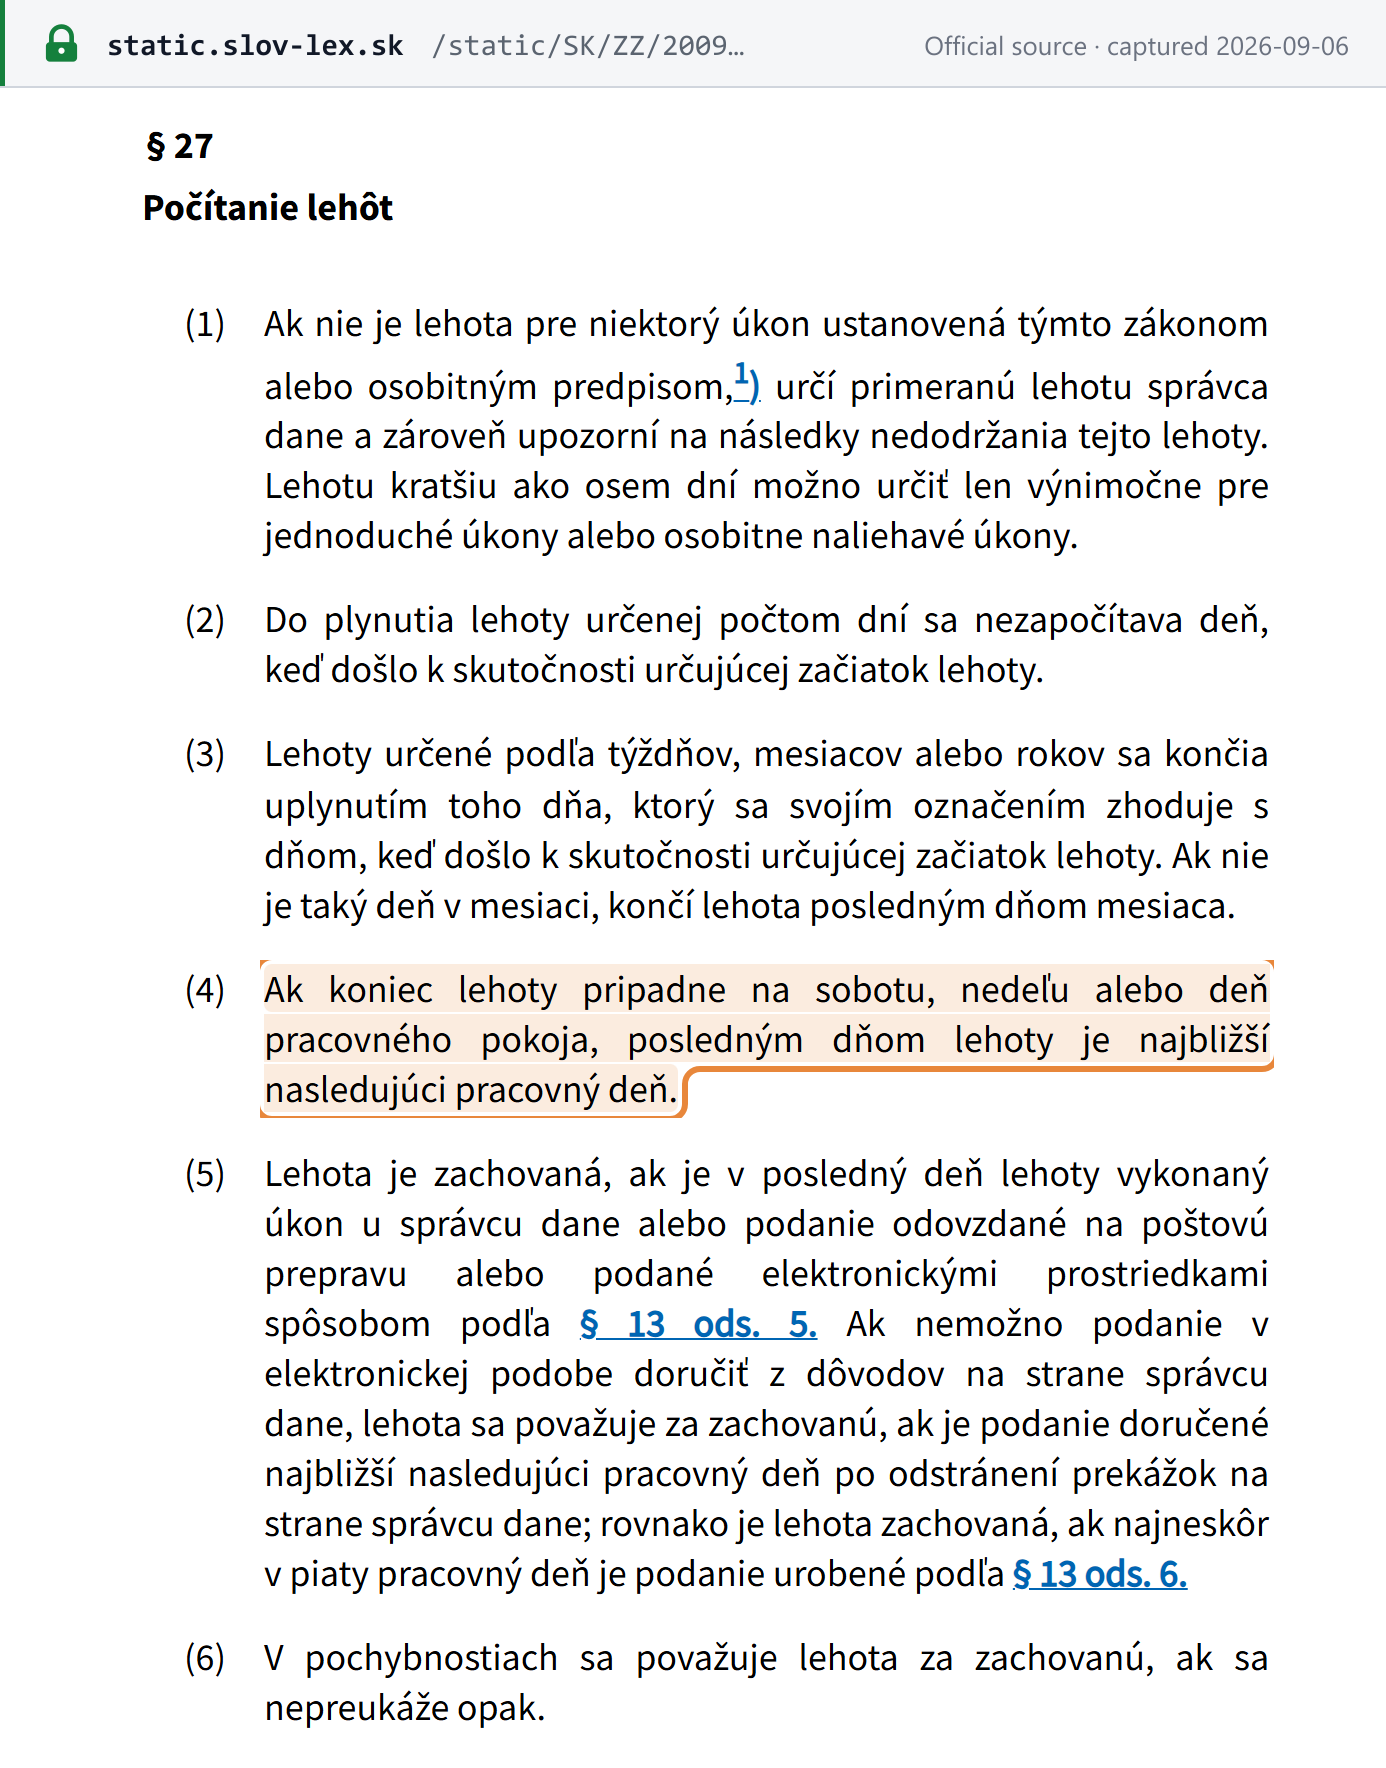
“Ak koniec lehoty pripadne na sobotu, nedeľu alebo deň pracovného pokoja, posledným dňom lehoty je najbližší nasledujúci pracovný deň.”
Screenshot of the official source stating the rule that governs Slovakia's deadlines
Zákon č. 563/2009 Z. z. o správe daní (daňový poriadok) — § 27 ods. 4 — Slov-Lex — Zbierka zákonov Slovenskej republiky, captured 2026-09-07

What this calendar does not list

  • Not applicable Annual or reconciliation return — Slovakia has no annual VAT return and no annual reconciliation return, and that was tested rather than assumed. The tax-period provision is exhaustive and offers only the calendar month and the calendar quarter; a full-text search of the consolidated VAT Act in force returns no occurrence of an annual return, an annual settlement or a calendar-year tax period. The one thing that looks like a reconciliation — the § 50 input-tax pro-rata for the year — is settled INSIDE the last periodic return of the calendar year, on the ordinary 25-day deadline, and the authority lists it among the situations requiring a control statement carrying no transaction data. Neither the insurance premium tax, the sugary-drinks levy nor any of the four excise Acts has an annual return either.
  • Not yet covered E-invoicing / e-reporting cycle — Slovakia has legislated a B2B e-invoicing and data-reporting regime — § 85o of the VAT Act, inserted by zákon č. 385/2025 Z. z. — and it arrives in three stages, not one. Odseky 18 to 22 are already in force from 1 January 2026, and their live effect is to remove the requirement for the recipient to consent to an electronic invoice. Mandatory B2B e-invoice ISSUANCE and a transitional per-invoice reporting duty commence 1 January 2027 (odseky 1 to 16 and 23). The permanent domestic reporting regime — a new § 80a — commences 1 July 2030, alongside odseky 17 and 24, and on the same date the recapitulative statement in § 80 is replaced by per-transaction cross-border reporting. There is no phasing by taxpayer size at any stage: from the first day it reaches every VAT payer registered under § 4, § 4b or § 4c. Even after commencement the reporting duty runs from each individual taxable transaction rather than from a period — five days per invoice — and is discharged by handing the invoice to an accredited delivery service run by a certified provider registered with the Financial Directorate, so it may well never produce a calendar date. Marked a gap rather than not-applicable because it is a real obligation with known start dates, and this file has not modelled it.

About this calendar

Which Slovakia tax deadlines does this calendar cover?

18 recurring indirect-tax obligations — Daň z pridanej hodnoty (VAT), Spotrebné dane (excise duties), Daň z poistenia (insurance premium tax), Daň zo sladených nealkoholických nápojov and Daň z finančných transakcií (financial transactions tax) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-09-07). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.