Austria lets the acquirer omit the tax declaration where a Parteienvertreter pays the tax, from 1 July 2026
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 30 June 2026
- Effective
- 1 July 2026
- Authority
- Rechtsinformationssystem des Bundes (RIS)
- Systems
- Reporting
- Verified
- Fetched from official source · medium confidence
Acquirers in Austria whose tax is calculated and paid by a Parteienvertreter under section 11(5) NoVAG 1991.
No action — monitoring only (vehicle-acquisition tax-return procedure).
Reporting
Article 2 of the Budgetmaßnahmengesetz 2026 (BGBl. I Nr. 43/2026, 30 June 2026) adds a second subparagraph to Art. 21 para. 2 of the UStG 1994 Annex (Binnenmarktregelung): where the tax is calculated and paid by a Parteienvertreter under section 11(5) NoVAG 1991, the acquirer's tax declaration may be omitted. Section 28(70) UStG provides that the provision enters into force on 1 July 2026 and applies first to supplies and other events after 30 June 2026.
What changed in detail
Article 2 of the Budgetmaßnahmengesetz 2026 (BGBl. I Nr. 43/2026, dated 30 June 2026) adds a second subparagraph to Art. 21 para. 2 of the Annex to the UStG 1994 (the Binnenmarktregelung).
Where the tax is calculated and paid by a Parteienvertreter under section 11(5) NoVAG 1991, the acquirer’s tax declaration may be omitted. Section 11(5) to (7) NoVAG 1991 applies by analogy.
Section 28(70) UStG provides that the provision enters into force on 1 July 2026 and applies first to supplies and other events after 30 June 2026.
What it means
The relief is narrow. It removes the acquirer’s separate tax declaration only when a Parteienvertreter has calculated and paid the tax under the NoVAG route; in every other intra-Community acquisition the declaration duty is unchanged. Acquirers should confirm with their representative that the tax is in fact being paid through that route before dropping the declaration, and note that the rule applies only to events after 30 June 2026.
Proof
Wird die Steuer von einem Parteienvertreter gemäß § 11 Abs. 5 NoVAG 1991 berechnet und entrichtet, kann die Steueranmeldung durch den Erwerber unterbleiben. § 11 Abs. 5 bis 7 NoVAG 1991 gilt sinngemäß.Where the tax is calculated and paid by a Parteienvertreter (party representative) under section 11(5) NoVAG 1991, the acquirer's tax declaration may be omitted. Section 11(5) to (7) NoVAG 1991 applies by analogy.
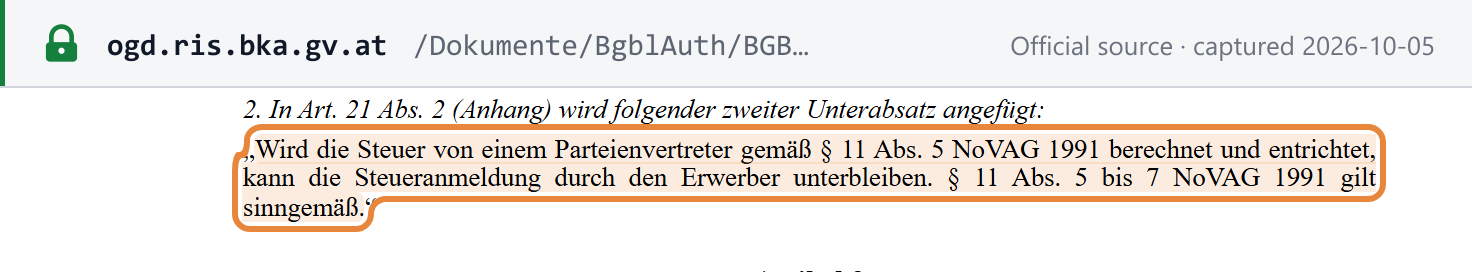 Source snapshot of the official page. Open full size ↗