Bolivia sets the invoicing procedure for the Law 1755 IVA exemption on productive inputs and capital goods (RND 102600000039)
This page records one dated change. For the rules in Bolivia as they stand today, see the Bolivia guide →
- Jurisdiction
- Bolivia
- Tax
- VAT
- Change type
- Invoice rules
- Status
- In force
- Impact
- Action required
- Announced
- 9 October 2026
- Effective
- 9 October 2026
- Authority
- Servicio de Impuestos Nacionales (SIN), Bolivia
- Systems
- Invoicing, ERP, Tax engine
- Verified
- Fetched from official source · high confidence
Bolivian taxpayers making the first domestic sale of exempt productive inputs, seeds, drones, machinery and capital goods under Article 9 of Law 1755.
Sellers of exempt productive goods must issue exempt invoices via the dedicated SIN billing option and add the Ley 1755 economic activity.
InvoicingERPTax engine
Bolivia's SIN issued Resolucion Normativa de Directorio No. 102600000039 (La Paz, 9 October 2026) setting the invoicing procedure for the IVA exemption under Article 9 of Law 1755 and Supreme Decree 5709: first domestic sales of exempt productive inputs, seeds, drones, machinery and capital goods must be invoiced without tax-credit entitlement through the 'Facturacion Bienes e Insumos Productivos Ley N 1755' option in the Sistema de Facturacion of the virtual tax office; the option and the added economic activity are temporary, for the Article 9 period.
What changed in detail
Resolución Normativa de Directorio No. 102600000039, issued in La Paz on 9 October 2026, sets the invoicing procedure for the IVA exemption under Article 9 of Law 1755 and Supreme Decree 5709.
First domestic sales of the exempt productive inputs, seeds, drones, machinery and capital goods must be invoiced without tax-credit entitlement. The seller issues them through the ‘Facturación Bienes e Insumos Productivos Ley N° 1755’ option in the Sistema de Facturación of the virtual tax office. Both that option and the added economic activity are temporary, for the period covered by Article 9.
What it means
This is the operational layer on top of the exemption itself. A seller of exempt goods needs the dedicated billing option and the added Ley 1755 economic activity in place before issuing exempt invoices. Because the invoices carry no tax-credit entitlement, buyers should not expect to claim IVA credit on them.
Proof
La presente Resolución tiene por objeto establecer el procedimiento para la facturación con exención del IVA en el marco del Artículo 9 de la Ley N° 1755 y de los parágrafos I y II del Artículo 3 del Decreto Supremo N° 5709.The purpose of this Resolution is to establish the procedure for invoicing with IVA exemption under Article 9 of Law No. 1755 and paragraphs I and II of Article 3 of Supreme Decree No. 5709.
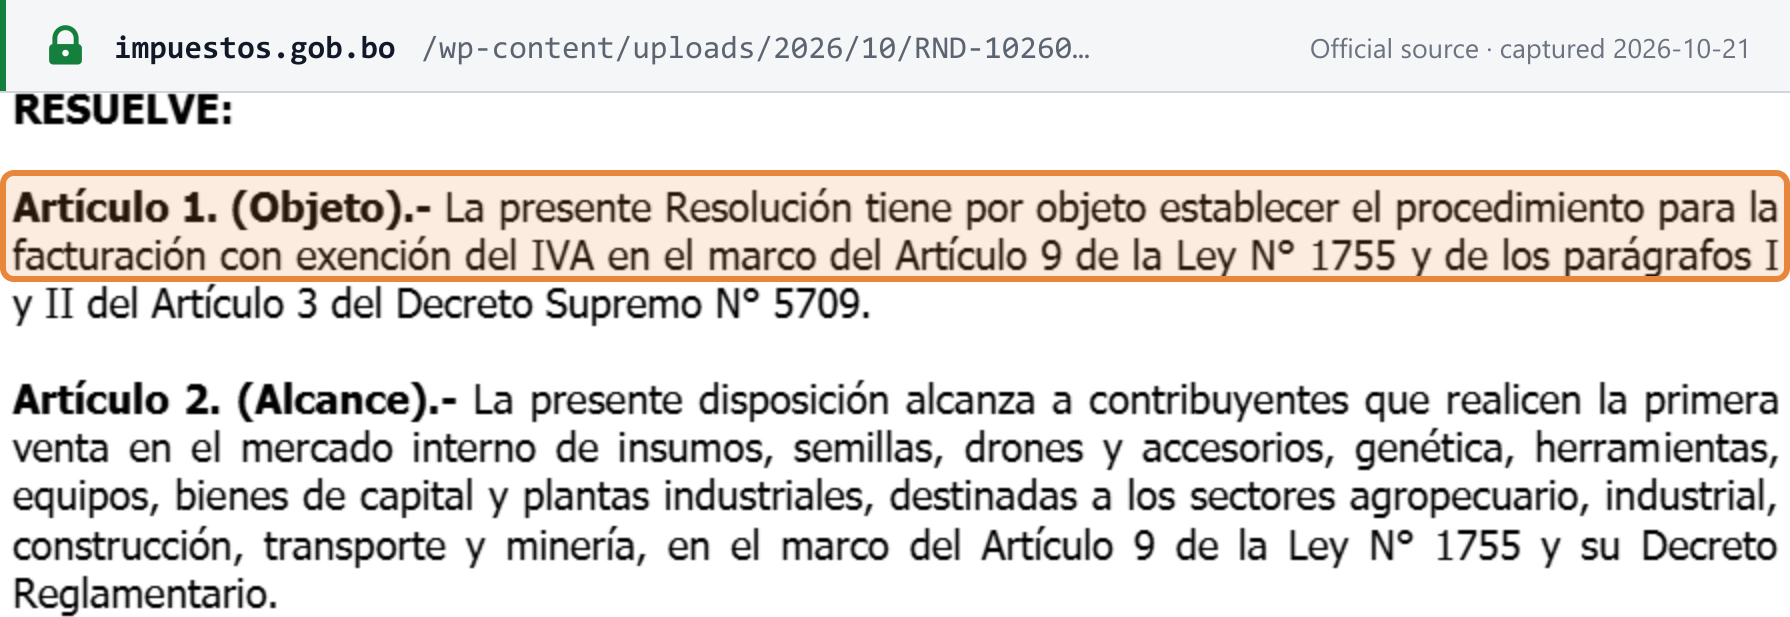 Source snapshot of the official page. Open full size ↗