Bulgaria drafts a zero VAT rate for SAFE defence-instrument supplies, proposed from 1 January 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Bulgaria as they stand today, see the Bulgaria guide →
- Jurisdiction
- Bulgaria
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 23 September 2026
- Effective
- 1 January 2027
- Authority
- Министерство на финансите (Ministry of Finance, Bulgaria)
- Systems
- Tax engine, Invoicing, Customs
- Verified
- Fetched from official source · high confidence
Suppliers and importers of defence products under the EU SAFE instrument in Bulgaria.
Defence suppliers on SAFE-funded contracts: track the draft; no change to current invoicing until enacted.
Tax engineInvoicingCustoms
The draft law amending the Bulgarian VAT Act (consultation 12733-K, open 23 September to 23 October 2026) would add article 173(16): supplies exempted from VAT under article 20 of Council Regulation (EU) 2025/1106 (the SAFE defence instrument) would be taxed at the zero rate, under rules to be set in the implementing regulation. Transitional provision section 100 applies it to supplies, intra-Community acquisitions and imports of defence products made from 29 May 2025 until the law enters into force. Under its section 105 the draft would enter into force on 1 January 2027, except listed e-invoicing provisions (1 January 2028) and article 182a (1 July 2028). It is a draft and not law.
What changed in detail
This is a draft law out for public consultation, not law. The draft amending the Bulgarian VAT Act (consultation 12733-K, open from 23 September to 23 October 2026) would add article 173(16): supplies exempted from VAT under article 20 of Council Regulation (EU) 2025/1106, the SAFE defence instrument, would be taxed at the zero rate, under rules to be set in the implementing regulation.
A transitional provision, section 100, would apply the rule to supplies, intra-Community acquisitions and imports of defence products made from 29 May 2025 until the law enters into force. Under its section 105 the draft would enter into force on 1 January 2027, except listed e-invoicing provisions (1 January 2028) and article 182a (1 July 2028).
What it means
Nothing changes until the amendment is adopted and published. The notable feature is the retroactive transitional rule, which would reach back to 29 May 2025. Suppliers of defence products should not change their invoicing now, but should follow the consultation and the implementing regulation, which would set the procedure for applying the zero rate.
Proof
(16) За доставки, които са освободени от данък върху добавената стойност по силата на чл. 20 от Регламент (ЕС) 2025/1106 на Съвета от 27 май 2025 година за създаване на инструмента „Мерки за сигурността на Европа чрез укрепване на европейската отбранителна промишленост“ (инструмент SAFE) (OВ, L 2025/1106 от 28 май 2025 г.), се прилага нулева ставка на данъка по ред, определен в правилника за прилагане на закона.(16) For supplies that are exempt from value added tax under Article 20 of Council Regulation (EU) 2025/1106 of 27 May 2025 establishing the Security Action for Europe (SAFE) through the Reinforcement of European Defence Industry instrument (OJ L 2025/1106 of 28 May 2025), the zero rate of tax applies under a procedure set out in the implementing regulations.
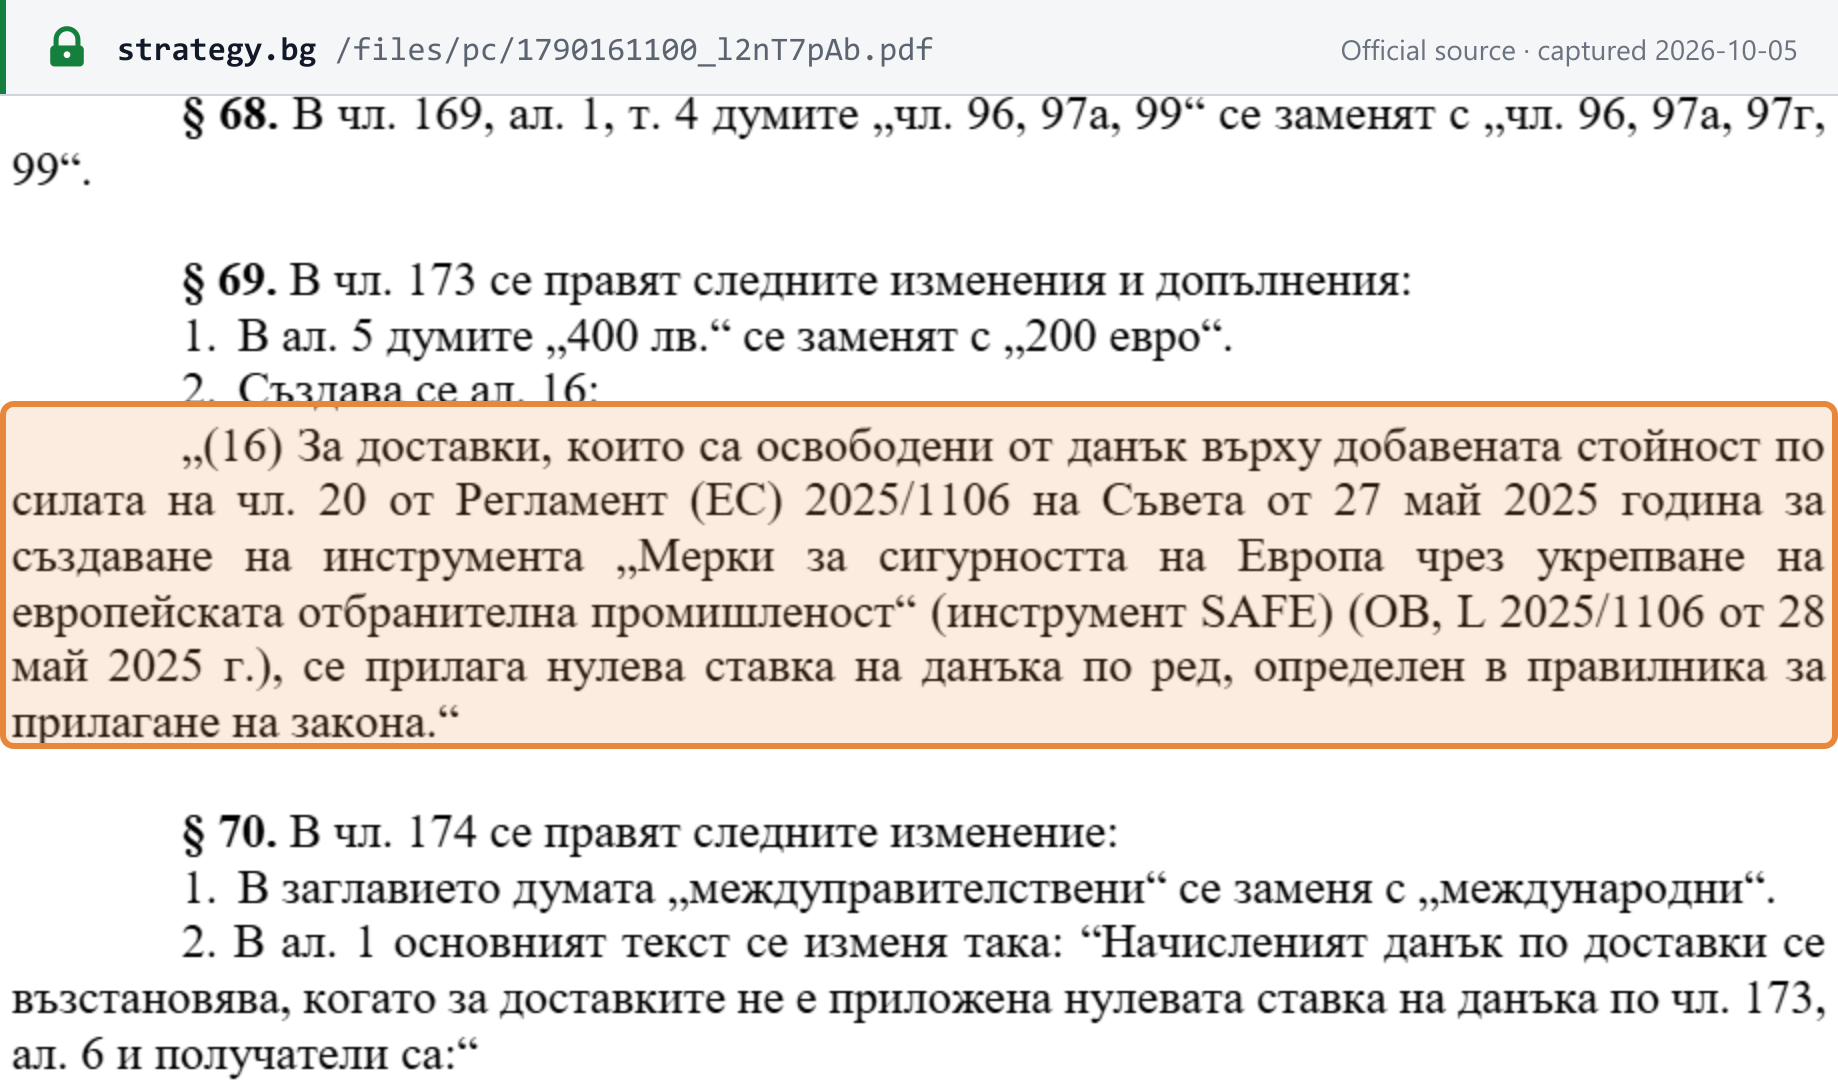 Source snapshot of the official page. Open full size ↗