Bulgaria drafts mandatory VAT registration for sellers of new buildings (article 97g), proposed from 1 January 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Bulgaria as they stand today, see the Bulgaria guide →
- Jurisdiction
- Bulgaria
- Tax
- VAT
- Change type
- Registration
- Status
- Proposed
- Impact
- Watch
- Announced
- 23 September 2026
- Effective
- 1 January 2027
- Authority
- Министерство на финансите (Ministry of Finance, Bulgaria)
- Systems
- Tax engine, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Taxable persons selling new buildings, adjoining land or rights over regulated plots in Bulgaria, including individuals acting as taxable persons.
Property developers and occasional sellers of plots or new buildings: assess exposure to registration from the first supply if enacted.
Tax engineInvoicingReporting
The same draft law (consultation 12733-K) would create article 97g of the VAT Act: any taxable person making taxable supplies in Bulgaria within a calendar year of new buildings (or parts of them, adjoining land and rights in rem over them) or of ownership or building rights over a regulated plot of land would have to register, with the registration application due at least 7 days before the date on which the tax on the supply becomes chargeable, and the supply taxed. Individuals fall under it only when acting as taxable persons in an independent economic activity. A person registered only under article 97g would be denied input VAT credit on other supplies and could not show VAT on invoices for other supplies. Proposed entry into force 1 January 2027.
What changed in detail
This is a draft law out for public consultation, not law. The same draft (consultation 12733-K) would create article 97g of the VAT Act. Any taxable person making taxable supplies in Bulgaria within a calendar year of new buildings (or parts of them, adjoining land and rights in rem over them) or of ownership or building rights over a regulated plot of land would have to register. The registration application would be due at least 7 days before the date on which the tax on the supply becomes chargeable, and the supply would be taxed.
Individuals would fall under the rule only when acting as taxable persons in an independent economic activity.
A person registered only under article 97g would be denied input VAT credit on other supplies and could not show VAT on invoices for other supplies. Entry into force is proposed for 1 January 2027.
What it means
The proposal creates a registration route tied to the type of supply rather than to turnover, so a one-off seller of a new building could be caught. The 7-day lead time means registration would need to be planned before a sale becomes chargeable. The restriction on input credit and on showing VAT for other supplies would make this a narrow, transaction-specific registration, not a full VAT status. All of this remains a draft.
Proof
На регистрация по този закон подлежи всяко данъчно задължено лице, което извършва облагаеми доставки с място на изпълнение на територията на страната в рамките на една календарна година на: 1. нови сгради или на части от тях, на прилежащите към тях терени, както и учредяването и прехвърлянето на други вещни права върху тях; 2. прехвърляне на правото на собственост или учредяването или прехвърлянето на право на строеж върху урегулиран поземлен имот по смисъла на Закона за устройство на територията.Every taxable person who makes taxable supplies with place of performance in the country within one calendar year of: 1. new buildings or parts of them, the land adjoining them, and the creation and transfer of other rights in rem over them; 2. transfer of ownership or creation or transfer of a building right over a regulated plot of land within the meaning of the Spatial Planning Act, is subject to registration under this Act.
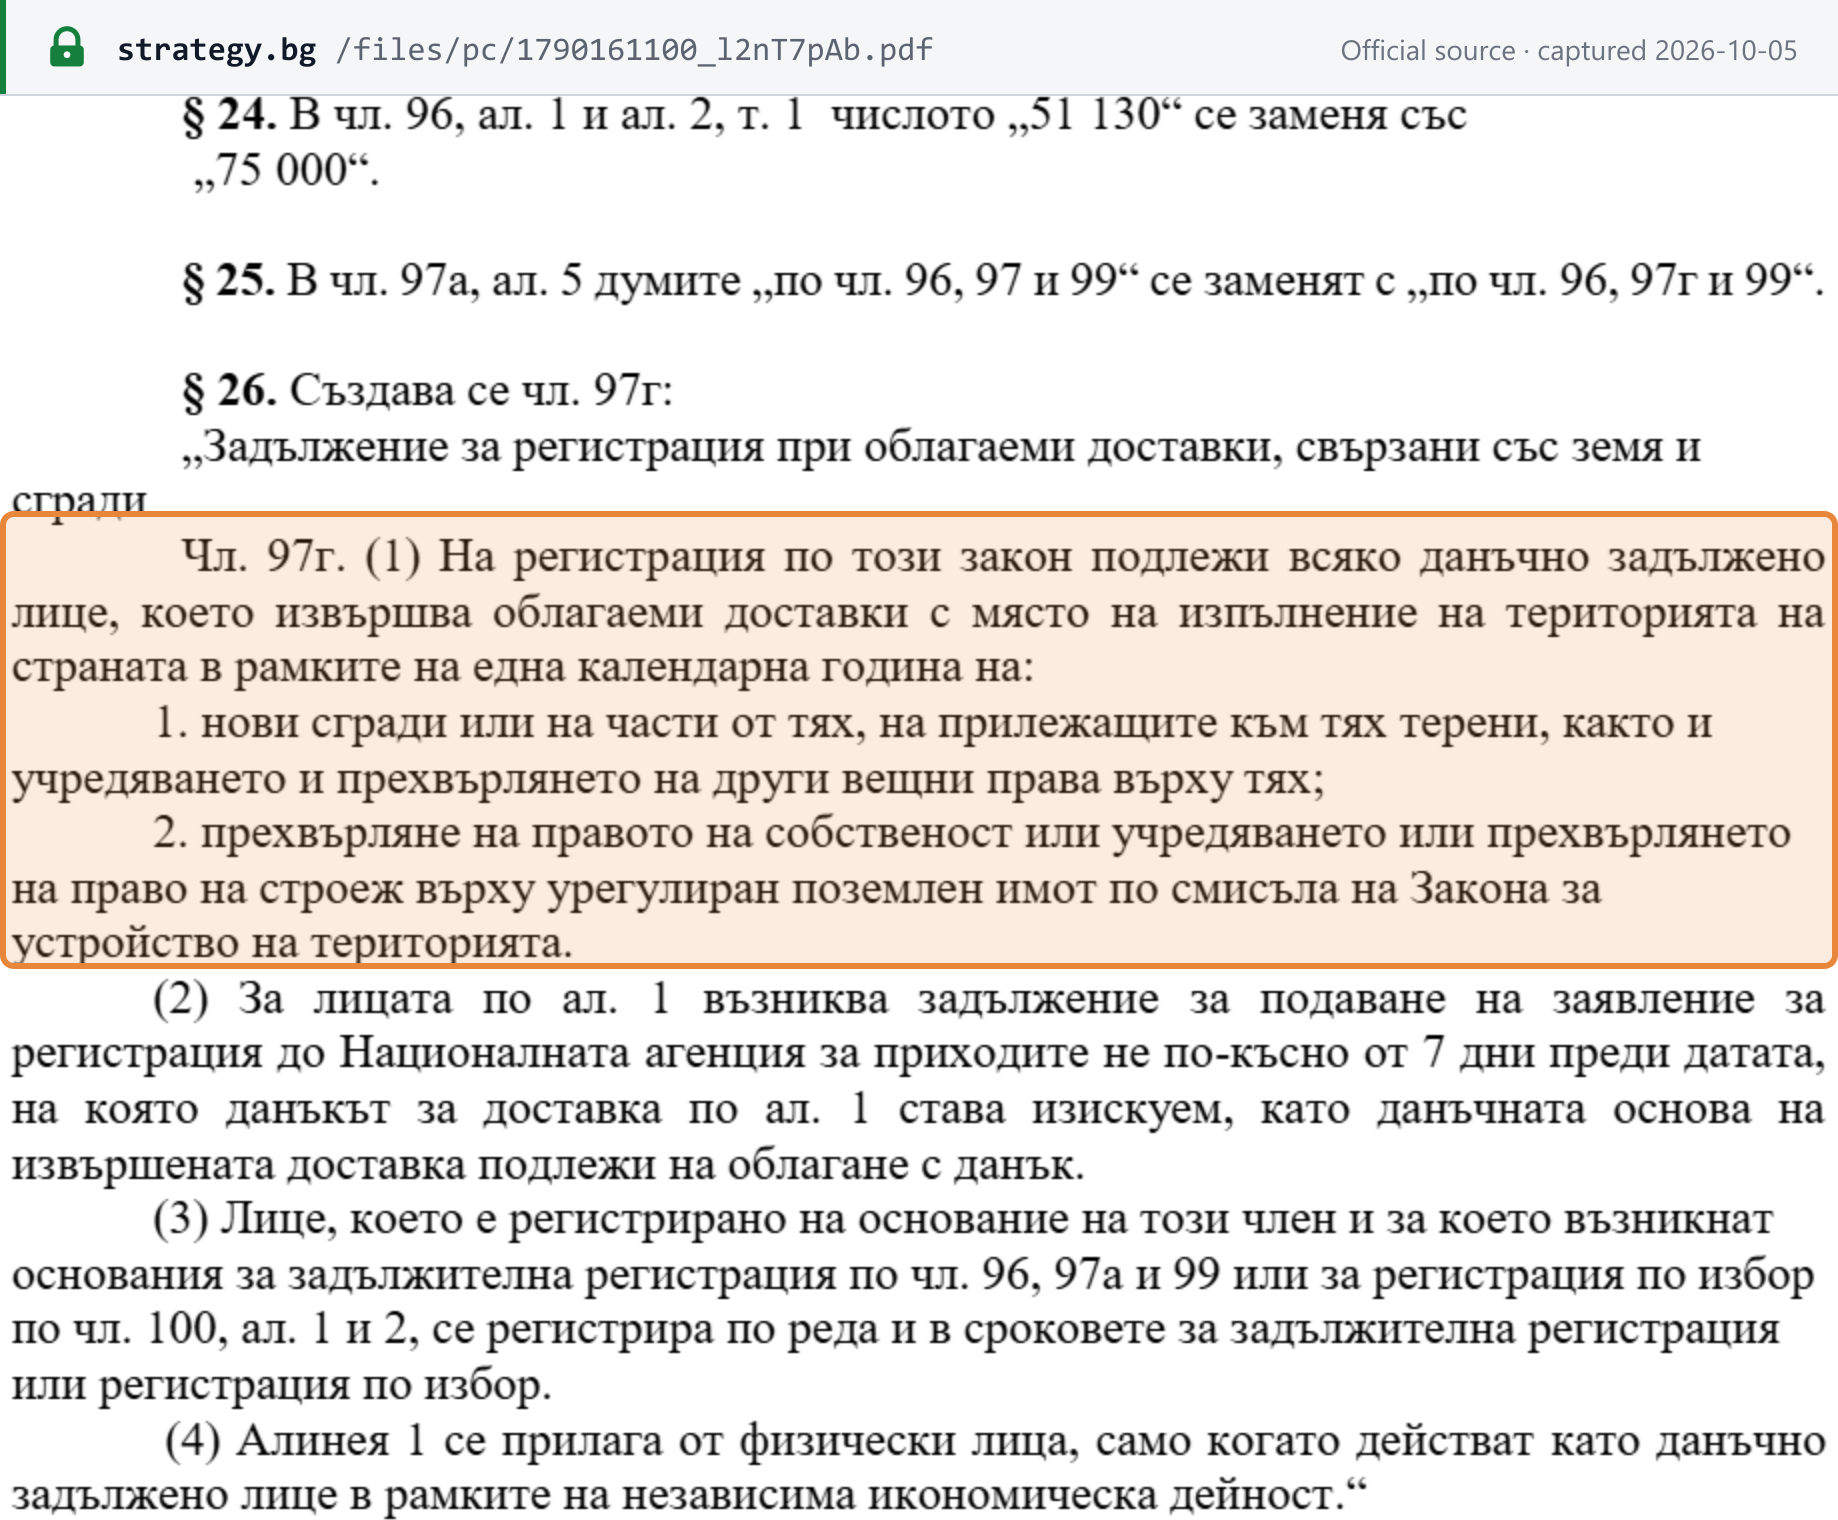 Source snapshot of the official page. Open full size ↗