Bulgaria: draft VAT Act amendment, not yet law, would widen the deemed-supplier rules and treat cross-border energy supplies as distance sales from 2027
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Bulgaria as they stand today, see the Bulgaria guide →
- Jurisdiction
- Bulgaria
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Watch
- Announced
- 23 September 2026
- Effective
- 1 January 2027
- Authority
- Министерство на финансите (Ministry of Finance, Bulgaria)
- Systems
- E-commerce, Tax engine, ERP, Reporting
- Verified
- Fetched from official source · high confidence
Electronic marketplaces and platforms, and non-established suppliers of gas, electricity and heating or cooling to recipients who do not account for VAT on intra-Community acquisitions.
Marketplaces and platforms selling to business or legal-person customers should assess deemed-supplier and OSS exposure; energy suppliers should assess distance-sales treatment.
E-commerceTax engineERPReporting
The Ministry of Finance draft law amending Bulgaria's VAT Act (consultation 12733, open until 23 October 2026) would implement Directive (EU) 2025/516 by widening the recipients covered by the electronic-interface deemed-supplier rules in article 14a: besides non-taxable persons, specified supplies to taxable persons or non-taxable legal persons that are not required to account for VAT on their intra-Community acquisitions would be covered. A new article 14(5) would also treat supplies of gas through a natural gas system, and of electricity or heating/cooling through networks, by a supplier not established in the Member State of supply to such recipients as intra-Community distance sales of goods for the purposes of the Union scheme. The draft's general commencement date is 1 January 2027.
What changed in detail
This is a draft for public consultation, not law. The Ministry of Finance draft law amending Bulgaria’s VAT Act (consultation 12733, open until 23 October 2026) would implement Directive (EU) 2025/516. It would widen the recipients covered by the electronic-interface deemed-supplier rules in article 14a: besides non-taxable persons, specified supplies to taxable persons or non-taxable legal persons that are not required to account for VAT on their intra-Community acquisitions would be covered.
A new article 14(5) would also treat supplies of gas through a natural gas system, and of electricity or heating/cooling through networks, by a supplier not established in the Member State of supply to such recipients as intra-Community distance sales of goods for the purposes of the Union scheme. The draft’s general commencement date is 1 January 2027.
What it means
Platforms would need to check whether sales to business and institutional buyers that do not account for VAT on acquisitions now fall under their deemed-supplier liability. Energy suppliers selling across borders could use the Union scheme for those sales. The wording may change after consultation.
Proof
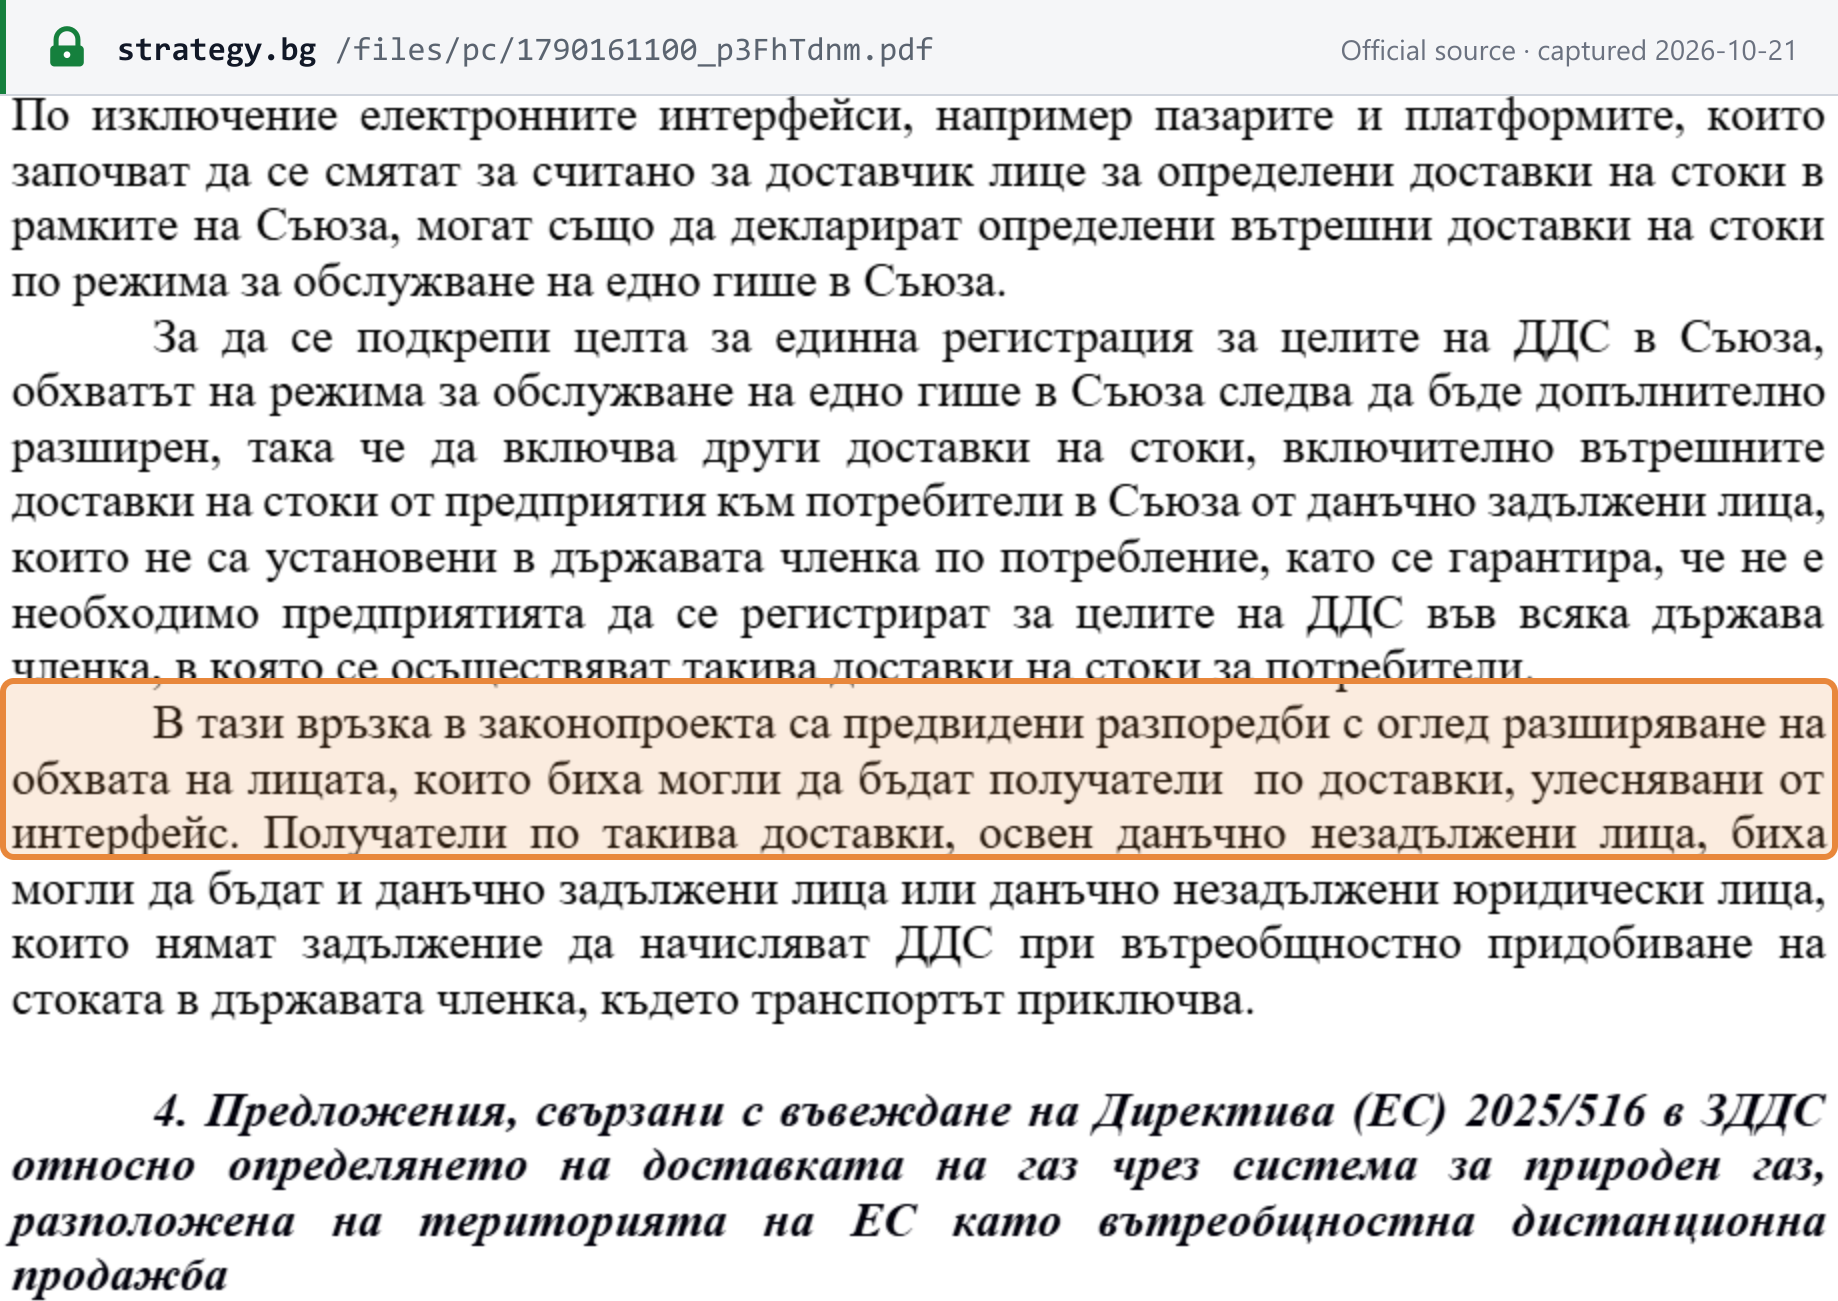
В тази връзка в законопроекта са предвидени разпоредби с оглед разширяване на обхвата на лицата, които биха могли да бъдат получатели по доставки, улеснявани от интерфейс.In this connection the draft law contains provisions to widen the scope of the persons who could be recipients of supplies facilitated by an interface.
 Source snapshot of the official page. Open full size ↗