Burundi makes taxpayers with purchases, imports or stock above BIF 50 million subject to VAT for 2026/2027
This page records one dated change. For the rules in Burundi as they stand today, see the Burundi guide →
- Jurisdiction
- Burundi
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- Action required
- Announced
- 30 June 2026
- Effective
- 1 July 2026
- Authority
- Office Burundais des Recettes (OBR)
- Systems
- ERP, Tax engine, Reporting
- Verified
- Fetched from official source · medium confidence
Burundian taxpayers whose local purchases and imports in a fiscal year, or whose stock of raw materials, finished or semi-finished goods or merchandise, exceed BIF 50,000,000 (investments and personal effects excluded).
Test Burundian entities against the BIF 50 million purchases/imports and stock triggers, not only the BIF 25 million turnover threshold, for the 2026/2027 budget year.
ERPTax engineReporting
Article 271 of Burundi's 2026/2027 Finance Law (Loi n° 1/10 of 30 June 2026) provides that, for budget management 2026/2027, a taxpayer whose local purchases and/or imports in a fiscal year exceed BIF 50,000,000 (excluding investments and personal effects) is automatically subject to VAT and must enter the medium or large taxpayer category; the same applies to a taxpayer holding stock of raw materials, finished or semi-finished goods or merchandise worth more than BIF 50,000,000. VAT invoicing starts from the first day of the month following the month in which the threshold is reached. This sits alongside the BIF 25,000,000 turnover threshold and BIF 5,000,000 optional threshold set in the same article.
What changed in detail
Article 271 of Burundi’s Finance Law for budget year 2026/2027 (Loi n° 1/10 of 30 June 2026, page 66 of the promulgated text) provides that, for budget management 2026/2027, a taxpayer whose local purchases and/or imports in a fiscal year exceed BIF 50,000,000, excluding investments and personal effects, is automatically subject to VAT and must enter the medium or large taxpayer category.
The same applies to a taxpayer that holds stock of raw materials, finished or semi-finished goods or merchandise worth more than BIF 50,000,000. VAT invoicing starts from the first day of the month following the month in which the threshold is reached.
These triggers sit alongside the BIF 25,000,000 turnover threshold and the BIF 5,000,000 optional threshold set in the same article.
What it means
The BIF 25 million turnover threshold is no longer the only test. A business with modest sales but large purchases, imports or stock can be pulled into VAT and into the medium or large taxpayer category, and its VAT invoicing must start from the following month.
Test Burundian entities against all three triggers for the 2026/2027 budget year. Traders that stock heavily or import in bulk are the most exposed, and they should monitor the thresholds during the year rather than only at year end.
Proof
Tout contribuable dont les achats locaux et/ou les importations atteignent, au cours d'un exercice fiscal, une valeur supérieure à cinquante millions de francs burundais (50 000 000 BIF) est automatiquement assujetti à la TVA et entre obligatoirement dans la catégorie des moyens contribuables ou des grands contribuables, à l'exception de la valeur des investissements ou des effets personnels.Any taxpayer whose local purchases and/or imports reach, in a fiscal year, a value above fifty million Burundian francs (BIF 50,000,000) is automatically subject to VAT and must enter the category of medium or large taxpayers, excluding the value of investments or personal effects.
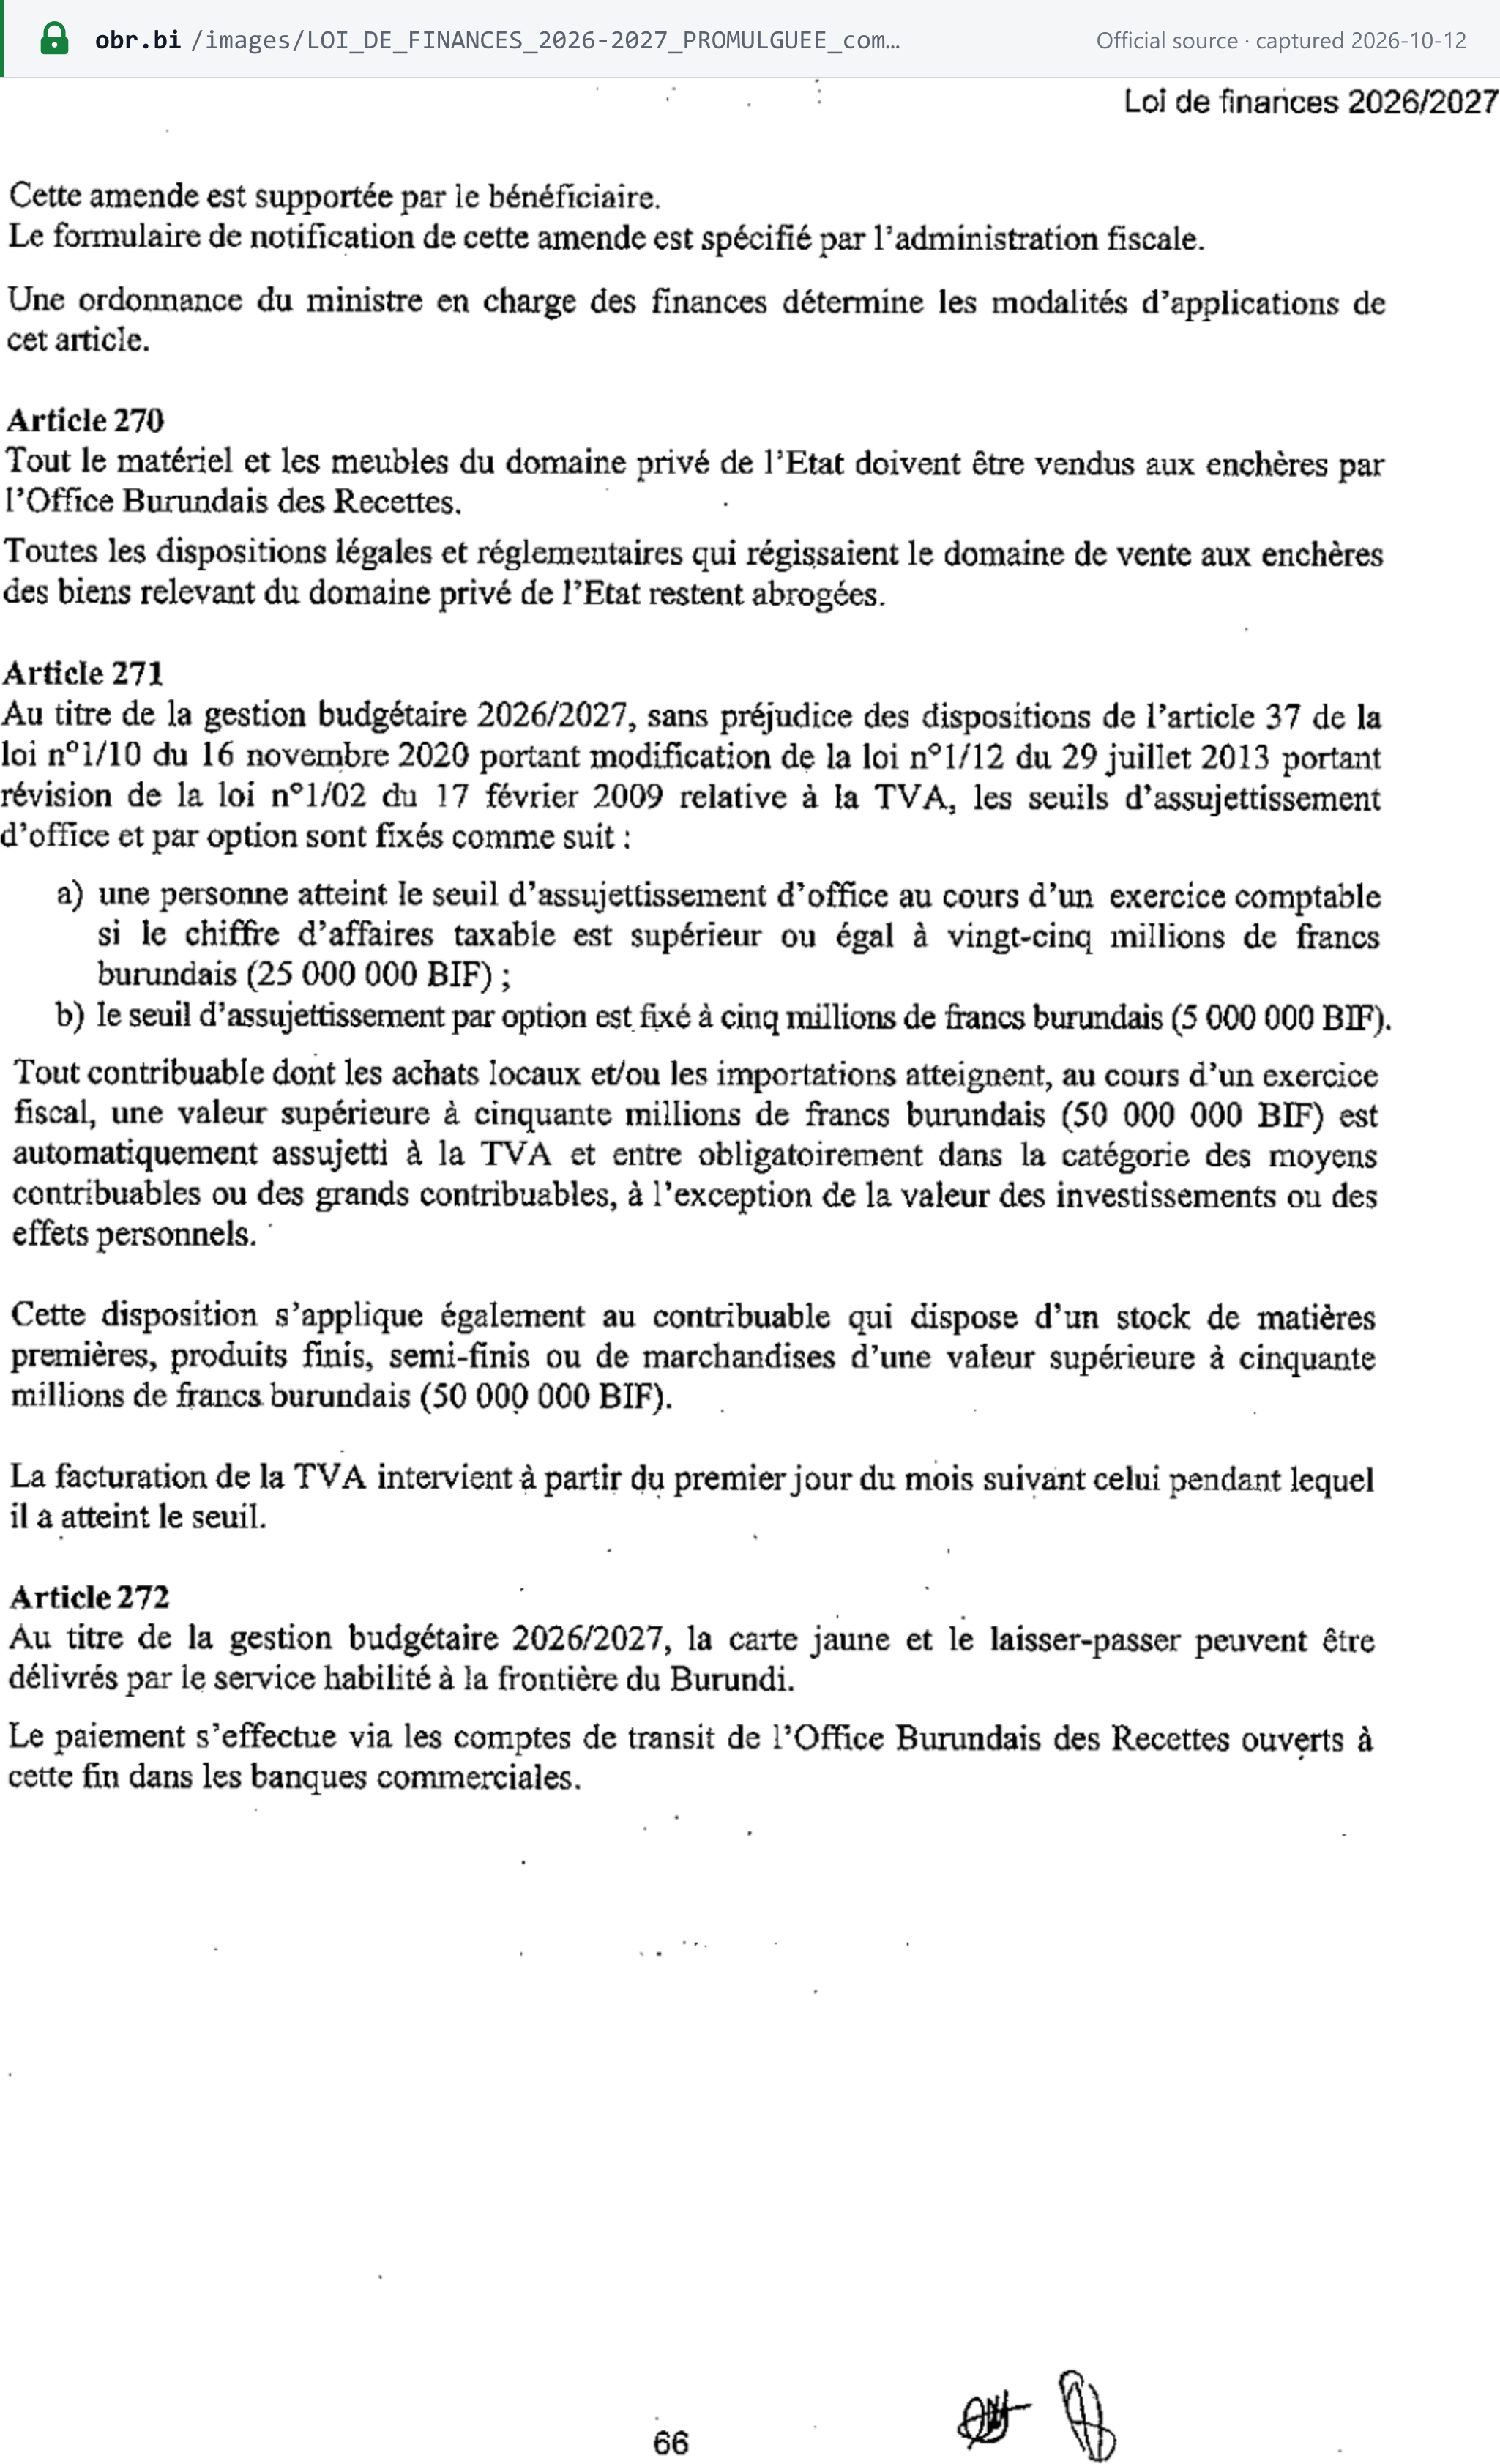 Source snapshot of the official page. Open full size ↗