Cambodia clarifies that dental services are VAT-exempt: Instruction No. 014 lists the services covered
- Jurisdiction
- Cambodia
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 17 August 2026
- Effective
- 17 August 2026
- Authority
- Ministry of Economy and Finance, Cambodia
- Systems
- Invoicing, POS, Tax engine
- Verified
- Fetched from official source · medium confidence
Dental clinics and other self-declaration regime taxpayers supplying dental services in Cambodia.
Dental clinics should not charge VAT on the listed services; no action for other taxpayers.
InvoicingPOSTax engine
Cambodia's Ministry of Economy and Finance issued Instruction No. 014 MEF.S.N.N.GDT dated 17 August 2026 (listed on the GDT Instructions page) clarifying the non-taxable (VAT-exempt) supply of dental services under Article 63 of the Law on Taxation (Royal Kram NS/RKM/0523/004 of 16 May 2023). It lists as non-taxable dental services including examinations and diagnosis (full-mouth records, orthodontic records, impressions, X-rays), tooth extraction and oral surgery (including implants and grafting), and gum treatment. Addressed to all self-declaration regime taxpayers; effective from the date of signature.
What changed in detail
Instruction No. 014 MEF.S.N.N.GDT of the Ministry of Economy and Finance, dated 17 August 2026 and listed on the General Department of Taxation’s Instructions page, clarifies the non-taxable (VAT-exempt) supply of dental services under Article 63 of the Law on Taxation (Royal Kram NS/RKM/0523/004 of 16 May 2023). It is addressed to all self-declaration regime taxpayers and is effective from the date of signature.
It lists as non-taxable:
- examinations and diagnosis, including full-mouth records, orthodontic records, impressions and X-rays;
- tooth extraction and oral surgery, including implants and grafting;
- gum treatment, with or without surgery; and
- the other dental services itemised in the instruction.
What it means
The instruction clarifies how an existing exemption applies rather than creating a new one. Dental clinics should not charge VAT on the listed services; it requires no action from other taxpayers.
Proof
ការផ្គត់ផ្គង់មិនជាប់អាករចំពោះសេវាខាងទន្តសាស្ត្រNon-taxable supply of dental services
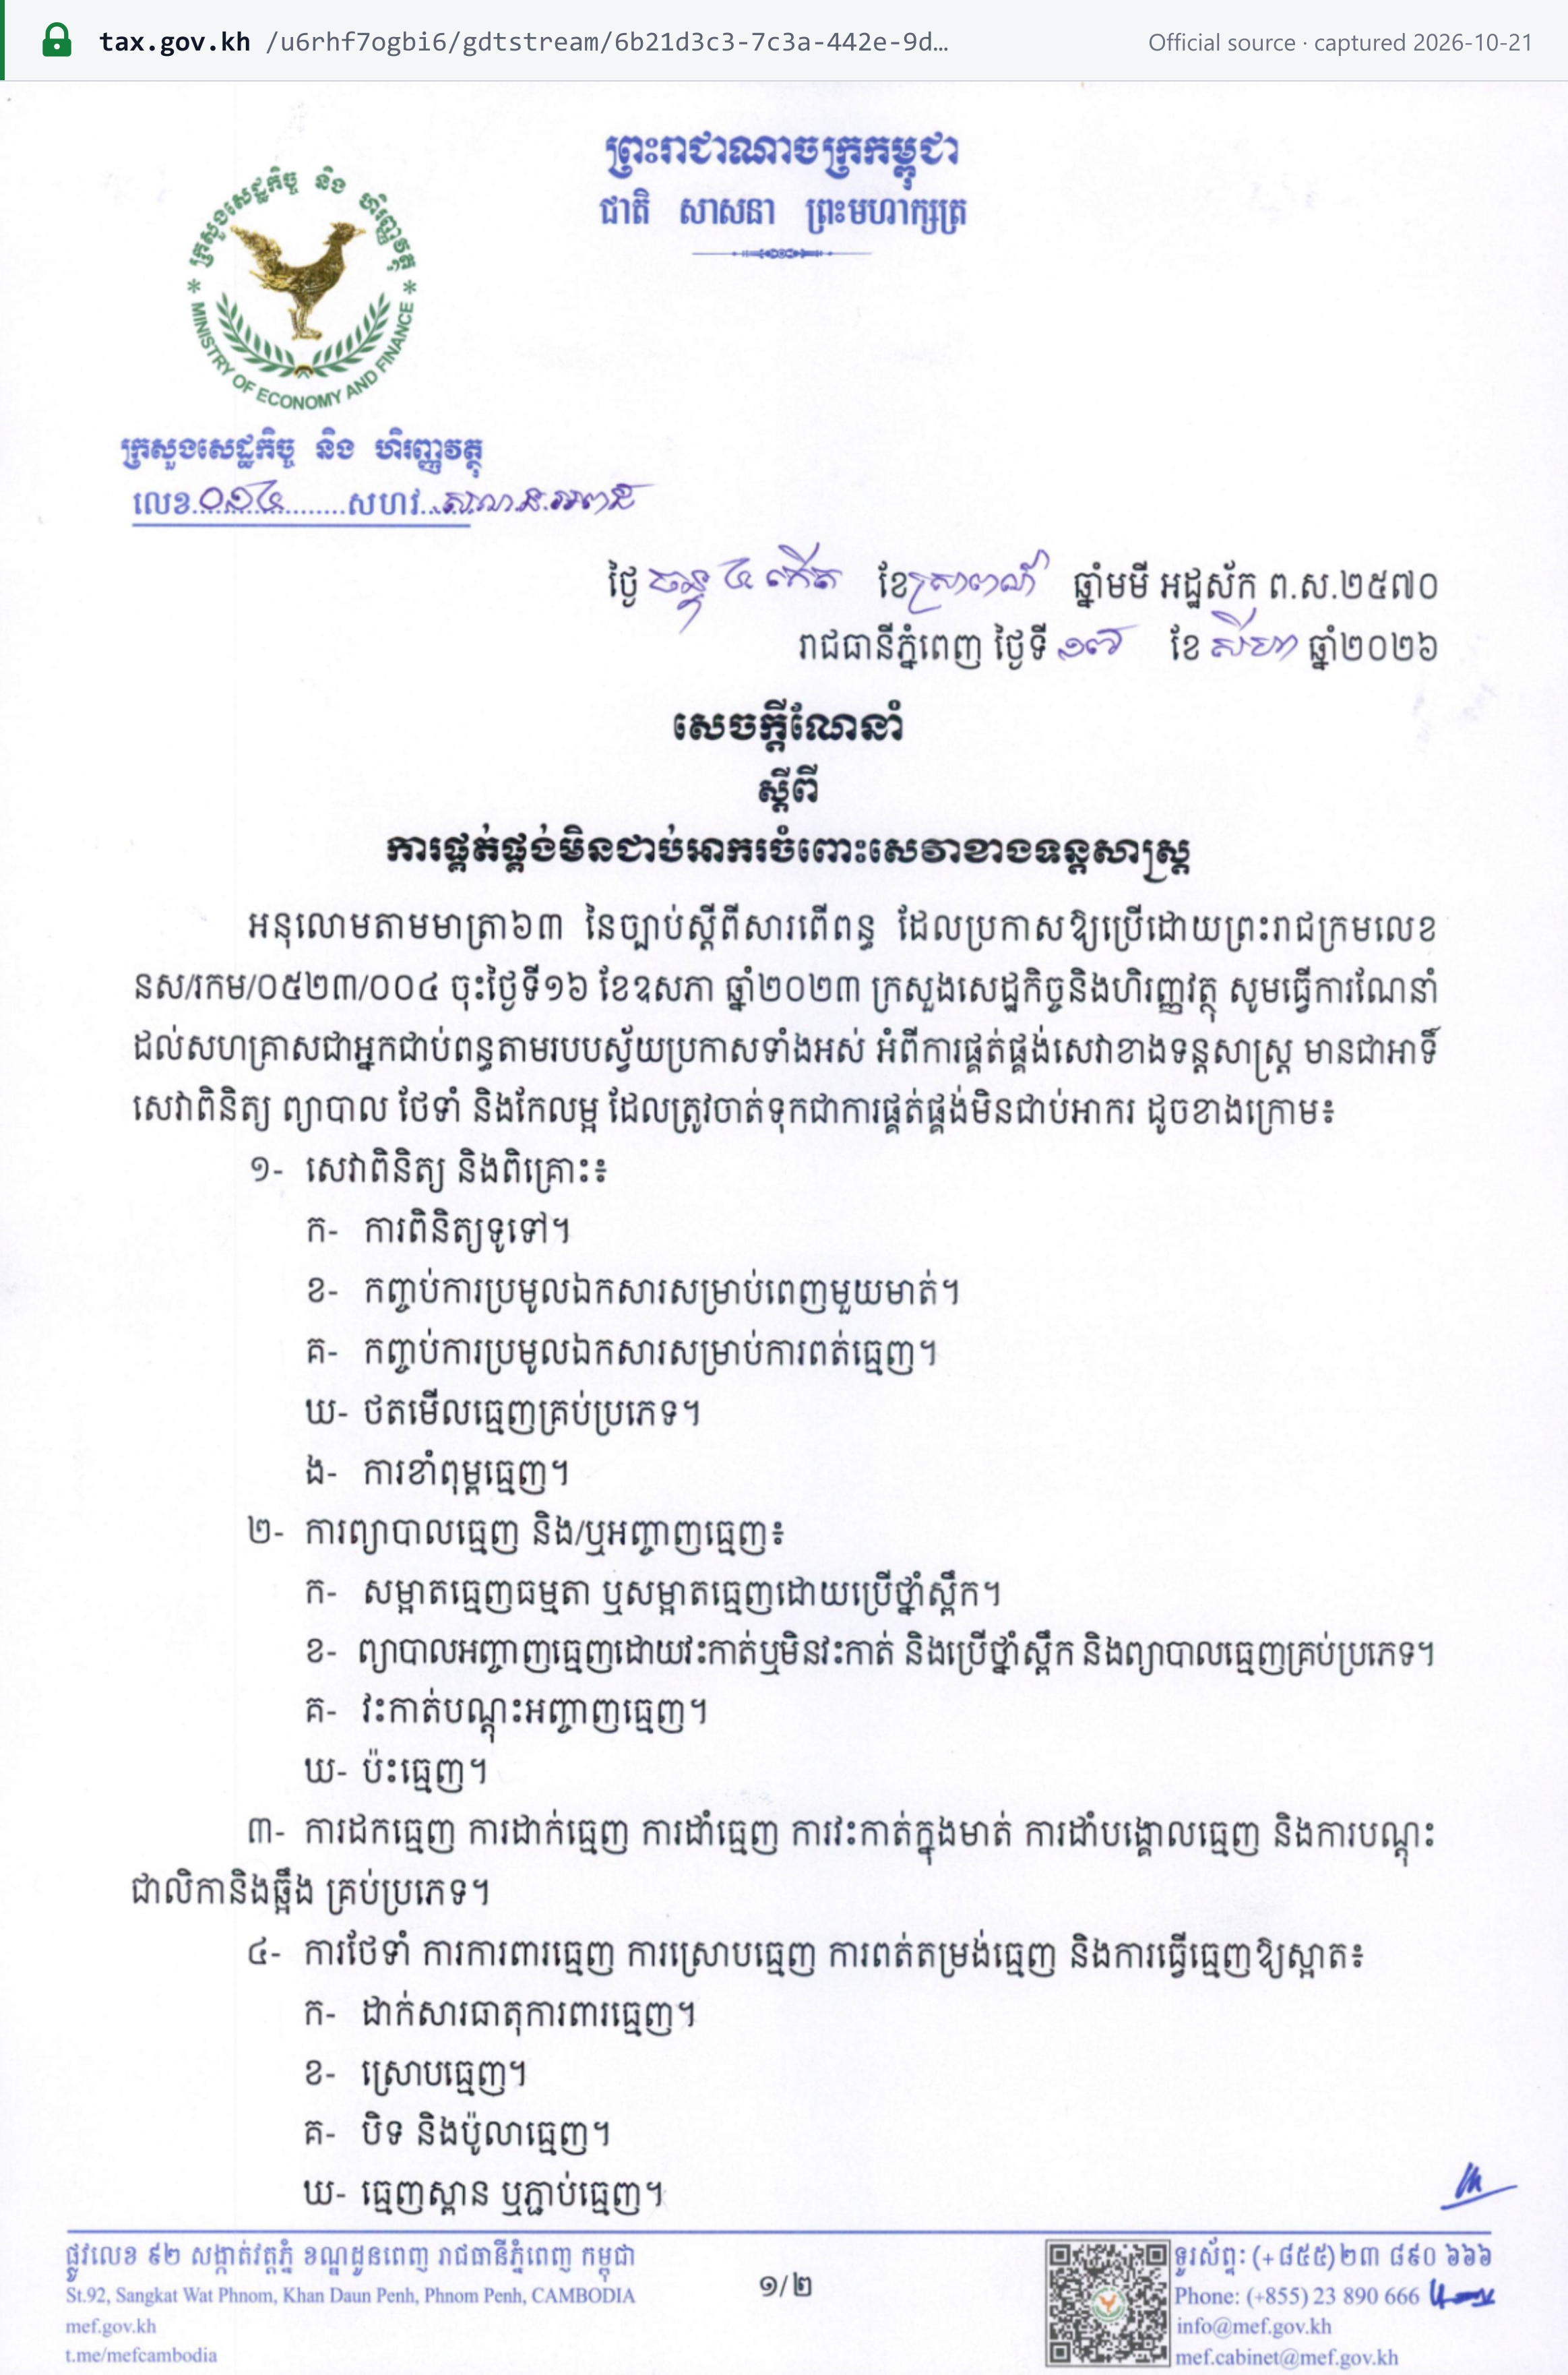 Source snapshot of the official page. Open full size ↗