Chile lets sellers opt for a VAT exemption on the first sale of new dwellings from 1 December 2026 (Law 21.850)
This page records one dated change. For the rules in Chile as they stand today, see the Chile guide →
- Jurisdiction
- Chile
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 17 October 2026
- Effective
- 1 December 2026
- Authority
- Diario Oficial de la República de Chile
- Systems
- ERP, Invoicing, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Chilean property developers and other sellers of new dwellings that already hold final municipal reception, and buyers of those dwellings.
Identify unsold new dwellings with final municipal reception before 17 Oct 2026 and plan exempt-sale invoicing, credit and refund treatment from 1 Dec 2026.
ERPInvoicingTax engineReporting
Chile's Law No. 21.850 (promulgated 9 October 2026, published in the Diario Oficial on 17 October 2026) lets sellers opt, under its fourth transitional article, for an exemption from VAT (Title II of Decree Law 825) on the first sale of a new dwelling. The option runs for one year from the first business day of the second month after publication (1 December 2026). Requirements: the dwelling (any value or size, with parking and storage sold in the same deed) already has final municipal reception dated before publication; it is the first transfer, not between related companies; and the deed (or a prior promise-of-sale instrument) falls within the period. The seller keeps input VAT credit; sales made between the date of the presidential message and the start date that already paid VAT may claim a refund under art. 126 of the Tax Code.
What changed in detail
Law No. 21.850 was promulgated on 9 October 2026 and published in the Diario Oficial on 17 October 2026. Its fourth transitional article lets sellers opt for an exemption from VAT (Title II of Decree Law 825) on the first sale of a new dwelling.
The option runs for one year from the first business day of the second month after publication, which is 1 December 2026. The requirements are:
- the dwelling, of any value or size and with parking and storage sold in the same deed, already has final municipal reception dated before publication;
- it is the first transfer and not between related companies; and
- the deed, or a prior promise-of-sale instrument, falls within the option period.
The seller keeps input VAT credit. Sales made between the date of the presidential message and the start date that already paid VAT may claim a refund under article 126 of the Tax Code.
What it means
The option is the seller’s choice, so developers will compare the exempt-sale treatment against charging VAT for each unsold dwelling. Stock with final municipal reception dated before 17 October 2026 is the group that can use it; invoicing, credit and refund treatment needs to be set up before 1 December 2026.
Proof
Durante el plazo de un año contado desde el primer día hábil del mes subsiguiente al de la publicación de la presente ley, los contribuyentes podrán optar a una exención del impuesto establecido en el Título II del decreto ley N° 825, de 1974, Ley sobre Impuesto a las Ventas y Servicios, por las ventas de bienes corporales inmuebles que, de conformidad con las normas generales de dicho cuerpo legal, se encontraren afectas a dicho impuestoFor one year from the first business day of the second month after publication of this law, taxpayers may opt for an exemption from the tax established in Title II of Decree Law No. 825 of 1974, the Law on Sales and Services Tax, for sales of tangible immovable property that, under the general rules of that law, would be subject to that tax
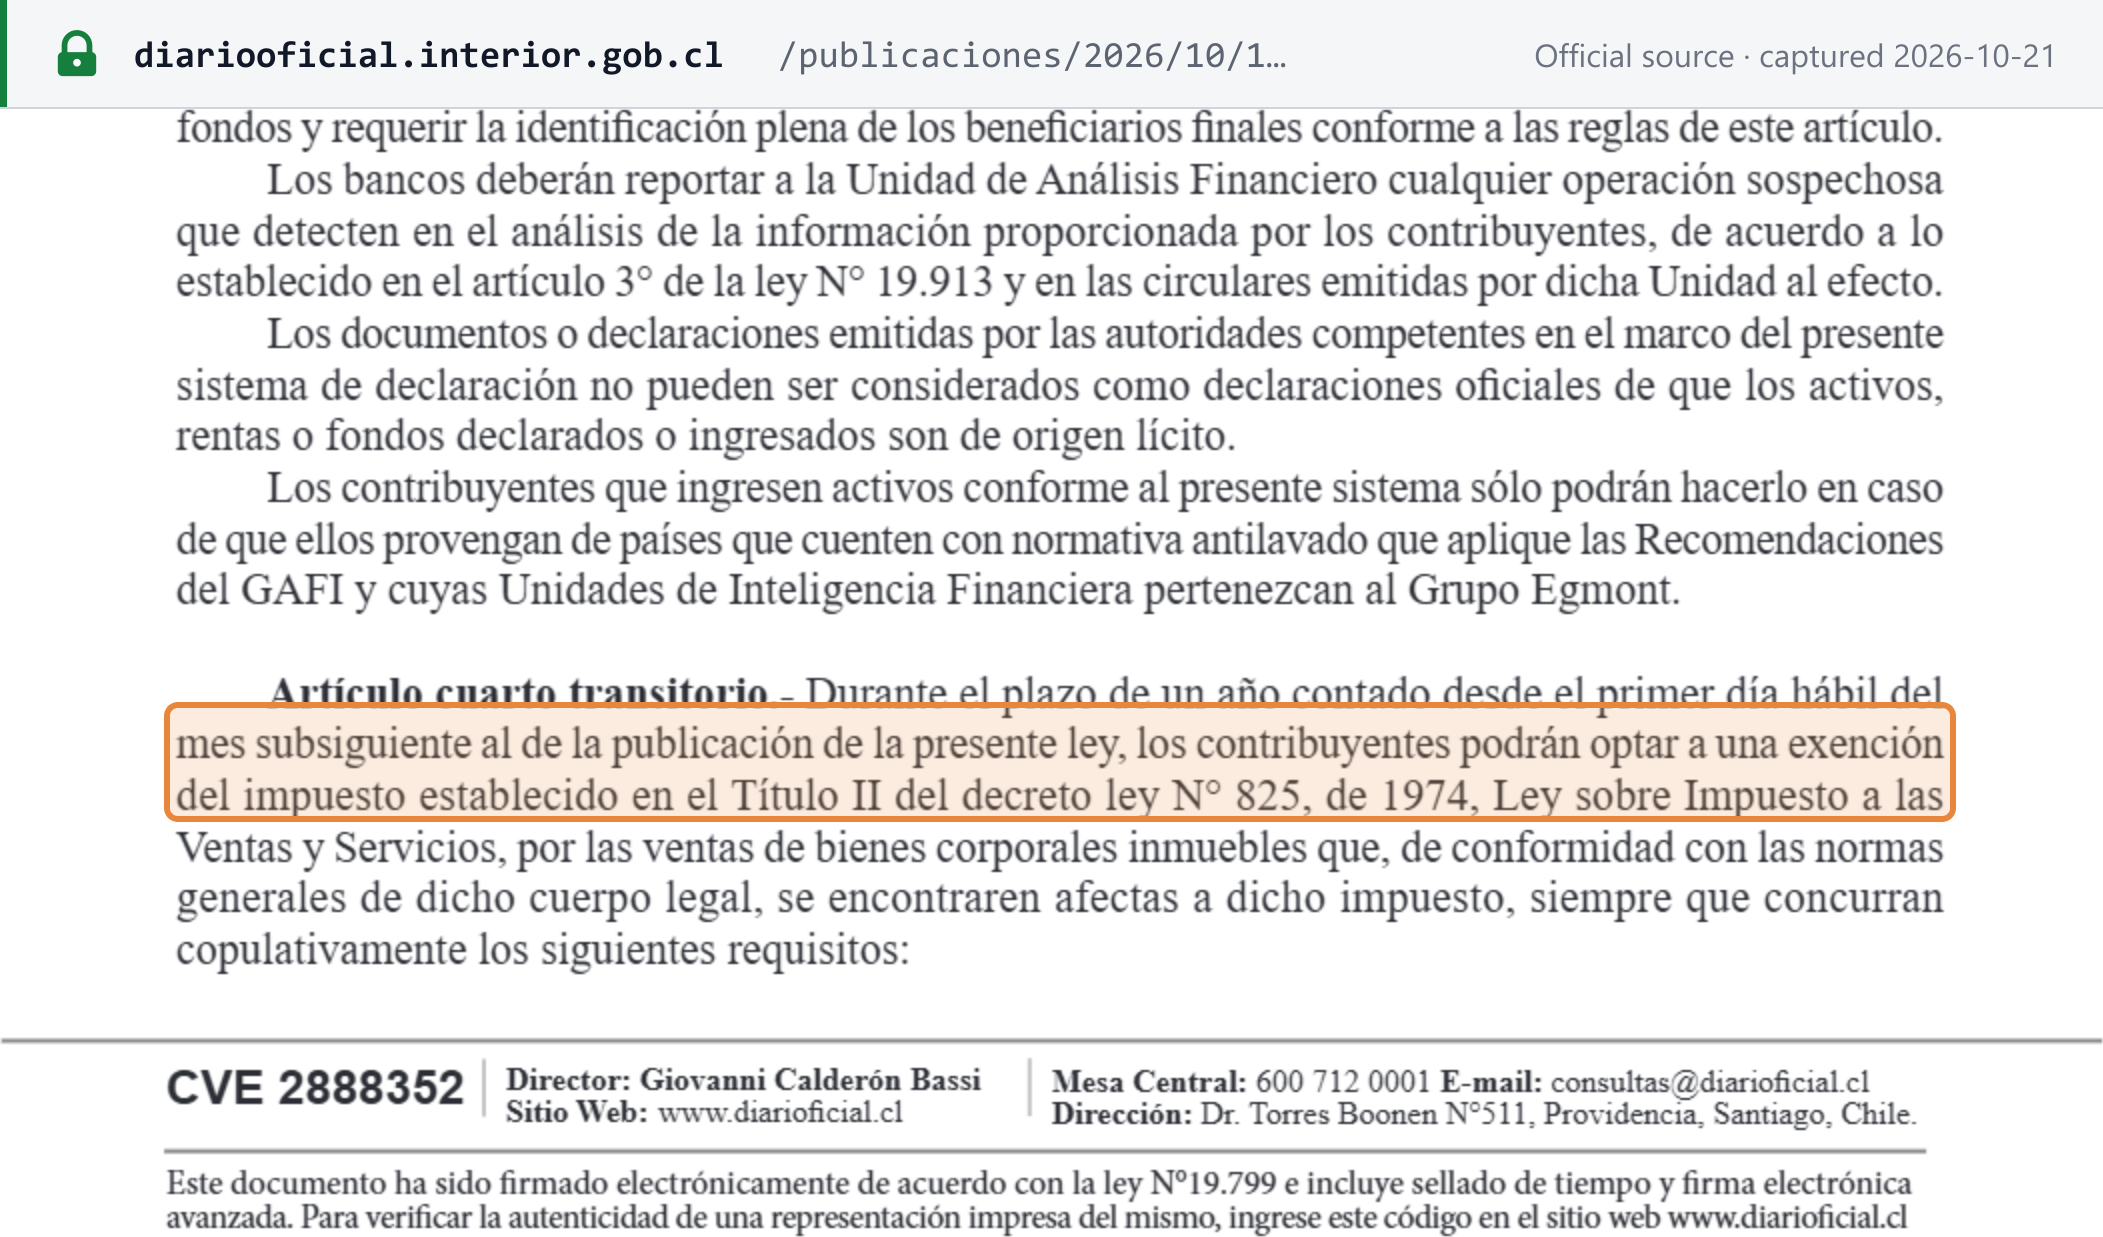 Source snapshot of the official page. Open full size ↗