Chile sets the VAT refund procedure for new-home sales under Law 21.850 from 1 December 2026 (SII Resolution 146 of 2026)
This page records one dated change. For the rules in Chile as they stand today, see the Chile guide →
- Jurisdiction
- Chile
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 23 October 2026
- Effective
- 1 December 2026
- Authority
- Servicio de Impuestos Internos (SII), Chile
- Systems
- ERP, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Chilean property developers and other sellers of new dwellings sold by public deed between the submission of the bill that became Law 21.850 and 1 December 2026, and the buyers of those dwellings.
Property developers and sellers: gather deeds, final-works certificates and proof of VAT repayment to buyers, and prepare F3298 claims from 1 December 2026.
ERPInvoicingReporting
Chile's SII Resolución Exenta N° 146 of 23 October 2026 sets the special procedure for sellers to claim the VAT refund provided by the fourth transitional article of Law No. 21.850 for sales of new homes under public deed between the date the bill was submitted and the first business day of the second month after publication of the law. Sellers file Form F3298 per sale, within 3 years from 1 December 2026, after buyers file a sworn declaration (F3299) confirming the VAT was returned to them; the SII aims to decide within 5 business days. The resolution takes effect on 1 December 2026.
What changed in detail
Chile’s Servicio de Impuestos Internos (SII) issued Resolución Exenta SII N° 146 on 23 October 2026. It sets the special procedure for sellers to claim the VAT refund provided by the fourth transitional article of Law No. 21.850, the law that also lets sellers opt for a VAT exemption on first sales of new dwellings for one year from 1 December 2026.
The refund covers sales of new homes made by public deed between the date the presidential message introducing the bill was submitted and the first business day of the second month after the law’s publication, which is 1 December 2026. The procedure works as follows:
- the buyer first files a sworn declaration online (Form F3299) confirming that the seller returned the VAT to them;
- the seller then files Form F3298, one claim per sale, showing the property’s roll number and commune, the invoice and the amount claimed;
- claims must be filed within 3 years from 1 December 2026; and
- the SII aims to decide within 5 business days of filing and, where it approves, refunds in cash the amount the seller returned to the buyer.
Sellers do not need to reissue invoices or amend their monthly Form 29 returns. They must keep the deed, the final-works certificate and proof of the amount returned to the buyer. The resolution takes effect on 1 December 2026.
What it means
The refund is the backward-looking half of Law 21.850: it puts sales that already bore VAT on the same footing as the exempt sales the law allows from 1 December 2026. The order matters, because the seller cannot claim until the buyer has filed the F3299 declaration, so developers should agree the VAT repayment and the buyer’s filing with each purchaser before preparing claims.
Proof
13º La presente resolución entrará en vigencia a contar del día 1° de diciembre de 2026.13. This resolution shall enter into force from 1 December 2026.
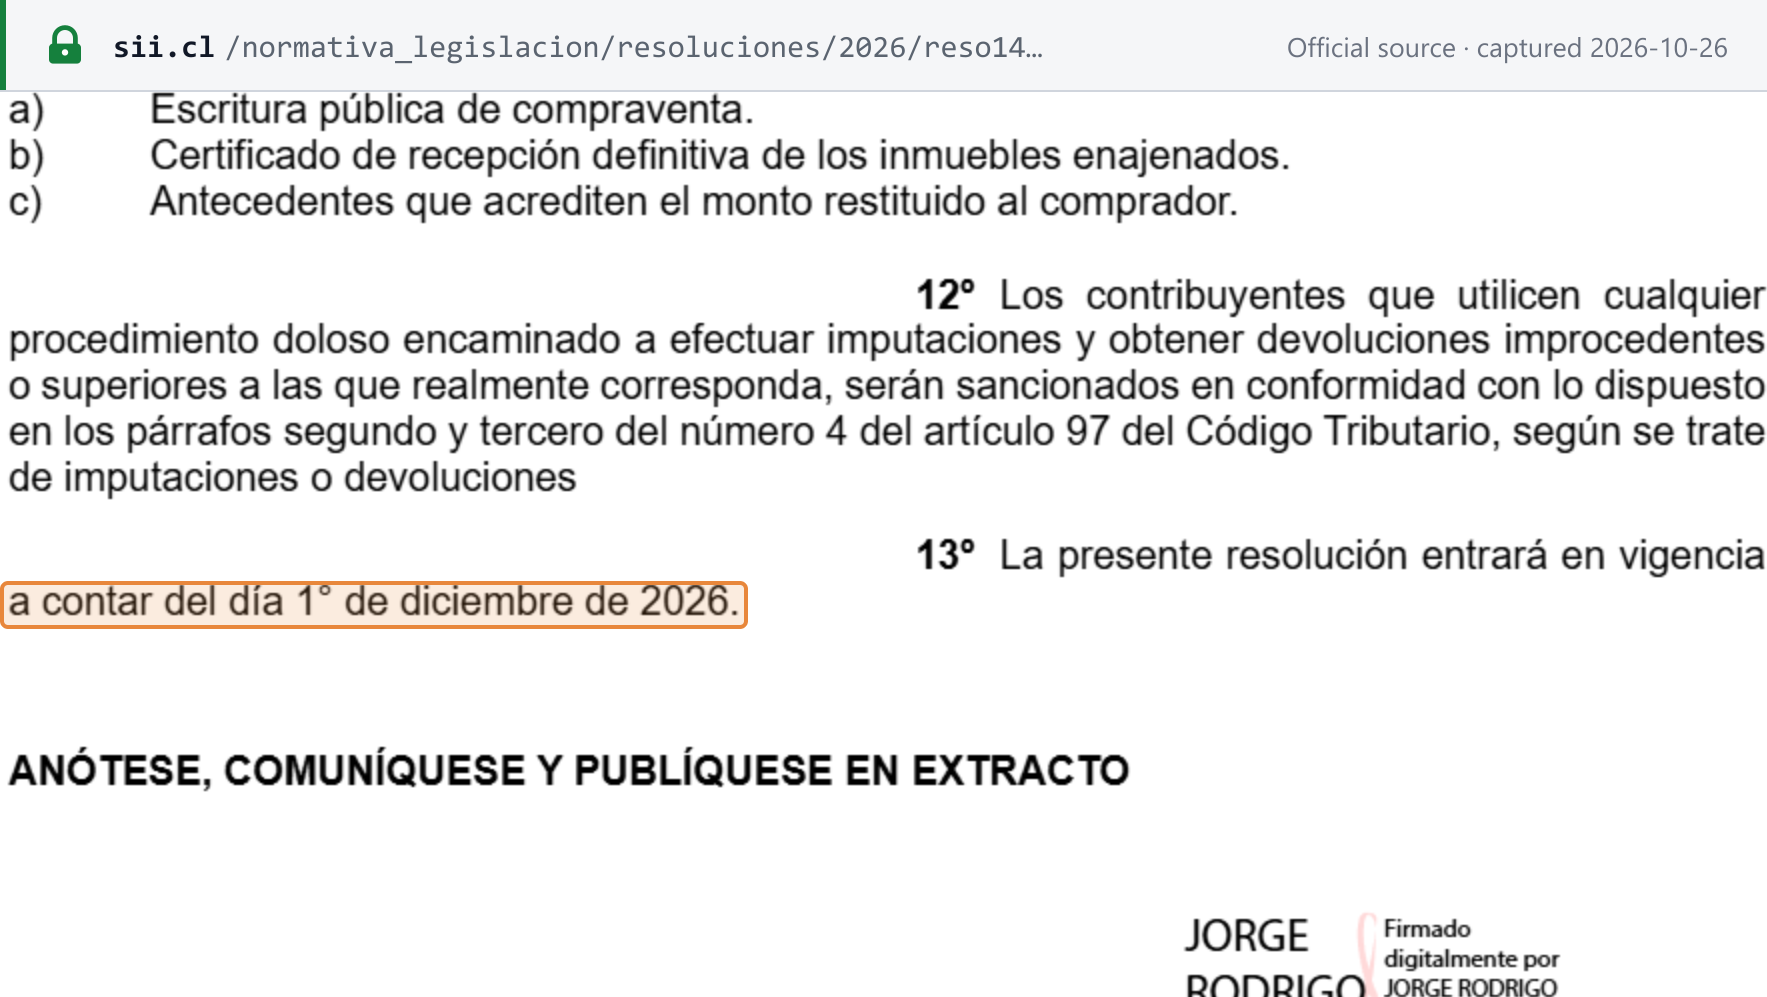 Source snapshot of the official page. Open full size ↗