China clarifies which items are non-deductible non-taxable transactions for input VAT (Announcement No. 25 of 2026)
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 27 August 2026
- Effective
- 1 September 2026
- Authority
- Ministry of Finance and State Taxation Administration of the People's Republic of China
- Systems
- ERP, Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
VAT taxpayers in China that receive insurance compensation, donations or subsidies, or that hold equity, dividends or commodity-futures positions.
Review input-VAT deduction treatment of insurance claims, donations, free services, subsidies and equity/futures income; apply to unprocessed matters from 1 January 2026.
ERPTax engineReporting
MOF and STA Announcement No. 25 of 2026 (dated 27 August 2026, effective 1 September 2026) clarifies the VAT Law Implementing Regulations: insurance compensation received, donations received, contract-breach payments where no taxable transaction occurs, free services, assignment of receivables arising from own taxable transactions and certain non-volume-linked subsidies are not 'non-taxable transactions' for input-tax non-deduction (input tax deductible); equity transfers for consideration (other than securities), dividends and commodity-futures trading (excluding physical delivery) and sales outside the Article 4 domestic-taxable scope are non-deductible. Unprocessed matters from 1 January to 31 August 2026 follow the announcement.
What changed in detail
Ministry of Finance and State Taxation Administration Announcement No. 25 of 2026, dated 27 August 2026, takes effect on 1 September 2026. It clarifies the VAT Law Implementing Regulations on non-taxable transactions for which input tax cannot be deducted.
The following are not “non-taxable transactions” for input-tax non-deduction, so the related input tax is deductible: insurance compensation received, donations received, contract-breach payments where no taxable transaction occurs, free services, assignment of receivables arising from the taxpayer’s own taxable transactions, and certain non-volume-linked subsidies.
The following are non-deductible: equity transfers for consideration (other than securities), dividends, commodity-futures trading (excluding physical delivery), and sales outside the Article 4 domestic-taxable scope.
Unprocessed matters from 1 January to 31 August 2026 follow the announcement.
The same announcement covers other implementing points beyond these two lists, including agricultural-product invoices, technical schools, first-gate ticket revenue, cost basis in restructurings, waiver of VAT preferences, telecom bundles and invoice discounts, and repeals article 1 of Cai Shui [2007] No. 127.
What it means
The Announcement sorts items into two lists, and the line is easy to misread. Receipts that look like income but are not payment for a supply, such as compensation or donations, do not by themselves block input VAT. By contrast, equity transfers, dividends and futures trading do. Because unprocessed matters from 1 January 2026 follow the Announcement, taxpayers with open periods should review how they treated these items.
Proof
一、纳税人有下列情形的,不属于增值税法实施条例第二十二条所称不得抵扣非应税交易,对应的进项税额可以按规定从销项税额中抵扣:1. Taxpayers in the following situations are not subject to the non-deductible non-taxable transactions referred to in Article 22 of the VAT Law Implementing Regulations; the corresponding input tax may be deducted from output tax in accordance with the rules:
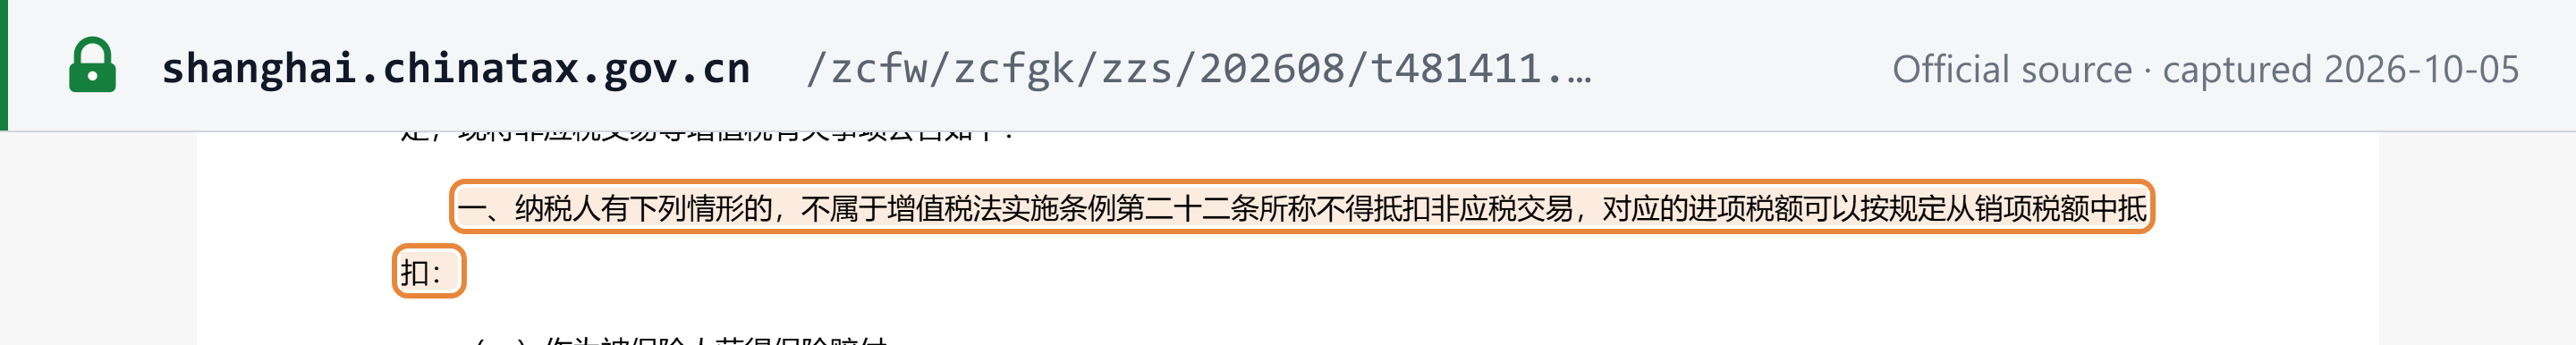 Source snapshot of the official page. Open full size ↗