China creates VAT withholding for domestic payers of resident individuals
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 3 September 2026
- Effective
- 1 November 2026
- Authority
- Ministry of Finance and State Taxation Administration of the People's Republic of China
- Systems
- Tax engine, ERP, Reporting
- Verified
- Fetched from official source · high confidence
Domestic units paying Chinese resident individuals for R&D, software, design, consulting, broadcast/film/TV production, cultural or education services — excluding payments made via internet platforms already subject to platform withholding.
Domestic payers of Chinese resident individuals for R&D, software, design, consulting, broadcast/film/TV production, cultural or education services must stand up VAT (and surcharge) withholding and monthly filing (within 15 days of the following month) before 1 November 2026.
Tax engineERPReporting
China's Ministry of Finance and State Taxation Administration published Announcement No. 28 of 2026 (dated 3 September 2026), promulgating the Measures for Domestic Entities Withholding VAT on Natural Persons. Under Article 15 of the Measures, from 1 November 2026 a domestic unit paying a resident individual for research-and-development, software, design, consulting, radio/film/TV programme production, cultural, or education services becomes the VAT withholding agent and must withhold VAT (and applicable surcharges) at the time of payment, calculated as sales amount times the prescribed levy rate; before 1 November 2026 (1 Jan-31 Oct 2026) such individuals continue to self-declare under Article 44 of the VAT Law Implementing Regulations. Individuals transacting via internet platforms already covered by platform withholding/declaration rules are excluded (Article 14).
What changed in detail
The Ministry of Finance and State Taxation Administration issued Announcement No. 28 of 2026 (dated 3 September 2026), promulgating the Measures for Domestic Entities Withholding VAT on Natural Persons. Under Article 15 of the Measures, from 1 November 2026 a domestic unit paying a resident individual for research-and-development, software, design, consulting, radio/film/TV programme production, cultural, or education services becomes the VAT withholding agent, and must withhold VAT (plus applicable surcharges) at the time of payment — calculated as the sales amount times the prescribed levy rate.
Before 1 November 2026 (1 January–31 October 2026), individuals providing these services continue to self-declare under Article 44 of the VAT Law Implementing Regulations. Individuals transacting through internet platforms already covered by platform withholding and declaration rules are excluded from the new withholding duty (Article 14).
What it means
This shifts the collection point from the individual to the payer for a specific list of services — R&D, software, design, consulting, media production, culture and education — that previously relied on self-declaration. Domestic units paying freelancers or independent contractors in these categories need withholding and monthly filing (within 15 days of the following month) operational before 1 November 2026, and should confirm early whether a given payment channel already counts as an internet platform under the existing platform rules, since that exclusion determines who withholds.
Proof
根据《中华人民共和国增值税法》、《中华人民共和国税收征收管理法》、《中华人民共和国增值税法实施条例》及有关规定,财政部、税务总局制定了《境内单位代扣代缴自然人增值税管理办法》,现予公布。Pursuant to the VAT Law of the People's Republic of China, the Tax Collection and Administration Law, the Implementing Regulations of the VAT Law and related provisions, the Ministry of Finance and the State Taxation Administration have formulated the Measures for Domestic Entities Withholding VAT on Natural Persons, which are hereby promulgated.
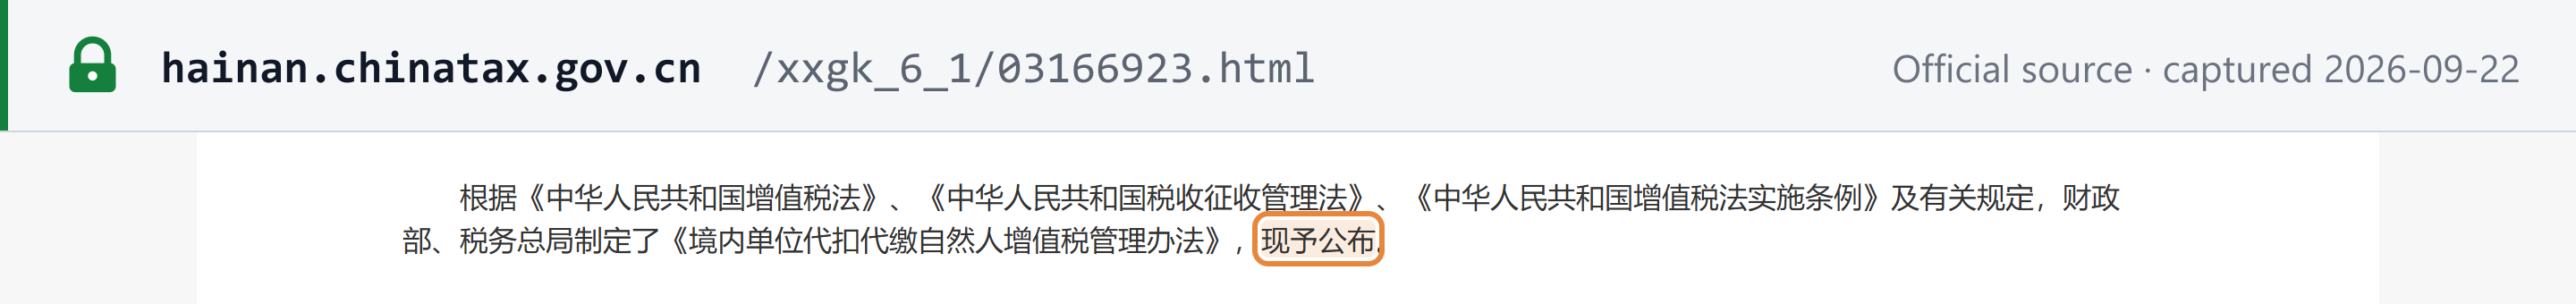 Source snapshot of the official page. Open full size ↗