Republic of the Congo collects 18% VAT on non-residents’ digital services from 1 July 2026
- Jurisdiction
- Congo (Brazzaville)
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- Action required
- Announced
- 1 January 2026
- Effective
- 1 July 2026
- Authority
- Agence de Régulation des Postes et des Communications Électroniques (ARPCE), République du Congo
- Systems
- Tax engine, Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Businesses with no establishment in the Republic of the Congo that supply digital services, or facilitate transactions, for customers located there: advertising, streaming, online games, software and apps, e-books, cloud services and similar. There is no turnover threshold.
Non-resident digital service providers with customers in the Republic of the Congo: register on the ARPCE portal, charge 18% VAT and file quarterly returns by the 20th.
Tax engineInvoicingReporting
In the Republic of the Congo, VAT applies to digital services supplied by non-resident providers to customers located in the Congo, under article 11 of Law No. 39-2023 of 29 December 2023 (Finance Law for 2024), as applied by the DGID’s Instruction N° 0339/MEF/DGID/DRC of 18 March 2024 and ARPCE Explanatory Note No. 001/ARPCE-DG/26 of 1 January 2026. Collection through ARPCE’s simplified portal (tvadigital.arpce.cg) started on 1 July 2026. The rate is a single 18%, with no additional surtax, and there is no registration threshold. Returns are quarterly, due by the 20th of the month after the quarter; the first, for July to September 2026, was due with payment by 20 October 2026. No tax representative is required. This supersedes cd-cross-border-digital-services-2026, which attributed the regime to the Democratic Republic of the Congo at 16% via a DGR portal.
What changed in detail
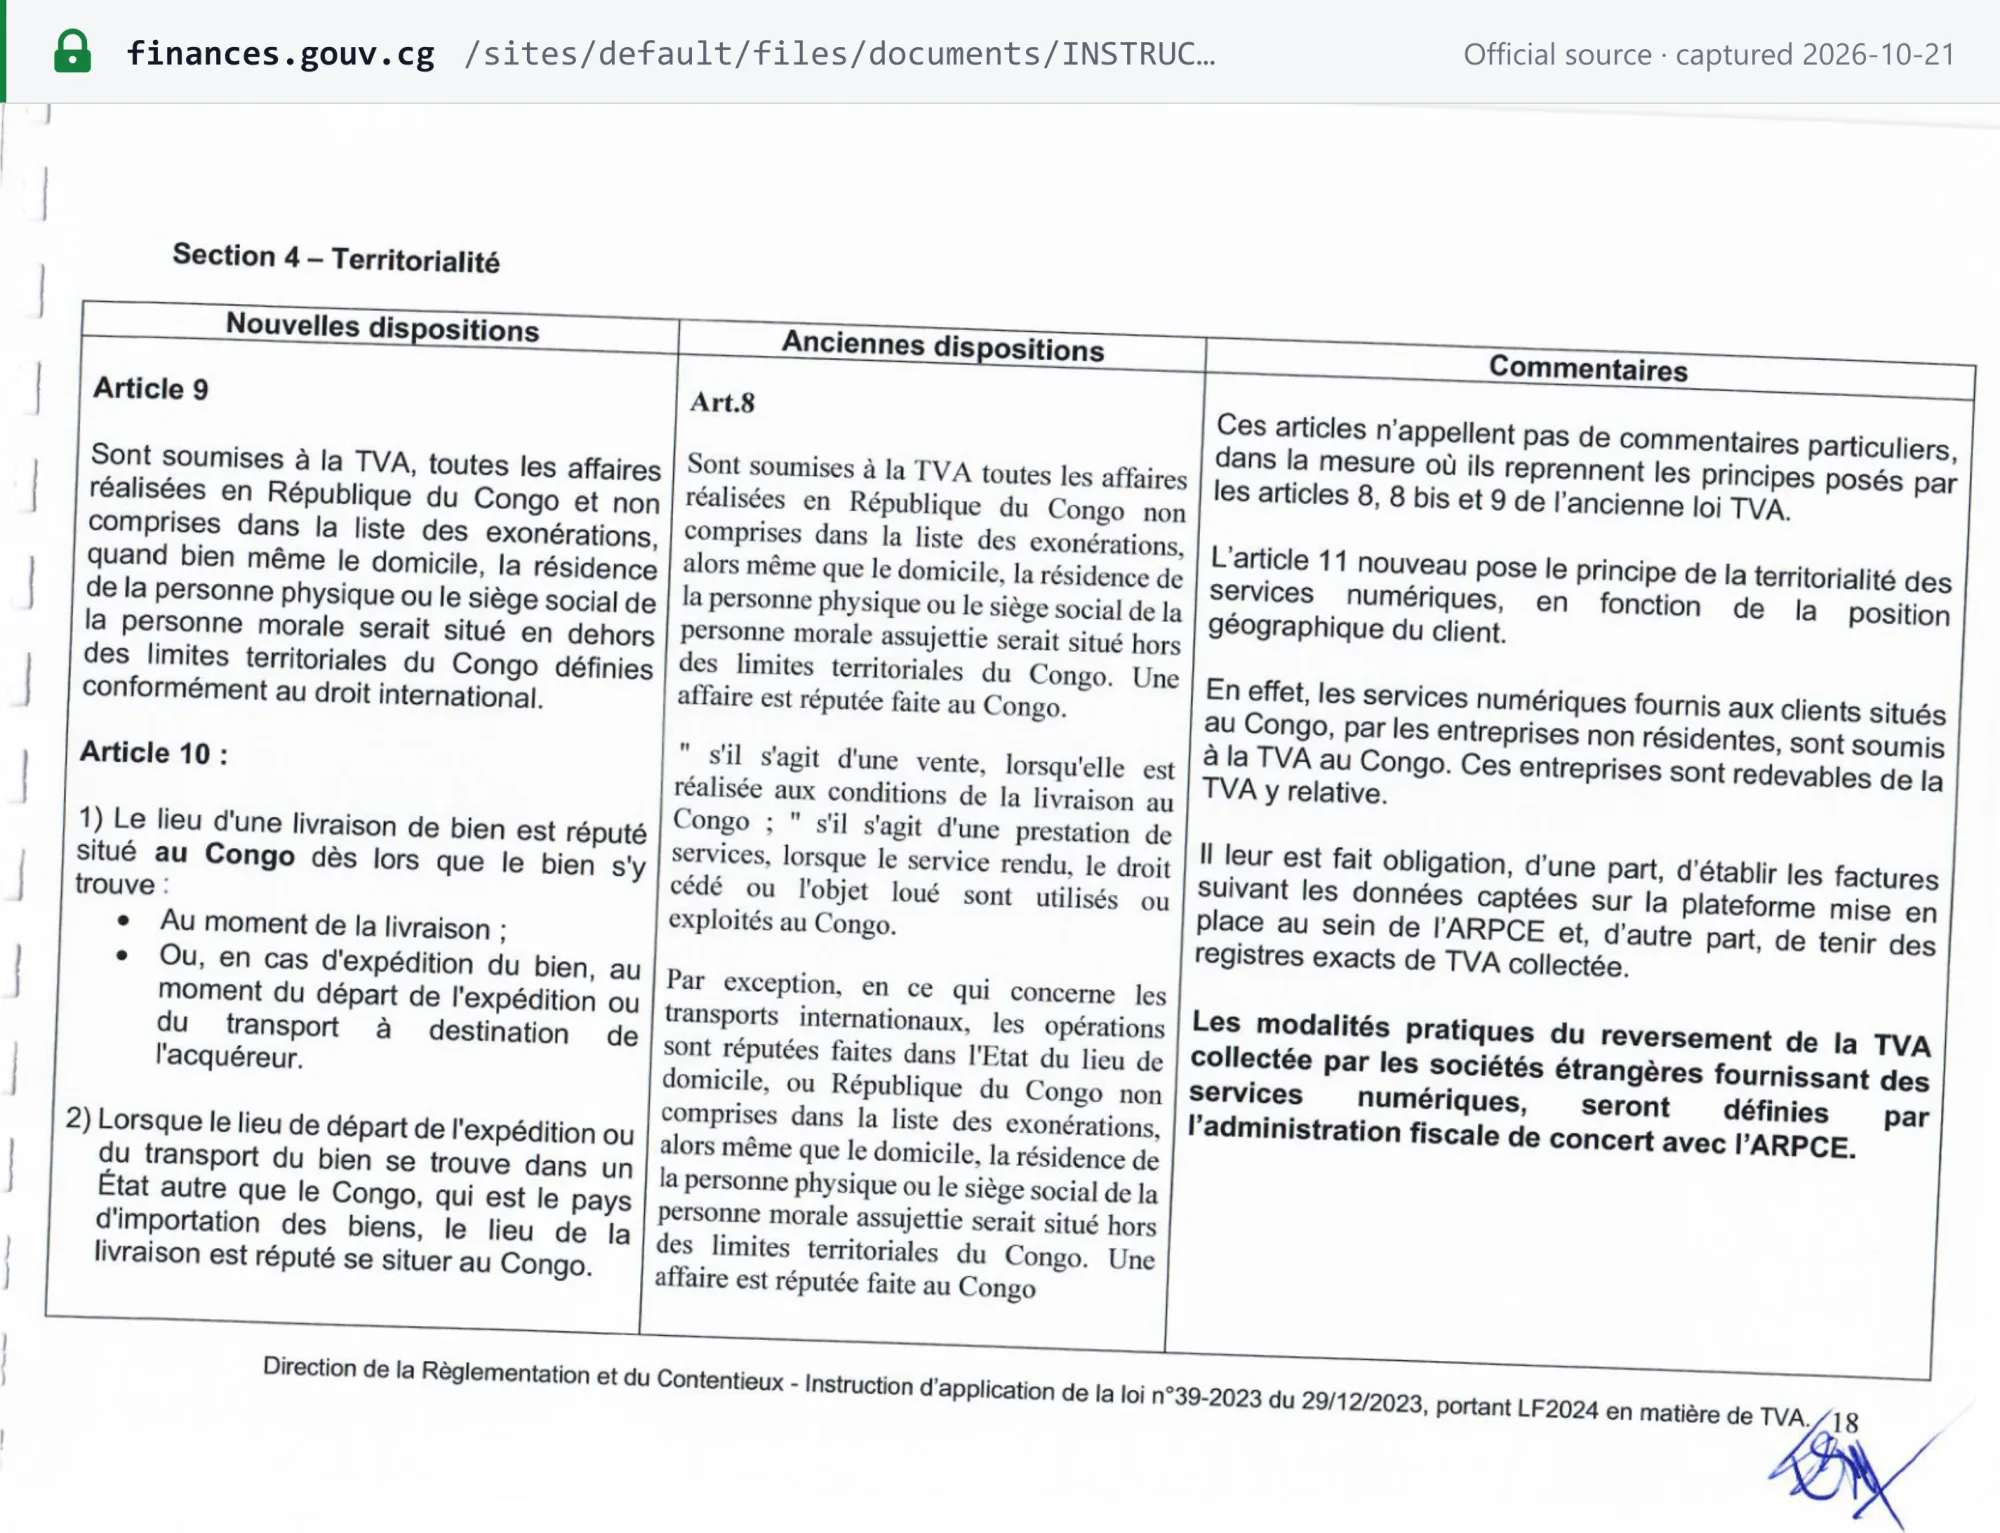
Article 11 of Law No. 39-2023 of 29 December 2023 (Finance Law for 2024) taxes digital services by where the customer is. The tax directorate’s application instruction (Instruction N° 0339 of 18 March 2024) explains that “les services numériques fournis aux clients situés au Congo, par les entreprises non résidentes, sont soumis à la TVA au Congo”, and leaves collection arrangements to the tax administration and the telecoms regulator, ARPCE.
ARPCE’s Explanatory Note No. 001/ARPCE-DG/26 of 1 January 2026 sets those arrangements, and its portal FAQ (last updated 29 September 2026) summarises them:
- Start of collection: 1 July 2026.
- Rate: a single 18%, with no additional surtax under this regime.
- Threshold: none — the obligation applies whatever the provider’s turnover.
- Returns: quarterly, including nil returns, by the 20th of the month after the quarter. The first, for July to September 2026, was due with payment by 20 October 2026.
- Payment: bank transfer in EUR or USD.
- Representative: not required.
What it means
If you sell digital services to customers in the Republic of the Congo (Brazzaville) and have no establishment there, you should already be registered on ARPCE’s portal and charging 18%. The first return has fallen due. This is the rule we reported in June 2026 as a DR Congo measure at 16%: the instruction is Brazzaville’s, and the DR Congo has no equivalent.
Proof
VAT Rate: 18% | Filing: Quarterly | Payment: Bank transfer in EUR or USD | No minimum threshold | No tax representative required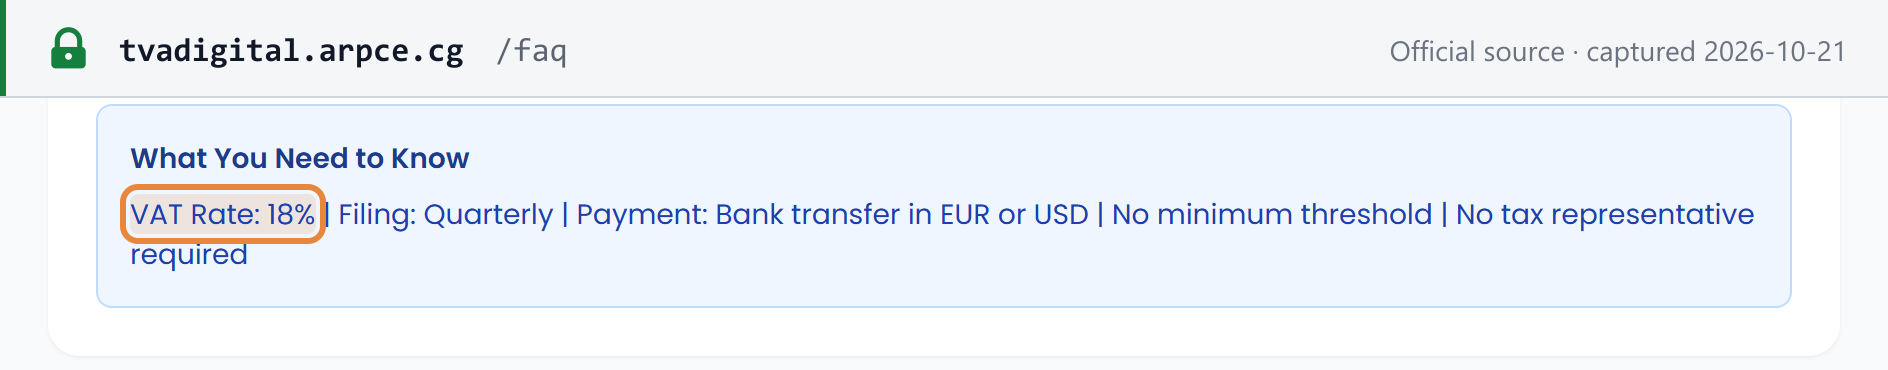 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · tvadigital.arpce.cg
En effet, les services numériques fournis aux clients situés au Congo, par les entreprises non résidentes, sont soumis à la TVA au Congo.Digital services supplied to customers located in the Congo by non-resident businesses are subject to VAT in the Congo.
 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Withdrawn: report of DR Congo VAT on cross-border digital services effective 1 July 2026