Czech Republic confirms input VAT is deductible no earlier than the period the invoice arrives
- Jurisdiction
- Czech Republic
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Watch
- Announced
- 13 April 2026
- Effective
- 9 September 2026
- Authority
- Generální finanční ředitelství (General Financial Directorate), Czech Republic
- Systems
- Tax engine, ERP
- Verified
- Fetched from official source · high confidence
Czech VAT payers that receive a supplier invoice in a tax period later than the one in which the taxable supply took place.
No action - monitoring only. Current practice (claiming input VAT deduction only from the tax period in which the invoice is received, per Section 73 VAT Act) continues to apply; the pending CJEU review (C-167/26 RX) may still change this position later.
Tax engineERP
On 9 September 2026 the Financial Administration of the Czech Republic (Financni sprava CR) published a formal communication (Sdeleni) on the timing of the right to deduct input VAT, stating that a VAT payer who receives a tax document in the tax period following the taxable supply may claim the input VAT deduction no earlier than that following period, per Section 73 of the VAT Act. The communication addresses the CJEU Tribunal judgment T-689/24 I.S.A. (11 February 2026), which it states does not change the current legal position or administrative practice because a review procedure (Case C-167/26 RX) before the Court of Justice, opened 4 March 2026, suspends application of that judgment's conclusions pending the review.
What changed in detail
The Financial Administration of the Czech Republic published a Sdělení (formal communication) on 13 April 2026 on the timing of the input VAT deduction. Where a VAT payer receives the tax document in the tax period following the one in which the taxable supply took place (DUZP), the deduction may be claimed no earlier than that following period, or in one of the later periods within the statutory time limit.
The communication applies § 73(1)(a) of Act No. 235/2004 Coll., the VAT Act — which makes holding the tax document a condition of deduction — together with § 73(2), under which the deduction may first be claimed for the tax period in which the § 73(1) conditions are met.
It also addresses the Tribunal judgment of 11 February 2026 in Case T-689/24, I. S. A., which read Articles 167, 168(a) and 178(a) of Directive 2006/112/EC as precluding a national rule of that kind. The Financial Administration states that the judgment changes neither the legal position nor administrative practice, because a review procedure before the Court of Justice — Case C-167/26 RX, opened on 4 March 2026 under Article 256(3) TFEU — is still pending, and under Article 62b of the Statute the answer under review takes effect only once that procedure ends. The direct effect of the Directive cannot be invoked to apply the judgment’s conclusions in the meantime. The communication also cites the judgment of 12 March 2026 in Case C-521/24, Aptiv Services Hungary.
:::note Correction, 21 September 2026 The frozen change this record overlays dates the communication 9 September 2026. The Financial Administration’s own page carries 13. 4. 2026 under its heading, and its Novinky 2026 index lists the same title and teaser under that date; the page shows no “aktualizováno” marker and returns no September revision. The date is corrected here to 13 April 2026.
The substantive rule is unaffected and independently verified. What the wrong date changes is the framing: a communication from April is not news of this week, and on that basis the entry would not have met the scan’s announcement window. The frozen entry is append-only, so the correction is recorded here and is owed upstream as a superseding entry. :::
What it means
Nothing changes today, and that is the point of publishing it. The Tribunal judgment was being read as licence to pull a deduction back into the period of the supply whenever the invoice arrived before the return was filed; the Financial Administration has now said in writing that it will not accept that.
The suspension is procedural, not substantive. C-167/26 RX could still confirm the Tribunal, and if it does, the timing rule in § 73 stops being defensible. Treat this as a hold rather than a resolution, and track the case number rather than the newsletter. If your ERP already posts input VAT to the DUZP period, the exposure is not hypothetical — it is a run of returns that would have to be amended in one direction or the other.
Proof
Pokud plátce obdrží daňový doklad ve zdaňovacím období následujícím po uskutečnění zdanitelného plnění (DUZP), může uplatnit nárok na odpočet daně, kterou vůči němu uplatnil jiný plátce, nejdříve za toto následující zdaňovací období.If a payer receives the tax document in the tax period following the one in which the taxable supply took place (DUZP), it may claim the right to deduct the tax charged to it by another payer no earlier than for that following tax period.
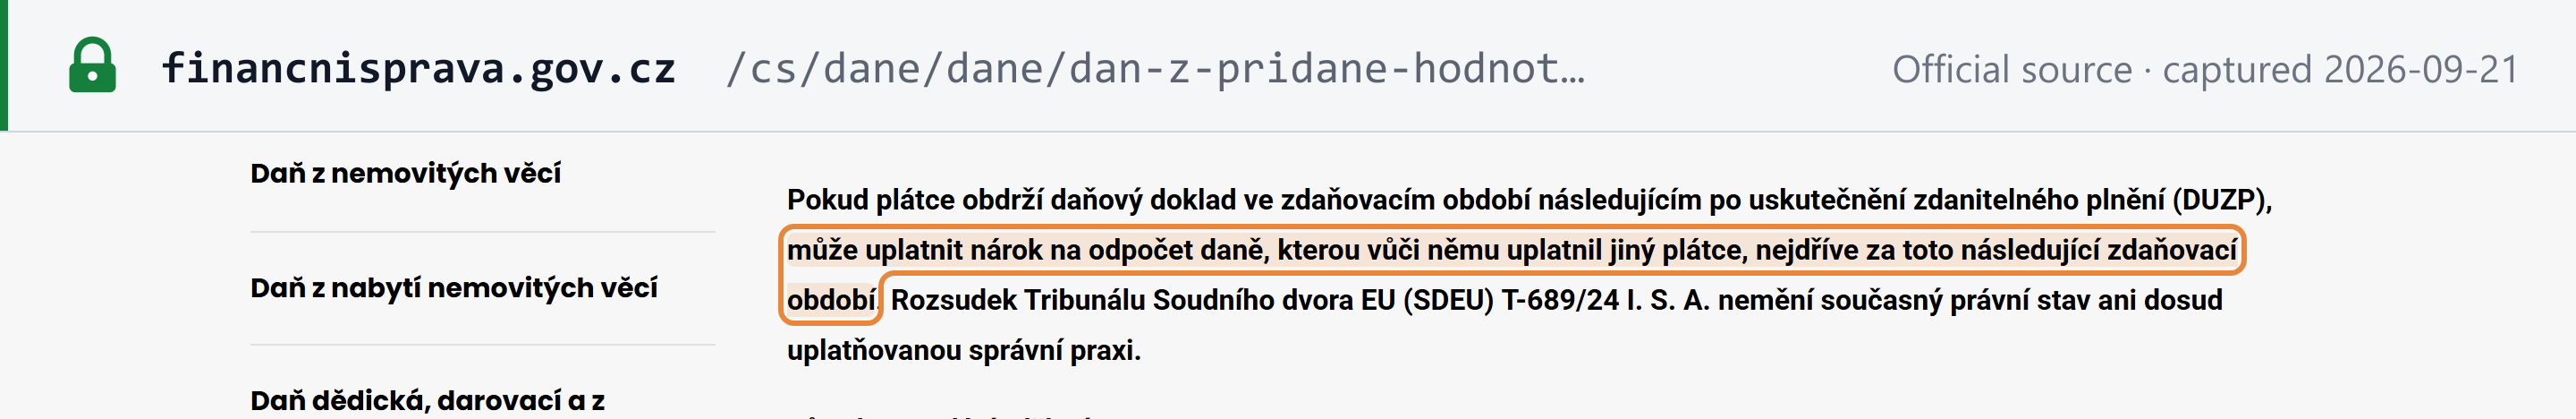 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Sdělení Finanční správy ČR k okamžiku uplatnění nároku na odpočet daně (DPH), published 13 April 2026 · financnisprava.gov.cz