Denmark: Commission proposes, not yet adopted, to extend the DKK 40-a-day flat VAT for private use of vans to 31 December 2029
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Denmark as they stand today, see the Denmark guide →
- Jurisdiction
- Denmark
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- FYI
- Announced
- 10 September 2026
- Authority
- European Commission — Taxation and Customs Union
- Systems
- Tax engine
- Verified
- Fetched from official source · high confidence
Danish businesses with light goods vehicles up to three tonnes registered solely for business use that are privately used.
No action — monitoring only.
Tax engine
The European Commission proposed on 10 September 2026 (COM(2026) 461 final, 2026/0255 (NLE); transmitted to the Council on 16 September 2026 as document 13264/26) a Council Implementing Decision extending Denmark's authorisation under Implementing Decision (EU) 2018/485, in derogation from Article 75 of Directive 2006/112/EC, to apply a flat VAT amount of DKK 40 per day (up to 20 days a year) for private use of light goods vehicles up to three tonnes registered solely for business use. The period of application would move from 31 December 2026 to 31 December 2029, with any further extension request due by 31 March 2029. The flat amount, weight threshold and 20-day cap are unchanged. The proposal needs unanimous Council approval.
What changed in detail
This is a proposal, not an adopted decision. The European Commission proposed on 10 September 2026 (COM(2026) 461 final, 2026/0255 (NLE); transmitted to the Council on 16 September 2026 as document 13264/26) a Council Implementing Decision extending Denmark’s authorisation under Implementing Decision (EU) 2018/485. The authorisation derogates from Article 75 of Directive 2006/112/EC and lets Denmark apply a flat VAT amount of DKK 40 per day, up to 20 days a year, for private use of light goods vehicles up to three tonnes registered solely for business use.
The period of application would move from 31 December 2026 to 31 December 2029, with any further extension request due by 31 March 2029. The flat amount, weight threshold and 20-day cap are unchanged. The proposal needs unanimous Council approval.
What it means
The measure expires at the end of 2026 unless the Council adopts the extension in time. Because the terms are unchanged, affected businesses would see no change in how private van use is accounted for if the proposal passes.
Proof
extend the period of application of the special measure from 31 December 2026 to 31 December 2029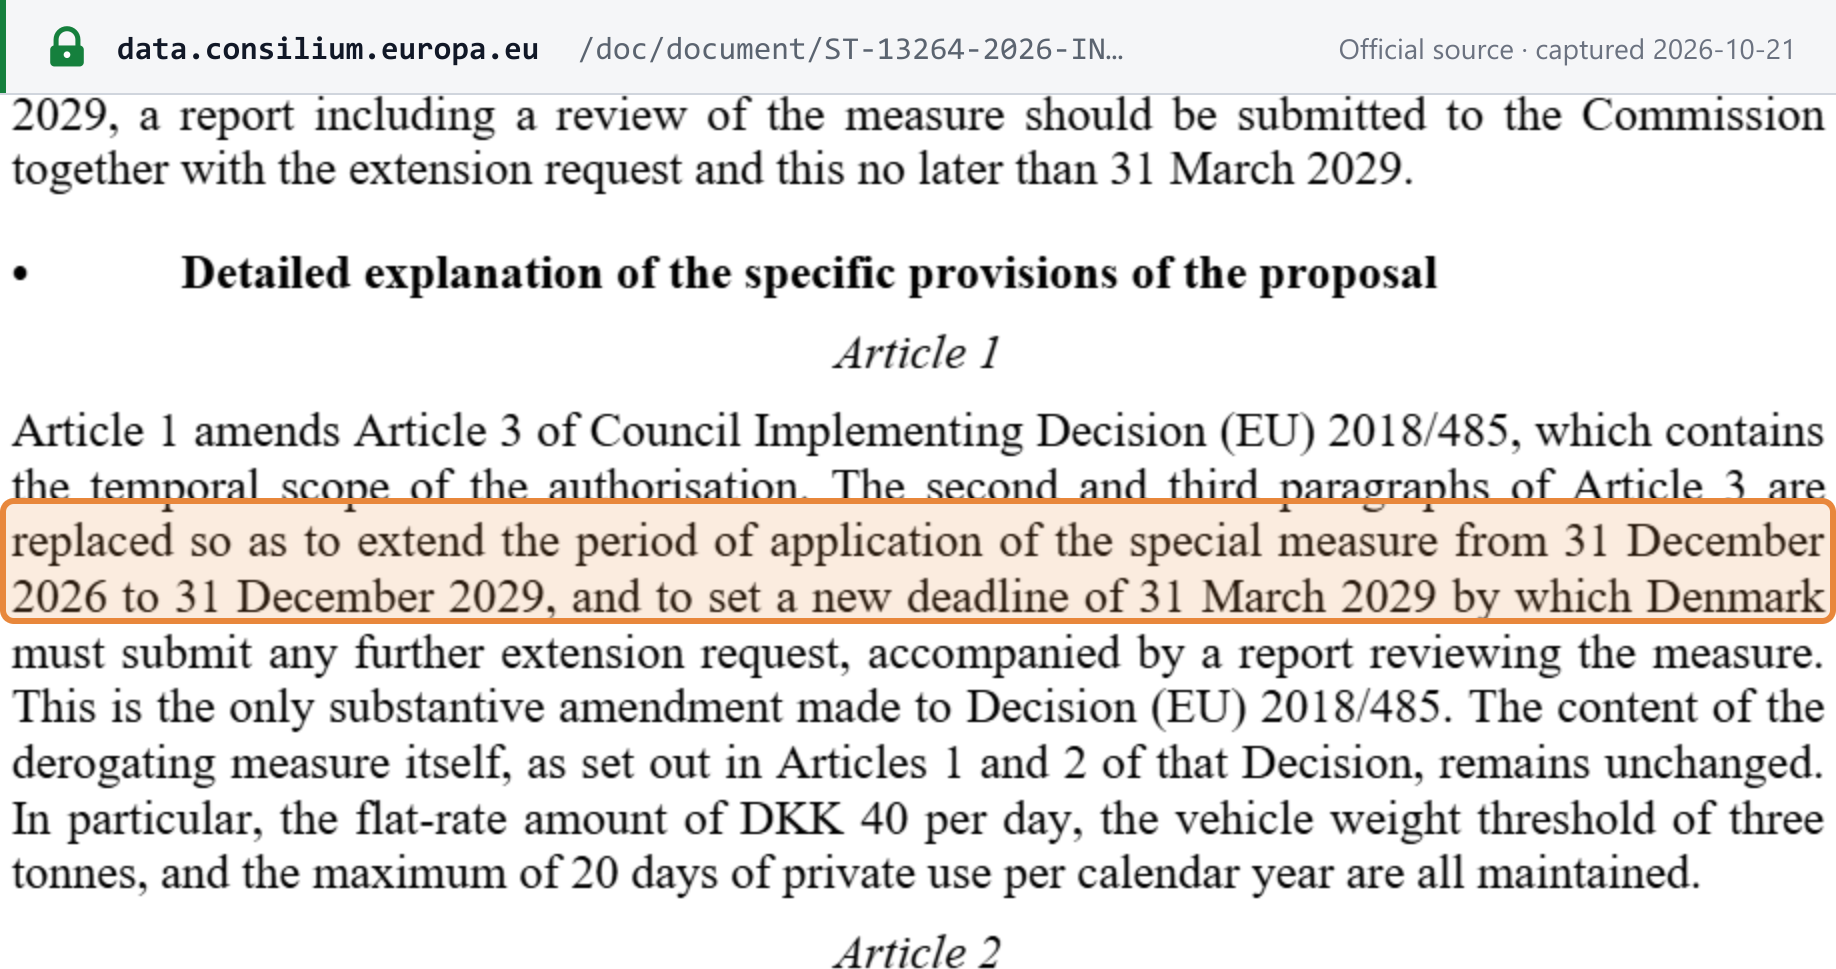 Source snapshot of the official page. Open full size ↗