Eswatini legalises electronic VAT invoices and requires designated taxpayers to send fiscal data to the ERS e-Invoicing System (Legal Notice No. 111 of 2026)
- Jurisdiction
- Eswatini
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Plan ahead
- Announced
- 20 July 2026
- Effective
- 15 July 2026
- Authority
- Eswatini Revenue Service
- Systems
- ERP, Invoicing, POS, Reporting
- Verified
- Fetched from official source · high confidence
VAT-registered businesses in Eswatini designated by the ERS Commissioner General, with wholesale and retail the first sectors; suppliers of electronic fiscal devices.
Eswatini VAT-registered businesses (wholesale and retail first) should prepare to issue invoices and receipts through an ERS-accredited fiscal device or system and await the Commissioner General's phase-in notice.
ERPInvoicingPOSReporting
Eswatini's Minister for Finance issued Legal Notice No. 111 of 2026, the Value Added Tax Act (Amendment of Third Schedule) Notice, 2026, inserting a new paragraph 1bis in the Third Schedule to the VAT Act 2011: a tax invoice, credit note or debit note may be issued in electronic form through an electronic fiscal device or other system authorised by the Commissioner General, and a fiscal receipt may likewise be issued electronically; electronic documents issued in accordance with it are valid for the purposes of the VAT Act. The notice takes effect on its date of gazette publication (ERS posted it on 20 July 2026). Under it, the ERS Commissioner General issued the Value Added Tax (Electronic Submission of Fiscal Data and Return-Supporting Records) Notice, 2026, in force 15 July 2026, requiring persons so designated to record transactions through an accredited EFD and submit fiscal data to the ERS e-Invoicing System: a fiscal document per transaction (tax invoice where the buyer is identified for VAT, carrying the buyer's TIN; fiscal receipt otherwise), transmission in real time or within fifteen days, with phased implementation by category, sector or date to be set by the Commissioner General. No general mandatory compliance date has been announced; wholesale and retail are the first sectors.
What changed in detail
Eswatini’s Minister for Finance issued Legal Notice No. 111 of 2026, the Value Added Tax Act (Amendment of Third Schedule) Notice, 2026. It inserts a new paragraph 1bis in the Third Schedule to the VAT Act 2011. A tax invoice, credit note or debit note may be issued in electronic form through an electronic fiscal device or another system authorised by the Commissioner General, and a fiscal receipt may likewise be issued electronically. Electronic documents issued in accordance with it are valid for the purposes of the VAT Act. The notice takes effect on its date of gazette publication; the ERS posted it on 20 July 2026.
Under that power, the ERS Commissioner General issued the Value Added Tax (Electronic Submission of Fiscal Data and Return-Supporting Records) Notice, 2026, in force from 15 July 2026. It requires persons so designated to record transactions through an accredited electronic fiscal device (EFD) and submit fiscal data to the ERS e-Invoicing System. A fiscal document is issued for each transaction: a tax invoice where the buyer is identified for VAT, carrying the buyer’s TIN, and a fiscal receipt otherwise. Data is transmitted in real time or within fifteen days. Implementation is phased by category, sector or date, to be set by the Commissioner General.
No general mandatory compliance date has been announced. Wholesale and retail are the first sectors.
What it means
The legal basis is in place, but the obligation bites only for taxpayers the Commissioner General designates, so the first question for a business is whether it has been told it is in the first phase. Retailers and wholesalers should start looking at accredited EFD suppliers and at how their systems capture the buyer’s TIN. For other sectors, the timetable is still to be set.
Proof
This Notice shall come into force on 15 July 2026.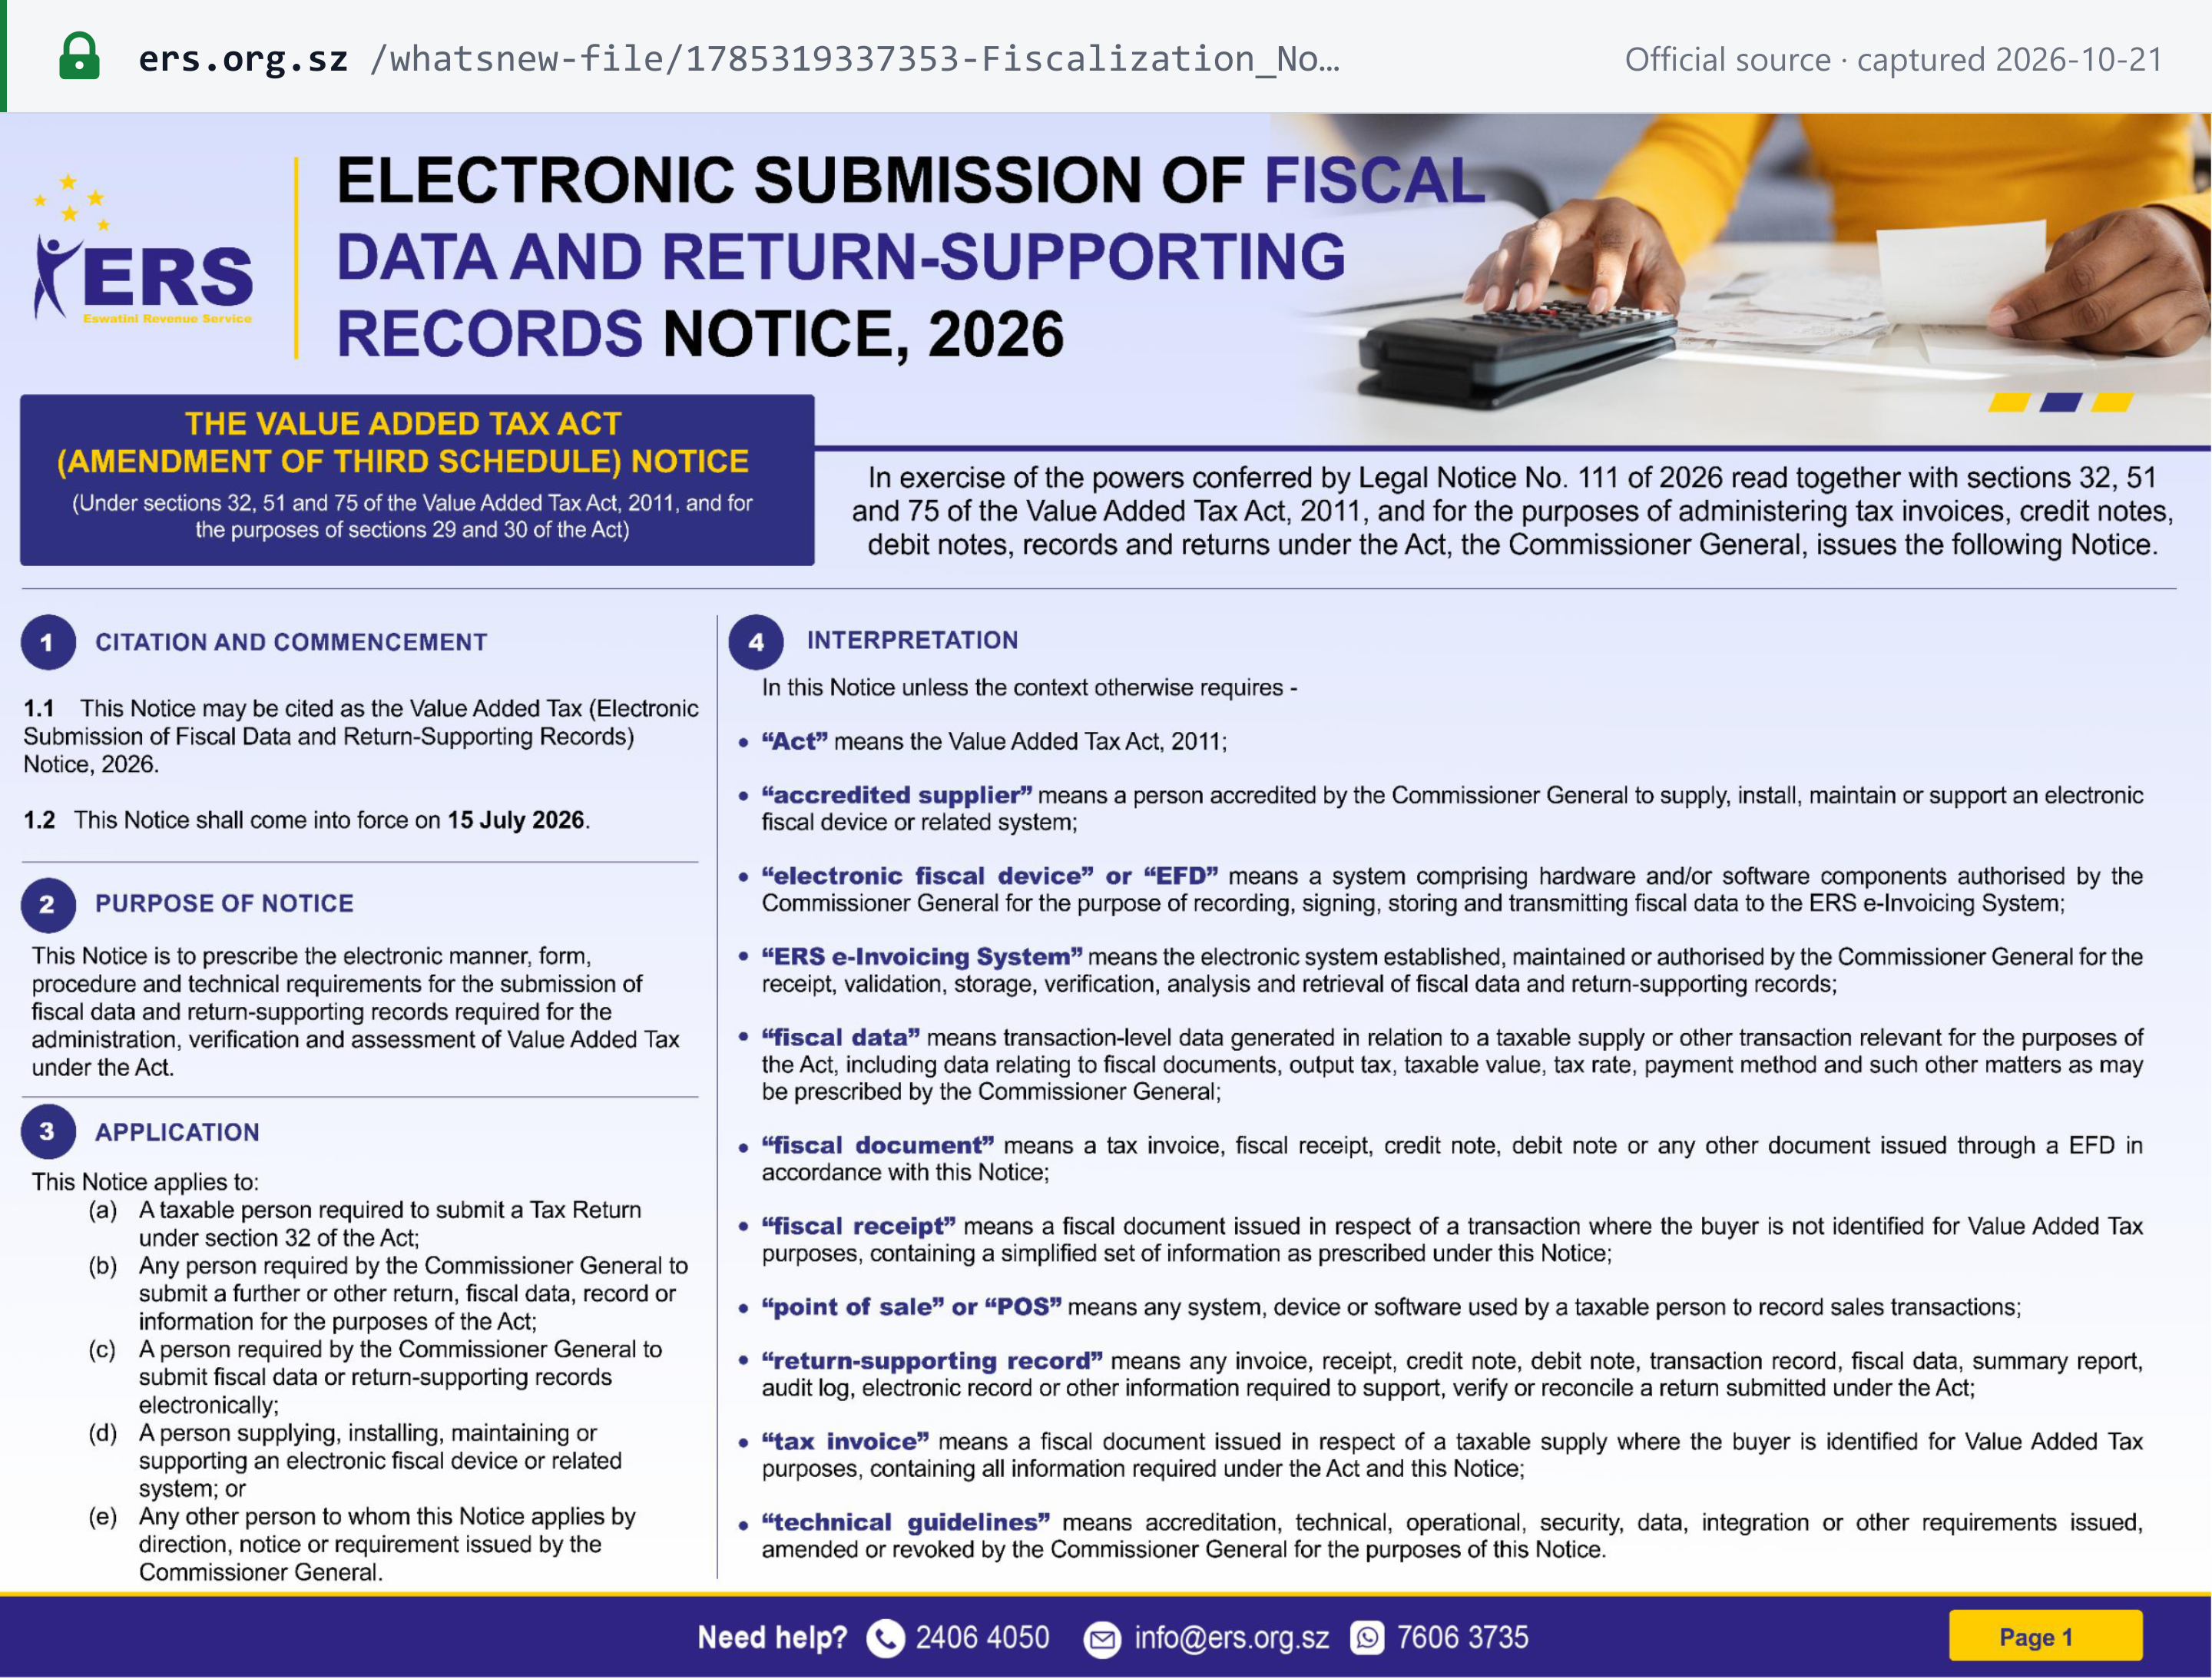 Source snapshot of the official page. Open full size ↗