EU names a single importer for distance sales in its new Union Customs Code
- Jurisdiction
- European Union
- Tax
- Customs/VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 19 September 2026
- Effective
- 21 September 2027
- Authority
- Publications Office of the European Union - Official Journal of the European Union
- Systems
- Customs, E-commerce, ERP, Reporting
- Verified
- Fetched from official source · high confidence
Any business that supplies or facilitates distance sales of goods imported into the EU - Article 5(14) fixes which single entity in that chain is the importer.
If you supply or facilitate distance sales of goods imported into the EU, map which entity in your chain becomes the single importer under Article 5(14) and plan for the EU Customs Data Hub and Trust and Check Trader regime ahead of 21 September 2027.
CustomsE-commerceERPReporting
Regulation (EU) 2026/2108 of the European Parliament and of the Council of 16 September 2026 establishing the Union Customs Code and the European Union Customs Authority, and repealing Regulation (EU) No 952/2013, was published in the Official Journal L series on 19 September 2026. Article 5, point (14) defines an importer for distance sales as either the person supplying goods in distance sales or the person facilitating distance sales, with distance sales taking the meaning in Article 14(4), point (2) of Directive 2006/112/EC and the IOSS scheme the meaning in Title XII, Chapter 6, Section 4 of that Directive. Recital 62 states that there should be only one importer at a time. Article 287 provides that the Regulation enters into force on the day following publication and applies from 21 September 2027, with an enumerated list of provisions (including Article 5 points (15), (16), (44) and (78), Articles 35 to 39 and 51, Articles 229 to 231 and 234 to 244 and 255 to 265, and all delegated and implementing empowerments) applying from entry into force.
What changed in detail
Regulation (EU) 2026/2108 of the European Parliament and of the Council of 16 September 2026, establishing the Union Customs Code and the European Union Customs Authority and repealing Regulation (EU) No 952/2013, was published in the Official Journal L series on 19 September 2026.
Article 5, point (14) defines an importer for distance sales as either the person supplying goods in distance sales, or the person facilitating distance sales - with “distance sales” and the IOSS scheme taking the meanings already set in Directive 2006/112/EC. Recital 62 states there should be only one importer at a time. Article 287 sets entry into force on the day after publication, with the Regulation applying generally from 21 September 2027; an enumerated list of provisions - including the customs-authority and Trust and Check Trader provisions - applies from entry into force instead.
What it means
The single-importer rule is the operative change for e-commerce supply chains: today a marketplace, a fulfilment provider and the underlying seller can each plausibly claim, or deny, being the importer of record, and Recital 62 closes that ambiguity by design rather than by guidance. Anyone in a distance-sales chain should map now which entity becomes the importer under Article 5(14) - the answer determines who registers, who declares, and who is liable if the declaration is wrong - well ahead of the 21 September 2027 application date, since the customs-authority infrastructure provisions are already live from entry into force.
Proof
‘importer for distance sales’ means either the person supplying goods in distance sales or the person facilitating distance sales;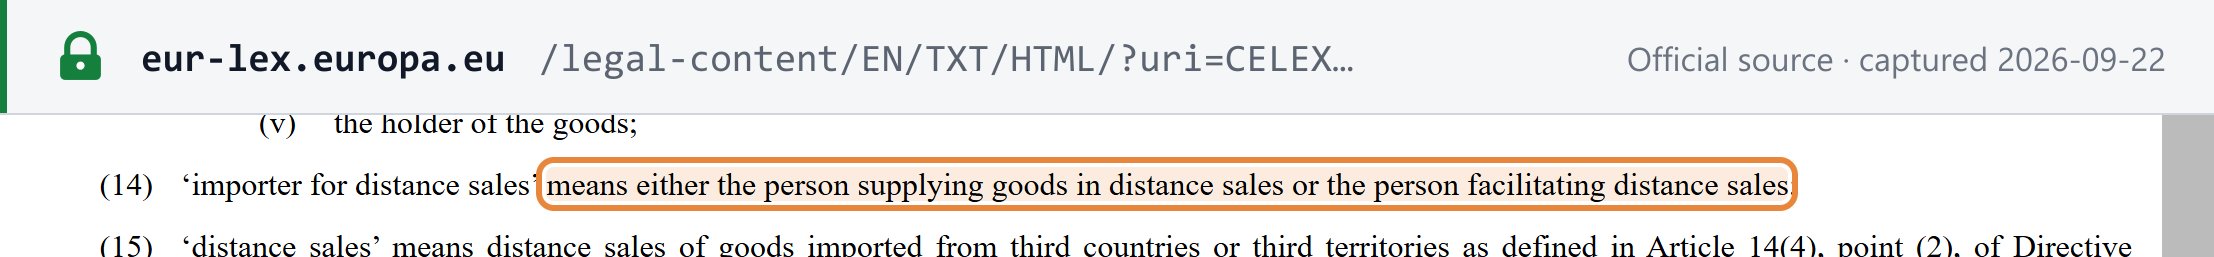 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · eur-lex.europa.eu