France finalises its BOFiP commentary on the international VAT agent (mandataire à l'international) regime
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Watch
- Announced
- 14 October 2026
- Effective
- 14 October 2026
- Authority
- Direction générale des Finances publiques (DGFiP)
- Systems
- Tax engine, Customs, Reporting
- Verified
- Fetched from official source · high confidence
Non-established, non-VAT-identified businesses importing goods into France, and the French-established agents that act for them under article 289 A bis CGI.
Non-established importers using or considering a French international agent: review the mandate scope against the finalised doctrine.
Tax engineCustomsReporting
DGFiP finalised, on 14 October 2026, the BOFiP commentary on the optional 'mandataire à l'international' (international agent) VAT regime of article 289 A bis CGI, following a public consultation. The regime lets a non-established, non-VAT-identified taxable person appoint a French-established agent to discharge its VAT obligations on goods entrusted to the agent, limited to imports with fully deductible VAT and certain article 95 ter annex III CGI operations (trade with third territories) that are exempt with right of deduction, payment-exempt or suspended.
What changed in detail
On 14 October 2026 the DGFiP finalised the BOFiP commentary BOI-TVA-DECLA-20-30-40-30 on the ‘mandataire à l’international’ (international agent) regime of article 289 A bis of the Code général des impôts, updating the text following a public consultation.
The regime is optional. It lets a taxable person that is not established in France and has no French VAT identification appoint an agent established in France to discharge its VAT obligations on goods entrusted to the agent. The scope is limited to imports on which the VAT is fully deductible and to certain operations under article 95 ter of annex III to the CGI (trade with third territories) that are exempt with a right of deduction, exempt from payment or suspended.
What it means
The practical point is the scope limit: the regime does not cover every import by a non-established business, only the fully deductible imports and the listed third-territory operations. Businesses already using a French agent, or considering one, should compare their mandate wording and the goods it covers with the finalised commentary, because the doctrine is what the administration will apply on audit.
Proof
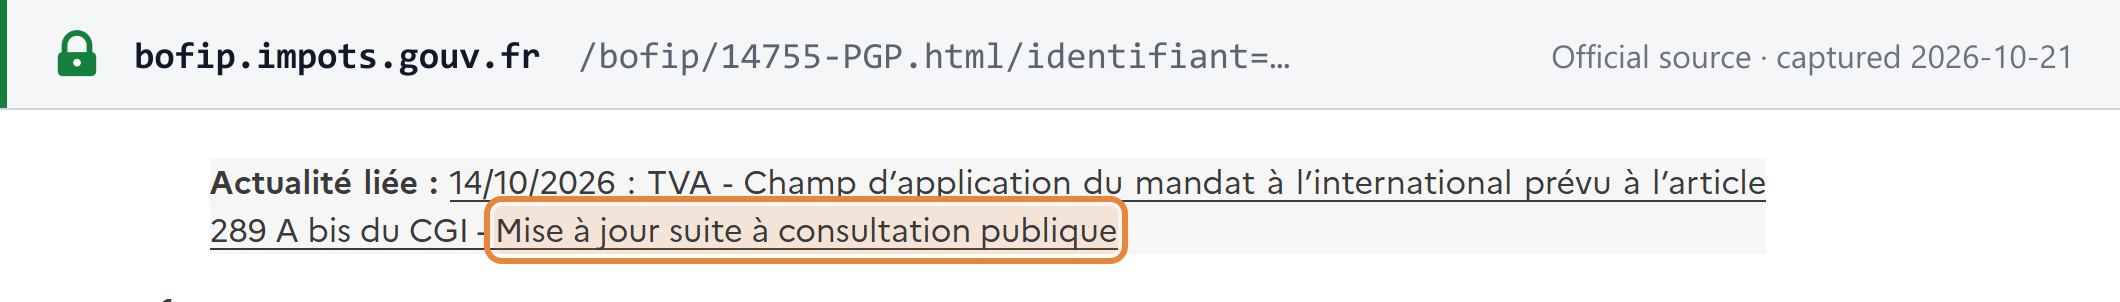
Actualité liée : 14/10/2026 : TVA - Champ d’application du mandat à l’international prévu à l’article 289 A bis du CGI - Mise à jour suite à consultation publiqueRelated news: 14/10/2026: VAT - Scope of the international mandate provided for in article 289 A bis of the CGI - Update following public consultation.
 Source snapshot of the official page. Open full size ↗