France's 2027 finance bill would amend property VAT rules in the CIBS (article 19) - proposed, not law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Update
- Status
- Proposed
- Impact
- Watch
- Announced
- 1 October 2026
- Effective
- 1 January 2027
- Authority
- Assemblée nationale
- Systems
- ERP, Invoicing, Tax engine
- Verified
- Fetched from official source · high confidence
Property developers, landlords letting unequipped land or under long leases (bail à construction, emphytéotique, réel immobilier, réel solidaire), press-distribution agents and commemorative-monument contractors.
No action — monitoring only. Track parliamentary amendments to article 19 of the PLF 2027 before the December vote.
ERPInvoicingTax engine
Article 19 of the projet de loi de finances pour 2027 (n° 3210, registered at the Assemblée nationale on 1 October 2026) would amend the VAT provisions of the Code des impositions sur les biens et services (CIBS) as they stand after Ordonnance n° 2026-671: it adds press-distribution agent services (L. 213-217) and commemorative monument works (L. 213-224) to the categories of zero-rated operations dispensed from the invoicing obligation (L. 216-31); it would let taxable persons opt to tax lettings of unequipped land; it would exempt, with a landlord option to waive the exemption, lettings of immovable property under a lease conferring a real right (new L. 231-35-1: bail à construction, bail emphytéotique, bail réel immobilier, bail réel solidaire); it would make VAT on deliveries of buildings to be constructed (immeubles à construire) payable on each receipt of consideration (new L. 231-36-1); and it would ratify Ordonnance n° 2025-1247 and Ordonnance n° 2026-671. Article 33 sets 1 January 2027 as the default entry-into-force date for the bill's tax measures unless otherwise provided.
What changed in detail
This is a bill, not law. Article 19 of the projet de loi de finances pour 2027 (n° 3210), registered at the Assemblée nationale on 1 October 2026, would amend the VAT provisions of the Code des impositions sur les biens et services (CIBS) as they stand after Ordonnance n° 2026-671.
As drafted, article 19 would:
- add press-distribution agent services (L. 213-217) and commemorative monument works (L. 213-224) to the categories of zero-rated operations dispensed from the invoicing obligation (L. 216-31);
- let taxable persons opt to tax lettings of unequipped land;
- exempt lettings of immovable property under a lease conferring a real right (new L. 231-35-1: bail à construction, bail emphytéotique, bail réel immobilier, bail réel solidaire), with a landlord option to waive the exemption;
- make VAT on deliveries of buildings to be constructed (immeubles à construire) payable on each receipt of consideration (new L. 231-36-1);
- ratify Ordonnance n° 2025-1247 and Ordonnance n° 2026-671.
Article 33 sets 1 January 2027 as the default entry-into-force date for the bill’s tax measures unless otherwise provided.
What it means
Everything here depends on the parliamentary vote, and amendments to article 19 can still change it. Treat the text as a signal of direction, not a rule to build against.
The measure with the widest cash-flow effect is the receipt-based chargeability for buildings to be constructed, which matters for off-plan sales paid in instalments. Developers and their ERP and invoicing set-ups should track the amended text before the December vote and plan for 1 January 2027 only if it survives unchanged.
Proof
il propose, pour les livraisons d’immeubles à construire, l’application d’une règle d’exigibilité de la TVA à l’encaissementit proposes, for deliveries of buildings to be constructed, the application of a rule making VAT chargeable on receipt of payment
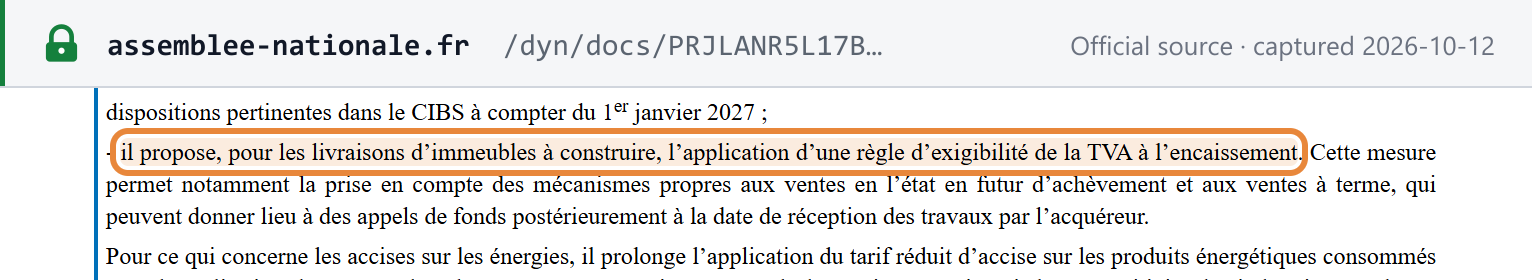 Source snapshot of the official page. Open full size ↗