France proposes simplifying VAT rates for television services in PLF 2027 (article 16)
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 1 October 2026
- Effective
- 1 January 2027
- Authority
- Assemblée nationale
- Systems
- Tax engine, Invoicing, E-commerce
- Verified
- Fetched from official source · high confidence
Providers of television services and composite TV and on-demand subscriptions in France.
No action — monitoring only. Model the loss of the reduced-rate treatment for TV and bundled TV/on-demand subscriptions as a scenario for 1 January 2027; do not change rates until enacted.
Tax engineInvoicingE-commerce
Article 16 of the projet de loi de finances pour 2027 (n° 3210, registered 1 October 2026) would delete the ninth and tenth lines of the rate table in article L. 213-230 of the Code des impositions sur les biens et services and repeal article L. 213-235, which together set out the VAT rates for television services. The explanatory memorandum presents the measure as a simplification of VAT rates for television services, citing the difficulty of applying a single VAT treatment to composite TV and on-demand subscriptions. Under Article 33, tax measures take effect on 1 January 2027 unless otherwise provided. The bill text read does not state the resulting rate. Figures in a bill are provisional until enacted.
What changed in detail
This is a bill, not law. Article 16 of the projet de loi de finances pour 2027 (n° 3210, registered 1 October 2026) would delete the ninth and tenth lines of the rate table in article L. 213-230 of the Code des impositions sur les biens et services and repeal article L. 213-235. Together these set out the VAT rates for television services.
The explanatory memorandum presents the measure as a simplification of VAT rates for television services, citing the difficulty of applying a single VAT treatment to composite TV and on-demand subscriptions.
Under Article 33, tax measures take effect on 1 January 2027 unless otherwise provided. The bill text read does not state the resulting rate. Figures in a bill are provisional until enacted.
What it means
The article removes specific rate lines but, in the text read, does not say which rate would apply afterwards. That gap makes any statement that TV services “will be taxed at” a given rate premature.
Subscription providers whose offers mix TV and on-demand content are the group the memorandum points to. Wait for the amended and adopted text before changing prices or tax codes.
Proof
Le présent article procède à la simplification des taux de taxe sur la valeur ajoutée (TVA) applicables aux services de télévision.This article simplifies the value added tax (VAT) rates applicable to television services.
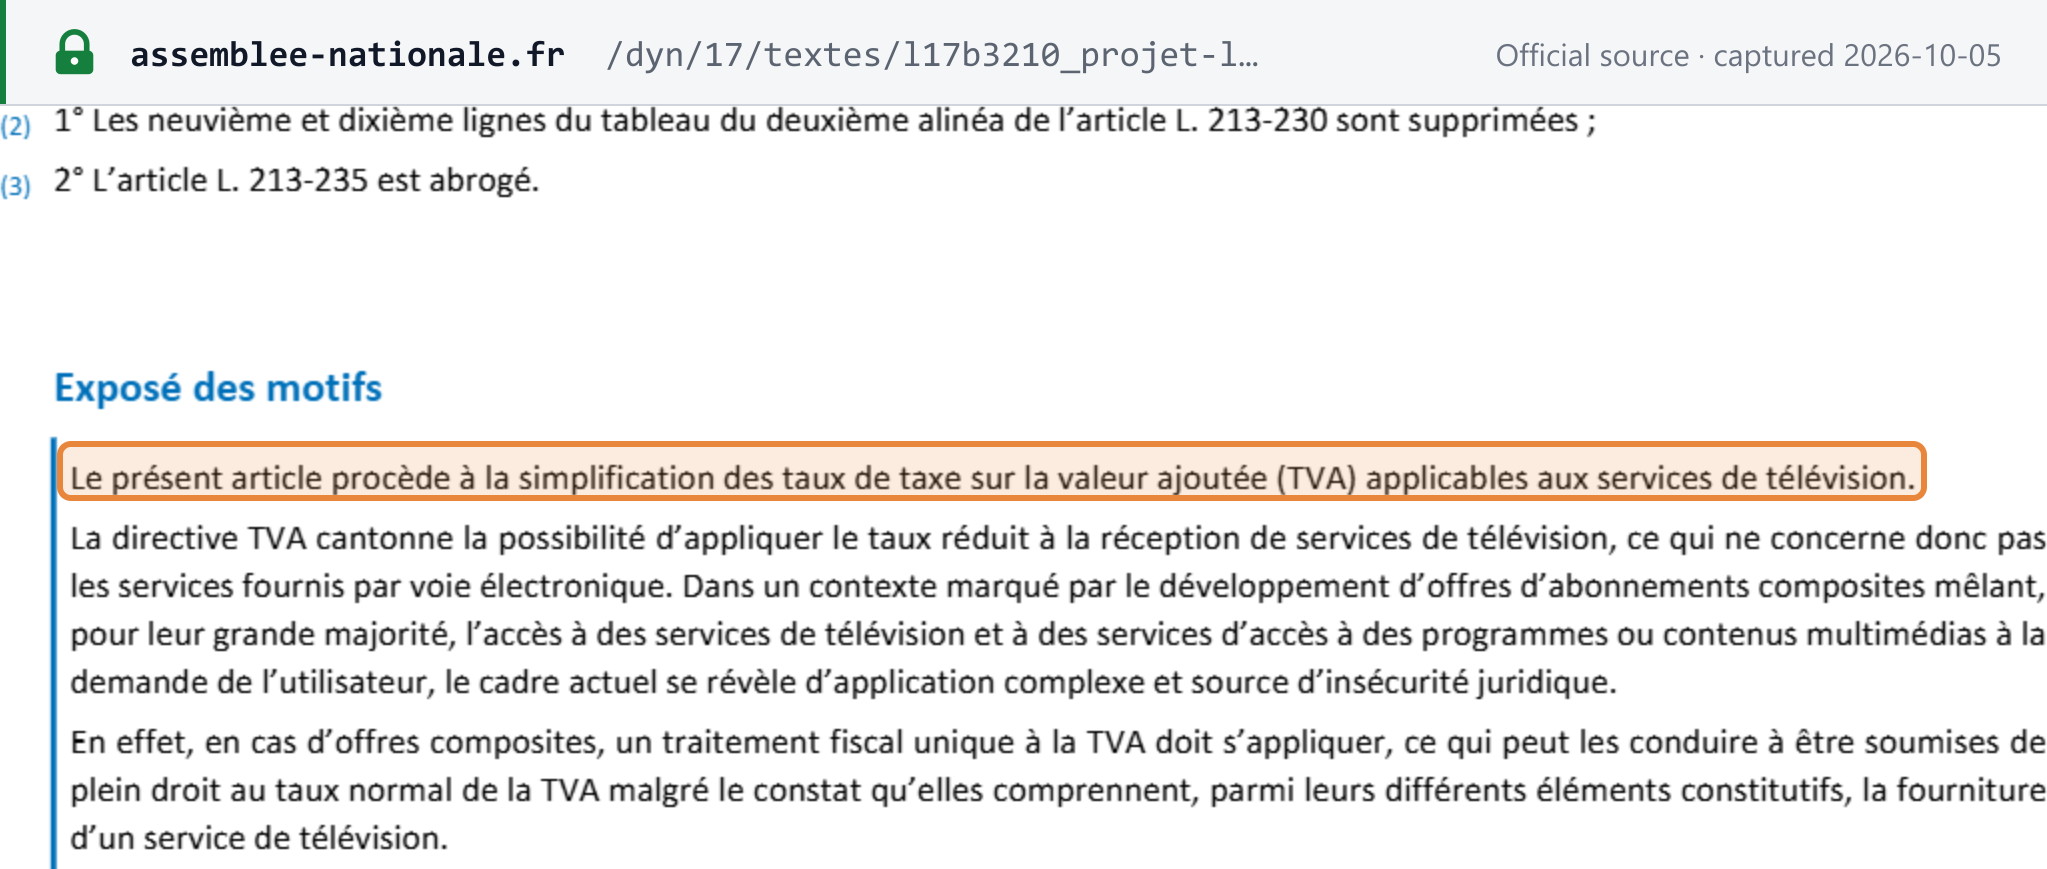 Source snapshot of the official page. Open full size ↗