France proposes new penalties on the VAT export exemption for non-resident travellers in PLF 2027 (article 32)
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Compliance
- Status
- Proposed
- Impact
- Watch
- Announced
- 1 October 2026
- Effective
- 1 January 2027
- Authority
- Assemblée nationale
- Systems
- POS, Reporting
- Verified
- Fetched from official source · high confidence
Taxable persons issuing export-proof documents for non-resident travellers, approved intermediaries, and travellers who obtain the exemption.
No action — monitoring only. Tax-free shopping operators and retailers: review export-proof document controls ahead of a possible 1 January 2027 start.
POSReporting
Article 32 of the projet de loi de finances pour 2027 (n° 3210) proposes new penalties around the VAT export exemption for non-resident travellers (article L. 213-15 CIBS): a fine of up to EUR 60 per export-proof document issued in breach of the conditions, capped at EUR 1 million per year per taxable person; a fine of 50% of the VAT wrongly exempted, refunded or claimed for any taxable person fraudulently involved in producing or transmitting the documents; the same 50% fine for non-taxable persons who fraudulently obtain the exemption; and withdrawal of approval and a fine up to EUR 500,000 for an approved intermediary that assists unapproved intermediaries (article 1788 F CGI as amended). Article 32 V provides that the article enters into force on 1 January 2027.
What changed in detail
This is a bill, not law. Article 32 of the projet de loi de finances pour 2027 (n° 3210) proposes new penalties around the VAT export exemption for non-resident travellers (article L. 213-15 CIBS).
The proposed penalties are:
- a fine of up to EUR 60 per export-proof document issued in breach of the conditions, capped at EUR 1 million per year per taxable person;
- a fine of 50% of the VAT wrongly exempted, refunded or claimed for any taxable person fraudulently involved in producing or transmitting the documents;
- the same 50% fine for non-taxable persons who fraudulently obtain the exemption;
- withdrawal of approval and a fine of up to EUR 500,000 for an approved intermediary that assists unapproved intermediaries (article 1788 F CGI as amended).
Article 32 V provides that the article enters into force on 1 January 2027.
What it means
The per-document fine scales with volume, which is why the annual cap of EUR 1 million per taxable person exists. Retailers and refund intermediaries issuing large numbers of export documents are the most exposed to the document-level fine.
Nothing here applies until the finance law is adopted, and amounts and conditions can change in Parliament. The fraud-based fines are defined by reference to VAT wrongly exempted, so they are not capped in the same way.
Proof
En cas de non-respect par un assujetti des conditions prévues au 4° de l’article L. 213-15 du code des impositions sur les biens et services, l’administration peut prononcer une amende dont le montant fixé par décret en Conseil d’État ne peut pas excéder 60 € par document émis à titre de preuve à l’exportation, dans la limite d’un plafond total d’un million d’euros par an et par assujetti.Where a taxable person fails to comply with the conditions of 4° of article L. 213-15 of the code des impositions sur les biens et services, the administration may impose a fine whose amount, set by décret en Conseil d'État, may not exceed EUR 60 per document issued as proof of export, up to a total ceiling of one million euros per year per taxable person.
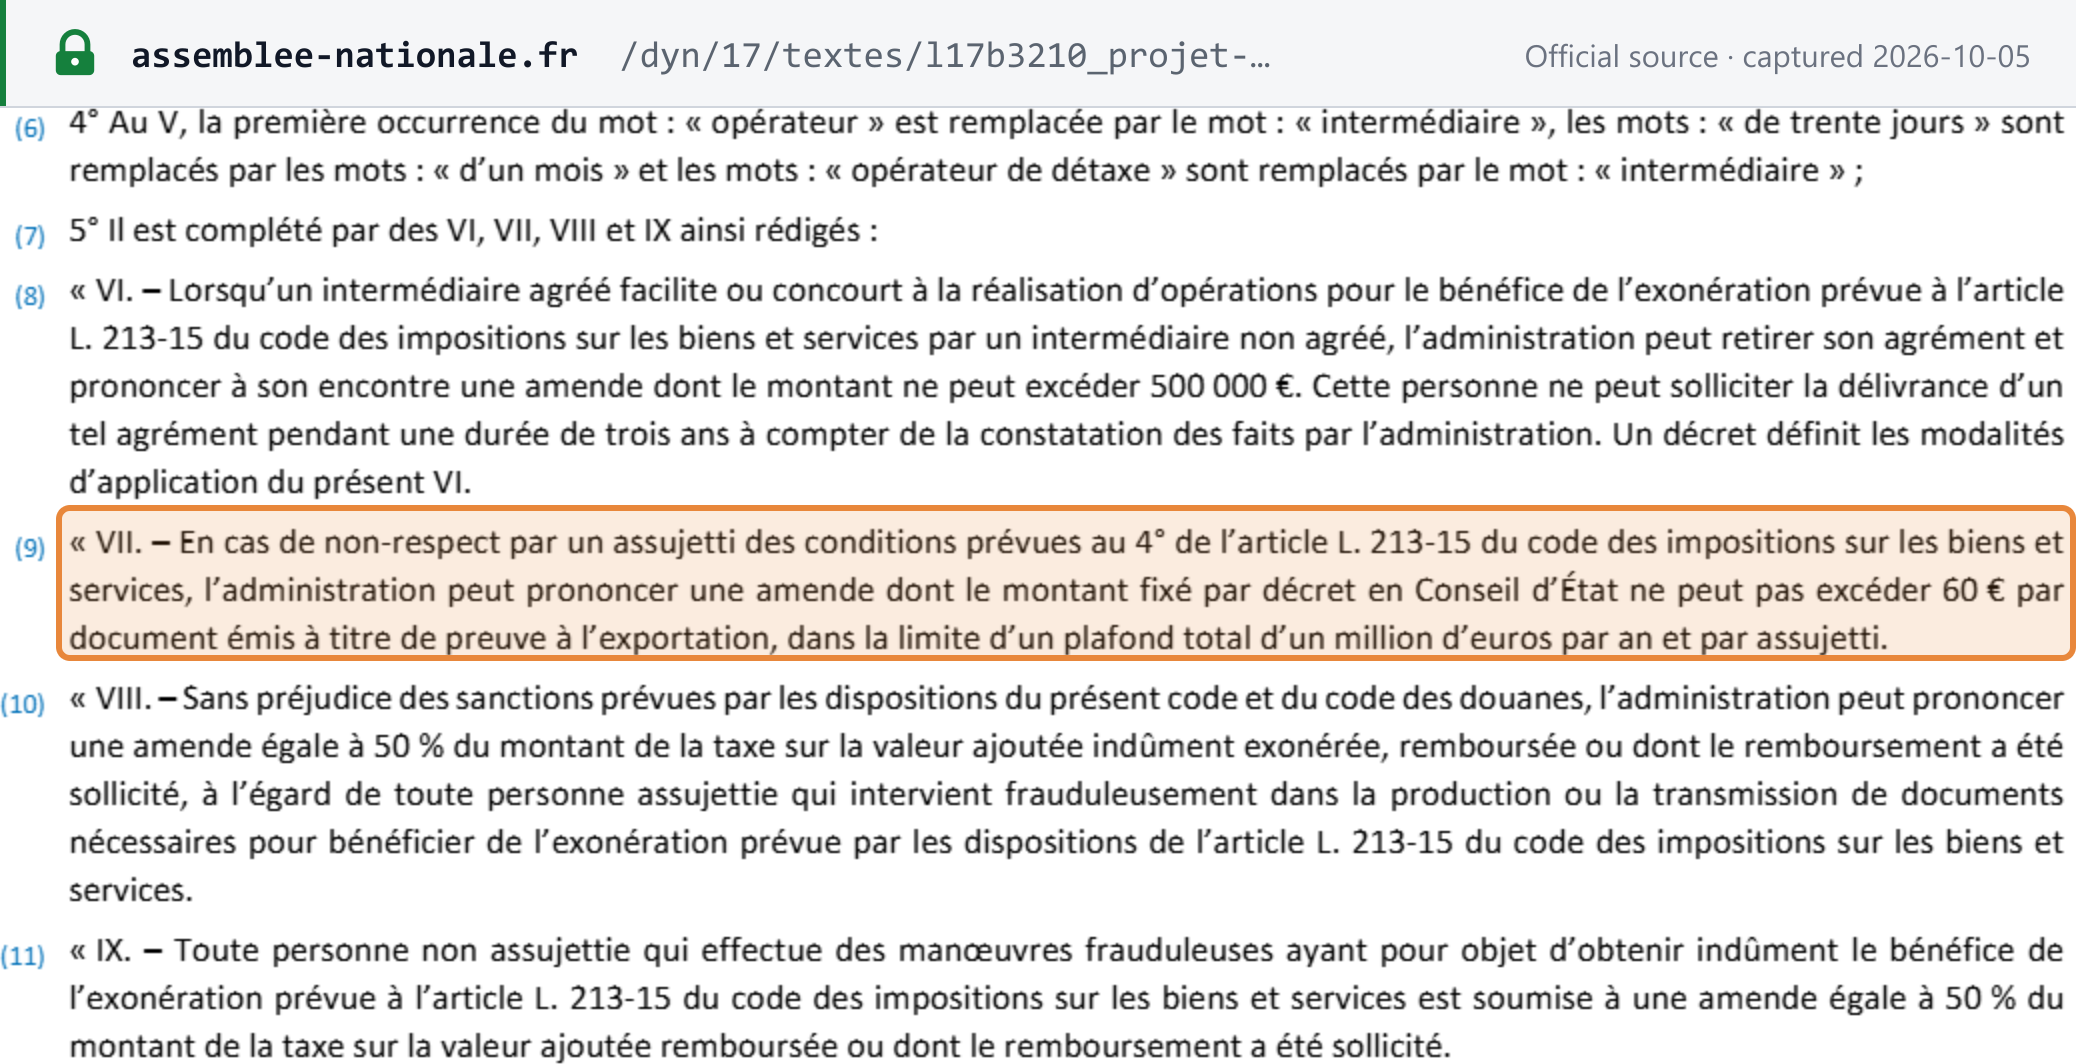 Source snapshot of the official page. Open full size ↗