France publishes the BOFiP commentary on e-reporting: 1 September 2026 for large and mid-sized companies, 1 September 2027 for SMEs
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 30 September 2026
- Effective
- 1 September 2026
- Authority
- Direction générale des Finances publiques (DGFiP)
- Systems
- ERP, Invoicing, Reporting, POS, E-commerce
- Verified
- Fetched from official source · high confidence
French large companies, mid-sized companies and single VAT taxable persons (from 1 September 2026); SMEs and micro-enterprises (from 1 September 2027).
Confirm e-reporting (transaction and payment data) flows are live for large and mid-sized companies from 1 September 2026; SMEs and micro-enterprises plan for 1 September 2027.
ERPInvoicingReportingPOSE-commerce
On 30 September 2026 BOFiP published the administrative commentary on the obligation to transmit transaction and payment data to the tax administration (e-reporting, article 26 of Loi n° 2022-1157). It states the obligations apply to invoices issued, or otherwise to transactions whose chargeable event occurs, from 1 September 2026 for large companies, mid-sized companies and single VAT taxable persons (article 256 C CGI), and from 1 September 2027 for SMEs and micro-enterprises. Commentary on the electronic invoicing provisions of article 289 bis CGI is stated to follow later.
What changed in detail
On 30 September 2026 BOFiP published the administrative commentary on the obligation to transmit transaction and payment data to the tax administration (e-reporting, article 26 of Loi n° 2022-1157).
The commentary states that the obligations apply to invoices issued, or otherwise to transactions whose chargeable event occurs, from 1 September 2026 for large companies, mid-sized companies and single VAT taxable persons (article 256 C CGI), and from 1 September 2027 for SMEs and micro-enterprises.
Commentary on the electronic invoicing provisions of article 289 bis CGI is stated to follow later.
What it means
The date test is the issue date of the invoice or, for transactions without an invoice, the date of the chargeable event. Both are relevant for businesses in the first group that are already inside the e-reporting period.
This commentary covers e-reporting only. Guidance on e-invoicing under article 289 bis is promised for later, so do not read its absence as relief.
Proof
1er septembre 2027 pour les petites et moyennes entreprises et les micro-entreprises.1 September 2027 for small and medium-sized enterprises and micro-enterprises.
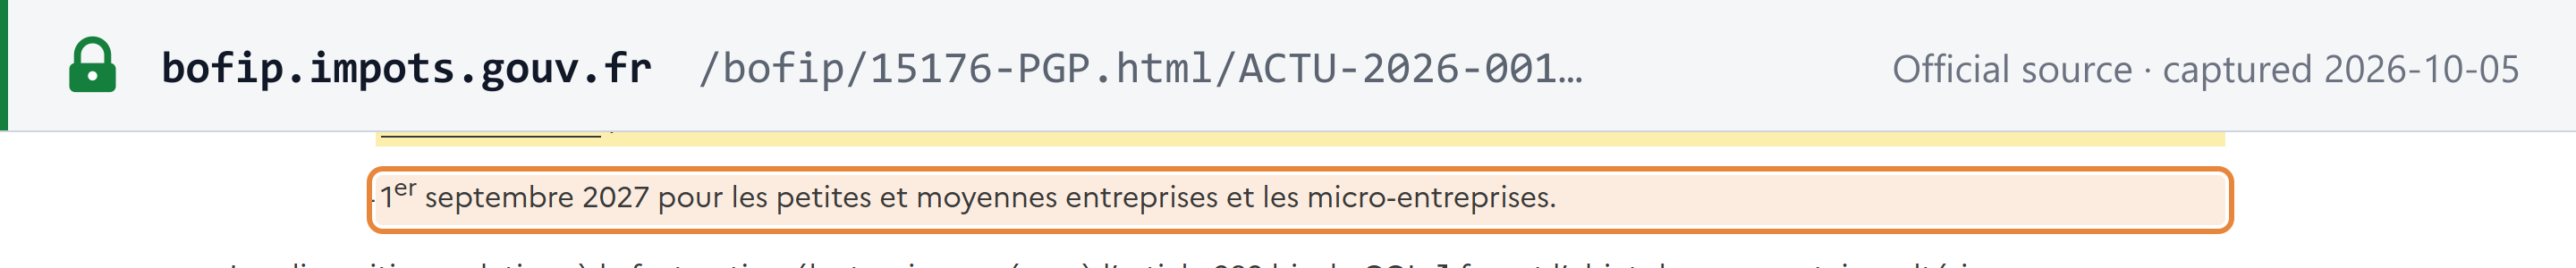 Source snapshot of the official page. Open full size ↗