France tolerates press-distribution intermediation outside the e-invoicing obligation, BOFiP rescrit of 23 September 2026
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- Plan ahead
- Announced
- 23 September 2026
- Effective
- 23 September 2026
- Authority
- Direction générale des Finances publiques (DGFiP)
- Systems
- Invoicing, ERP, Reporting
- Verified
- Fetched from official source · high confidence
Intermediaries in press distribution and their principals, for intermediation transactions under article 298 undecies of the CGI.
Press-distribution intermediaries and their principals: exclude article 298 undecies intermediation commissions from e-invoice issuance flows while keeping the current documentary follow-up; keep e-invoicing for all other transactions.
InvoicingERPReporting
A DGFiP rescrit published in BOFiP on 23 September 2026 (BOI-RES-TVA-000275) provides that transactions of intermediation under article 298 undecies of the CGI carried out by intermediaries in press distribution are admitted not to be covered by the electronic-invoicing obligation of article 289 bis CGI, provided the existing documentary follow-up of the transactions is strictly and fully maintained, pending an extension of the e-invoicing exemption to these transactions. The tolerance covers only these intermediation transactions; press intermediaries and their principals remain subject to e-invoicing for all other transactions.
What changed in detail
A DGFiP rescrit published in BOFiP on 23 September 2026 (BOI-RES-TVA-000275) provides that intermediation transactions under article 298 undecies of the CGI carried out by intermediaries in press distribution are admitted not to be covered by the electronic-invoicing obligation of article 289 bis CGI.
The tolerance applies provided the existing documentary follow-up of the transactions is strictly and fully maintained. It applies pending an extension of the e-invoicing exemption to these transactions.
It covers only these intermediation transactions. Press intermediaries and their principals remain subject to e-invoicing for all other transactions.
What it means
This is an administrative tolerance, not a change to the law. It is conditional on keeping the current documentary follow-up of these transactions in full, so dropping that follow-up would lose the benefit.
Its scope is narrow: only the article 298 undecies intermediation transactions. Everything else a press intermediary or principal invoices stays inside the e-invoicing and e-reporting rules.
Proof
il est d’ores et déjà admis que ces opérations ne soient pas couvertes par l’obligation de facturation électronique prévue à l’article 289 bis du CGI, sous réserve du strict et complet maintien du suivi documentaire des opérations en vigueurit is already admitted that these transactions are not covered by the electronic invoicing obligation provided for in article 289 bis of the CGI, subject to the strict and complete maintenance of the existing documentary follow-up of the transactions
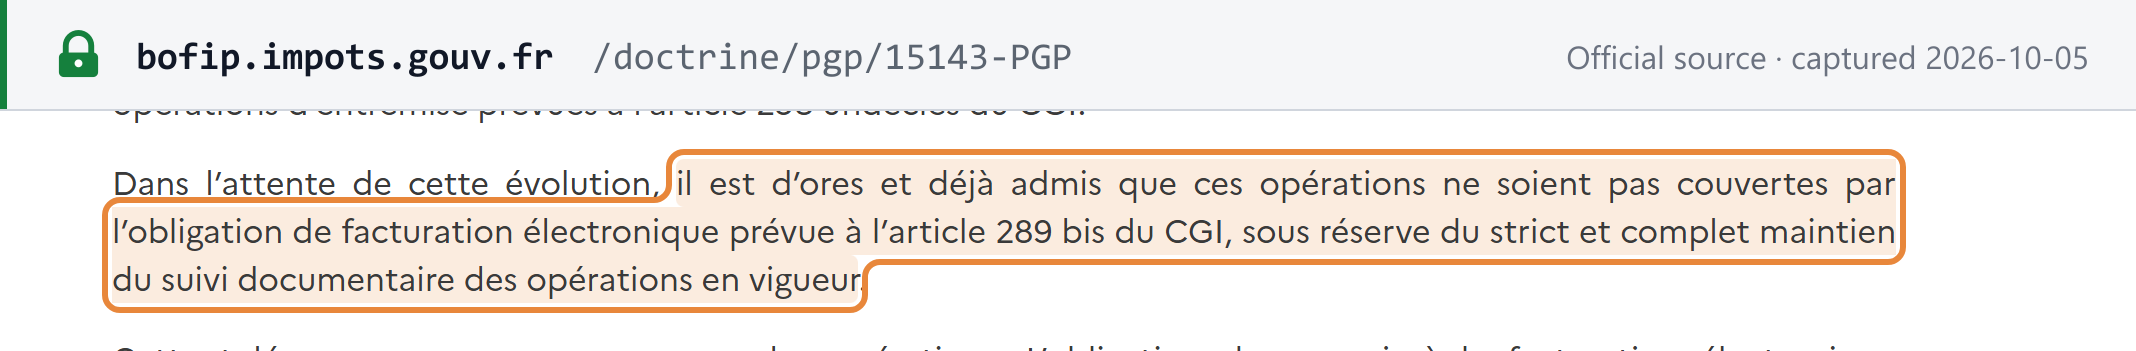 Source snapshot of the official page. Open full size ↗