France extends the 0% VAT rate to air transport within Martinique, Guadeloupe and La Réunion
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Plan ahead
- Announced
- 2 September 2026
- Effective
- 21 February 2026
- Authority
- Direction générale des Finances publiques (DGFiP) — BOFiP
- Systems
- Tax engine, ERP
- Verified
- Fetched from official source · high confidence
Airlines and freight carriers running passenger or goods services within Martinique, Guadeloupe and La Réunion, and suppliers of goods on the La Réunion-only VAT-exempt list at CGI Annexe IV, art. 50 duodecies.
Overseas-territory (Martinique/Guadeloupe/La Réunion) carriers and suppliers should confirm VAT treatment of air-transport services and update the La Réunion VAT-exempt product list used in tax-engine configuration.
Tax engineERP
DGFiP published BOFiP doctrine (ACTU-2026-00140) on 2 September 2026 confirming that article 100 of Loi n° 2026-103 du 19 février 2026 de finances pour 2026 extends the 0% VAT rate under CGI art. 295-1-1° to air transport of passengers and goods within Martinique, Guadeloupe and La Réunion (previously limited to sea transport), applicable to services from 21 February 2026. It also confirms that the Arrêté du 11 décembre 2025 modifies the list of VAT-exempt products specific to La Réunion (CGI Annexe IV, art. 50 duodecies), adding certain first-necessity goods and removing certain computer/telephone equipment, for operations from 28 December 2025 to 31 December 2027.
What changed in detail
BOFiP actuality ACTU-2026-00140, published on 2 September 2026, updates DGFiP’s doctrine on the territorial VAT regimes of the overseas collectivities covered by article 73 of the Constitution, on two points.
First, article 100 of Loi n° 2026-103 du 19 février 2026 de finances pour 2026 extends to air transport the 0% VAT rate provided at 1° of 1 of article 295 of the Code général des impôts, which until then was limited to the supply of sea transport of passengers and goods effected within the overseas collectivities of Martinique, Guadeloupe and La Réunion. The provision applies to services supplied from 21 February 2026.
Second, on the basis of article 295 of the CGI and article 45 of Loi n° 2025-127 du 14 février 2025, the arrêté du 11 décembre 2025 amends the list of products at III of article 50 duodecies of Annexe IV to the CGI — the goods exempt from VAT in La Réunion alone. It adds certain goods regarded as first-necessity items and removes certain computer and telephone equipment. That provision applies to operations carried out from 28 December 2025 to 31 December 2027.
The revised commentary sits in BOI-TVA-GEO-20-20, signed by the director of tax legislation.
What it means
The air-transport extension closes an asymmetry with no obvious rationale: the same journey between two points in a DOM was zero-rated by sea and not by air. Carriers should read the boundary rather than the headline — the 0% rate attaches to transport effected within Martinique, Guadeloupe or La Réunion, so legs to the mainland or between collectivities still need their own analysis.
The La Réunion list change is the one with a backward edge. It bites on operations from 28 December 2025, which is long past, and it moves in both directions: a supplier of computer or telephone equipment that kept exempting on the old list has been under-charging for most of a year, with the correction falling on them rather than the customer. It also carries an expiry — 31 December 2027 — so it is a temporary list, not a new baseline.
Proof
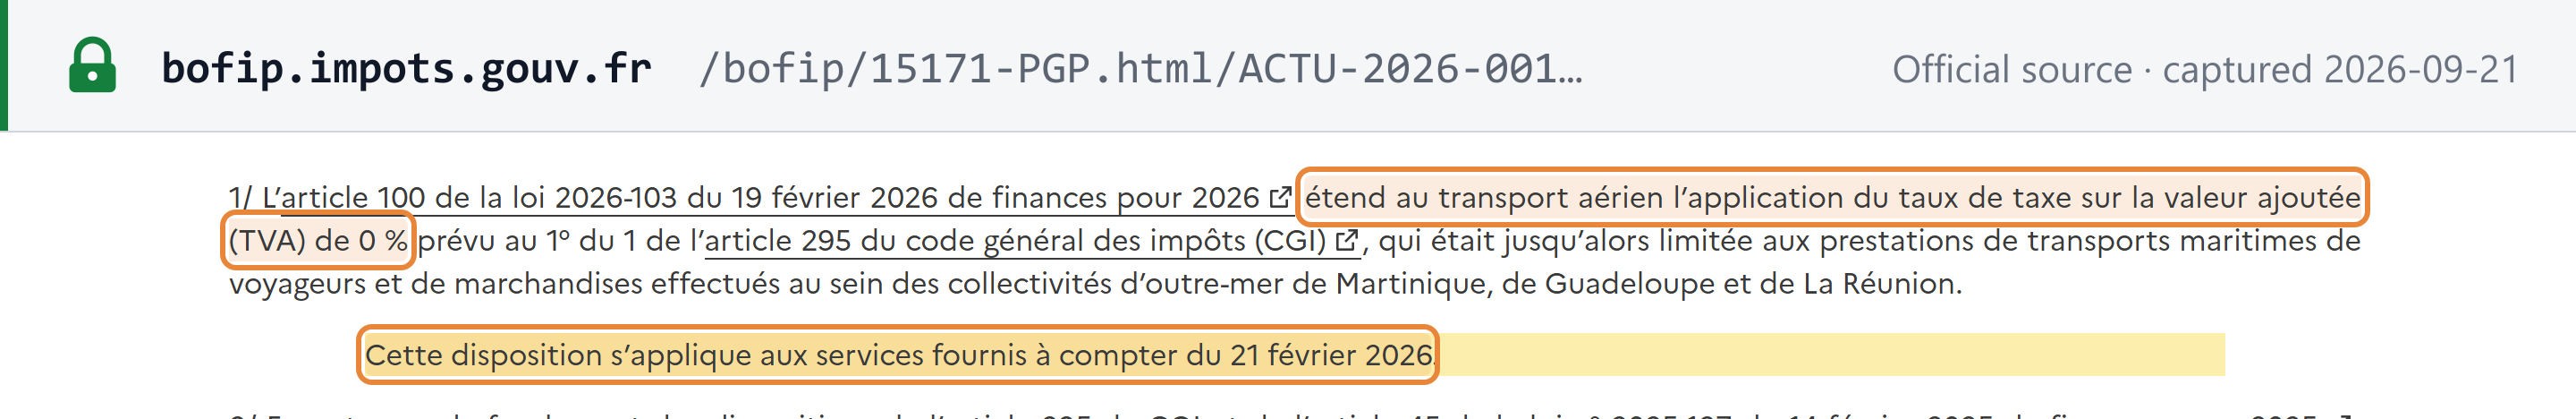
1/ L’article 100 de la loi 2026-103 du 19 février 2026 de finances pour 2026 étend au transport aérien l’application du taux de taxe sur la valeur ajoutée (TVA) de 0 % prévu au 1° du 1 de l’article 295 du code général des impôts (CGI), qui était jusqu’alors limitée aux prestations de transports maritimes de voyageurs et de marchandises effectués au sein des collectivités d’outre-mer de Martinique, de Guadeloupe et de La Réunion. Cette disposition s’applique aux services fournis à compter du 21 février 2026.1/ Article 100 of Law no. 2026-103 of 19 February 2026 on the finances for 2026 extends to air transport the application of the 0% value added tax (VAT) rate provided for at 1° of 1 of article 295 of the General Tax Code (CGI), which until then was limited to supplies of sea transport of passengers and goods effected within the overseas collectivities of Martinique, Guadeloupe and La Réunion. This provision applies to services supplied from 21 February 2026.
 Source snapshot of the official page. Open full size ↗
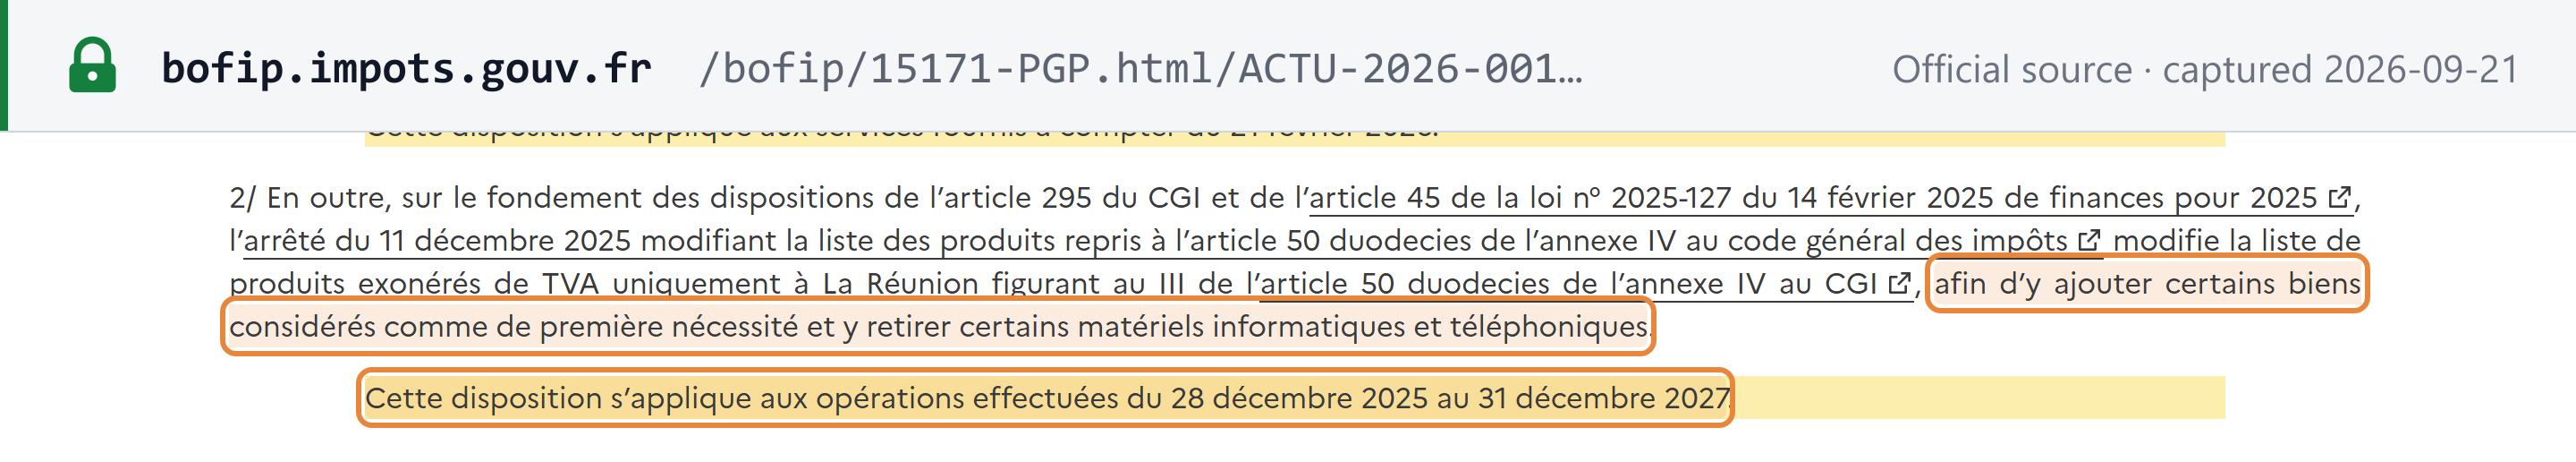
2/ En outre, sur le fondement des dispositions de l’article 295 du CGI et de l’article 45 de la loi n° 2025-127 du 14 février 2025 de finances pour 2025, l’arrêté du 11 décembre 2025 modifiant la liste des produits repris à l’article 50 duodecies de l’annexe IV au code général des impôts modifie la liste de produits exonérés de TVA uniquement à La Réunion figurant au III de l’article 50 duodecies de l’annexe IV au CGI, afin d’y ajouter certains biens considérés comme de première nécessité et y retirer certains matériels informatiques et téléphoniques. Cette disposition s’applique aux opérations effectuées du 28 décembre 2025 au 31 décembre 2027.2/ In addition, on the basis of the provisions of article 295 of the CGI and of article 45 of Law no. 2025-127 of 14 February 2025 on the finances for 2025, the order of 11 December 2025 amending the list of products set out in article 50 duodecies of Annex IV to the General Tax Code amends the list of products exempt from VAT in La Réunion only, appearing at III of article 50 duodecies of Annex IV to the CGI, in order to add to it certain goods regarded as of first necessity and to remove from it certain computer and telephone equipment. This provision applies to operations carried out from 28 December 2025 to 31 December 2027.
 Source snapshot of the official page. Open full size ↗