France confirms fossil-fuel boiler works get no reduced VAT rate, and moves reduced-rate certification onto the quote or invoice
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 9 September 2026
- Authority
- Direction générale des Finances publiques (DGFiP) — BOFiP
- Systems
- Invoicing, Tax engine
- Verified
- Fetched from official source · high confidence
Builders, installers and heating engineers carrying out renovation, energy-improvement or maintenance works on French dwellings completed more than two years ago — and the customers who certify eligibility for the reduced rate.
Confirm invoicing/quote templates for energy-renovation works capture the client's in-document certification of reduced-rate eligibility, and that fossil-fuel-boiler works are billed at the standard VAT rate.
InvoicingTax engine
DGFiP published a finalised BOFiP doctrine update (ACTU-2026-00036) on 9 September 2026, following public consultation, on the scope of the 5.5% reduced VAT rate for energy-renovation works to dwellings under CGI art. 278-0 bis A. It confirms that works involving a boiler capable of using fossil fuels are excluded from both the 5.5% rate (art. 278-0 bis A) and the 10% rate for improvement/maintenance works (art. 279-0 bis) and fall under the standard rate, and that the client now certifies directly on the quote/invoice (rather than via a separate written attestation) that the conditions for the reduced rate are met.
What changed in detail
The Direction générale des Finances publiques published ACTU-2026-00036 on 9 September 2026, finalising the BOFiP commentary it opened for public consultation on 22 October 2025 on the reduced VAT rates for works on dwellings completed more than two years ago.
Article 278-0 bis A of the Code général des impôts taxes qualifying energy-renovation works at 5.5% — the fitting, installation, adaptation or maintenance of materials, equipment, appliances or systems intended to save energy or to use renewable energy. The arrêté du 4 décembre 2024 sets the nature, content and performance levels of those works.
Article 32 of Loi n° 2025-127 du 14 février 2025 excludes from the reduced rate any supply comprising the provision or installation of a boiler capable of using fossil fuels. The doctrine confirms that such works qualify for neither the 5.5% rate under article 278-0 bis A nor the 10% rate that article 279-0 bis allows, on conditions, for improvement, transformation, fitting-out and maintenance works: they fall under the standard rate.
Article 41 of the same finance law removes the requirement for the recipient of the supply to attest in writing that the conditions of article 278-0 bis A or article 279-0 bis are met. The client now certifies directly on the quote or the invoice that those conditions are satisfied. The publication also clarifies the reverse charge under article 283, 2 nonies of the CGI for construction works carried out on a building by a subcontractor.
What it means
Two separate things landed in one publication, and only one of them is about rates. The boiler exclusion is a tax-engine question: whether a job is 5.5%, 10% or 20% now turns on an attribute of the appliance — can it burn a fossil fuel — rather than on the category of work. A hybrid or gas-ready installation sits on the wrong side of that line even when the rest of the job is plainly energy renovation, and the exclusion reaches the 10% rate too.
The certification change is an invoicing question, and the cheaper one to get wrong. The separate written attestation is gone, which sounds like a simplification and is really a relocation: the evidence that a reduced rate was justified now sits on the document itself. A quote template that still refers to a detached attestation form leaves the rate unsupported on audit.
Proof
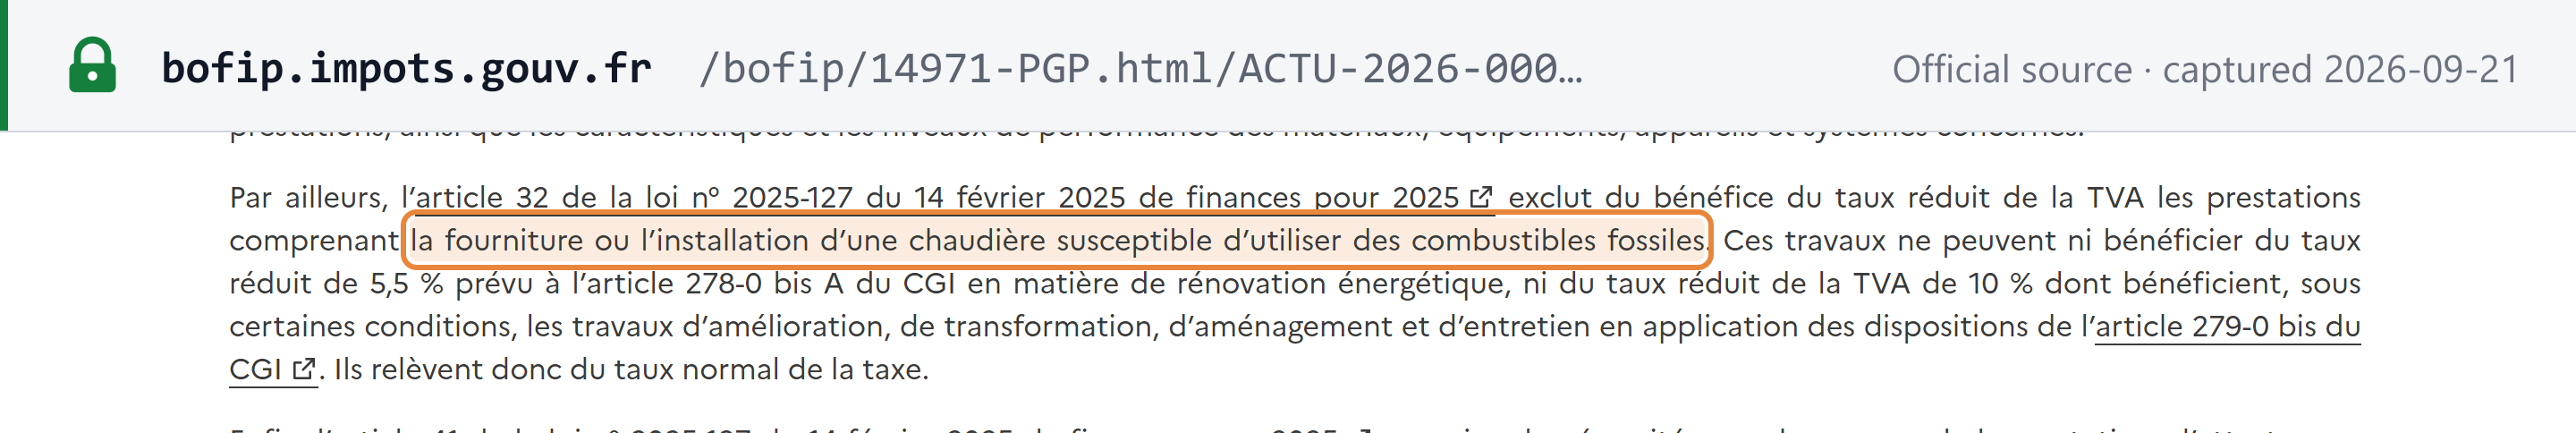
Par ailleurs, l’article 32 de la loi n° 2025-127 du 14 février 2025 de finances pour 2025 exclut du bénéfice du taux réduit de la TVA les prestations comprenant la fourniture ou l’installation d’une chaudière susceptible d’utiliser des combustibles fossiles. Ces travaux ne peuvent ni bénéficier du taux réduit de 5,5 % prévu à l’article 278-0 bis A du CGI en matière de rénovation énergétique, ni du taux réduit de la TVA de 10 % dont bénéficient, sous certaines conditions, les travaux d’amélioration, de transformation, d’aménagement et d’entretien en application des dispositions de l’article 279-0 bis du CGI. Ils relèvent donc du taux normal de la taxe.Moreover, article 32 of Law no. 2025-127 of 14 February 2025 on the finances for 2025 excludes from the benefit of the reduced VAT rate supplies comprising the provision or installation of a boiler capable of using fossil fuels. Those works can benefit neither from the reduced rate of 5.5% provided for by article 278-0 bis A of the CGI on energy renovation, nor from the reduced VAT rate of 10% from which works of improvement, transformation, fitting-out and maintenance benefit, under certain conditions, under the provisions of article 279-0 bis of the CGI. They therefore fall under the standard rate of the tax.
 Source snapshot of the official page. Open full size ↗
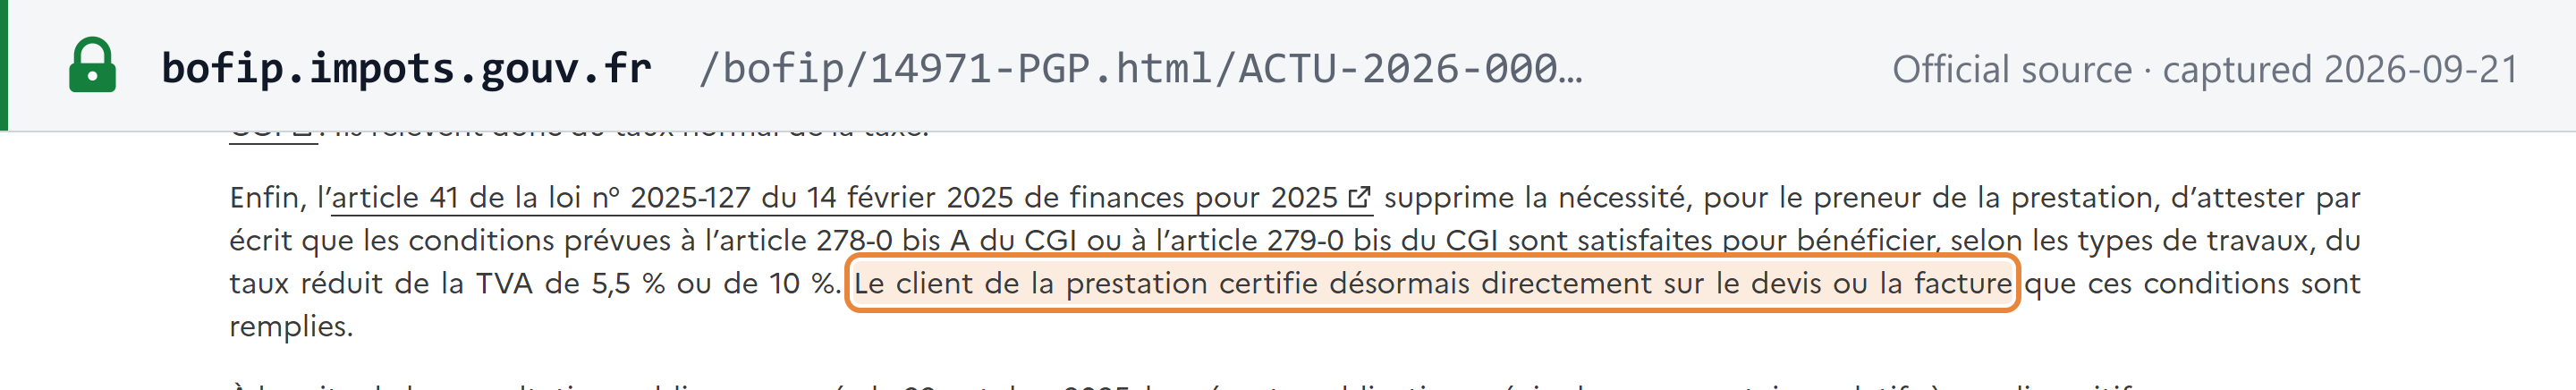
Enfin, l’article 41 de la loi n° 2025-127 du 14 février 2025 de finances pour 2025 supprime la nécessité, pour le preneur de la prestation, d’attester par écrit que les conditions prévues à l’article 278-0 bis A du CGI ou à l’article 279-0 bis du CGI sont satisfaites pour bénéficier, selon les types de travaux, du taux réduit de la TVA de 5,5 % ou de 10 %. Le client de la prestation certifie désormais directement sur le devis ou la facture que ces conditions sont remplies.Finally, article 41 of Law no. 2025-127 of 14 February 2025 on the finances for 2025 removes the need for the recipient of the supply to attest in writing that the conditions laid down in article 278-0 bis A of the CGI or in article 279-0 bis of the CGI are met in order to benefit, according to the type of works, from the reduced VAT rate of 5.5% or 10%. The client of the supply now certifies directly on the quote or the invoice that those conditions are fulfilled.
 Source snapshot of the official page. Open full size ↗