France abolishes the simplified VAT regime (RSI) from 1 January 2027
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Compliance
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 22 September 2026
- Effective
- 1 January 2027
- Authority
- Direction générale des Finances publiques (DGFiP)
- Systems
- Reporting, ERP
- Verified
- Fetched from official source · high confidence
French businesses currently on the régime simplifié d'imposition (RSI) for VAT — they move to the régime réel normal, filing quarterly CA3 returns up to EUR 1,000,000 turnover (EUR 1,100,000 in the current year) and monthly above that. The agricultural simplified regime is unaffected.
Move RSI businesses to quarterly or monthly CA3 filing from January 2027 and file the final CA12 for 2026 by 4 May 2027.
ReportingERP
France's DGFiP announced on 22 September 2026 that article 38 of the loi de finances pour 2025 abolishes the simplified VAT regime (régime simplifié d'imposition, RSI) from 1 January 2027. Businesses on the RSI move to the régime réel normal and file quarterly CA3 returns where turnover does not exceed EUR 1,000,000 in the previous year (or EUR 1,100,000 in the current year), and monthly returns above those thresholds. The final annual CA12 return for 2026 remains due by 4 May 2027. The simplified regime for agricultural operators is unaffected.
What changed in detail
France’s DGFiP announced on 22 September 2026 that article 38 of the loi de finances pour 2025 abolishes the simplified VAT regime (régime simplifié d’imposition, RSI) from 1 January 2027. Businesses currently on the RSI move to the régime réel normal: they file quarterly CA3 returns where turnover does not exceed EUR 1,000,000 in the previous year (or EUR 1,100,000 in the current year), and monthly returns above those thresholds. The final annual CA12 return for 2026 remains due by 4 May 2027. The simplified regime for agricultural operators is unaffected.
What it means
Every RSI business needs a filing-frequency change, not an opt-in — this is a wholesale abolition, not a threshold adjustment some businesses can stay under. The one deadline that survives the transition is the final CA12 for 2026, still due 4 May 2027, so year-end 2026 processes should follow the old annual mechanics one last time even as CA3 filing switches to quarterly or monthly from January 2027. Confirm turnover against the EUR 1,000,000 / 1,100,000 split now, since it decides whether a given business lands on quarterly or monthly filing from day one of the new regime.
Proof
L'article 38 de la loi de finances 2025 supprime, à compter du 1er janvier 2027, le régime simplifié d'imposition (RSI) en matière de TVA.Article 38 of the 2025 Finance Act abolishes, from 1 January 2027, the simplified VAT assessment regime (RSI).
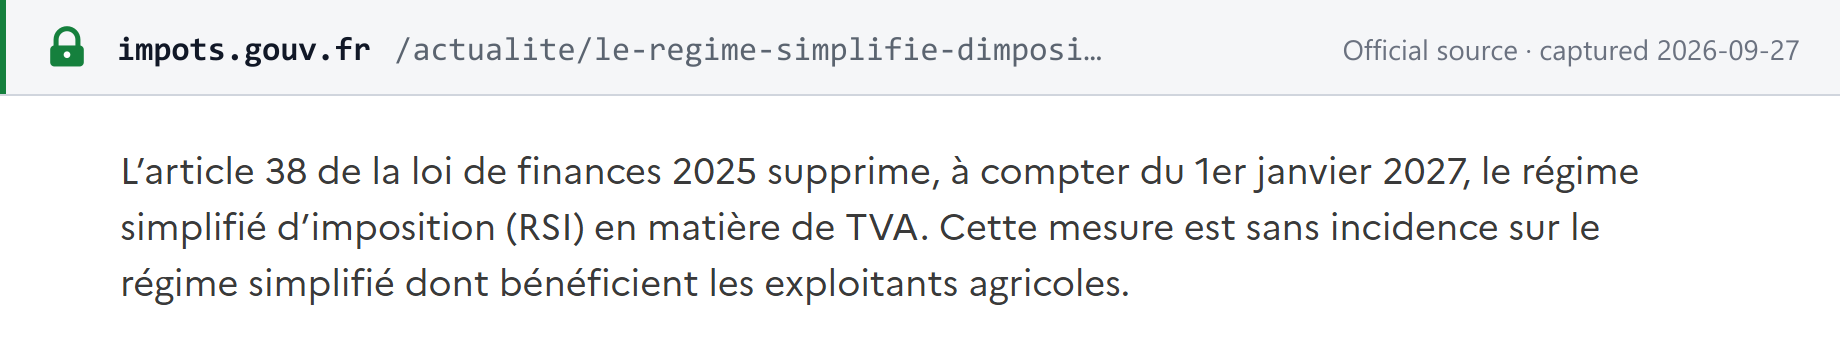 Source snapshot of the official page. Open full size ↗